What is the market overview and industry significance of the Inground Swimming Pools Market?
The Inground Swimming Pools Market represents a vital segment of residential and commercial infrastructure, valued at 7.89 Billion in 2026. This sector encompasses permanent aquatic installations requiring complex excavation, reinforced concrete, fiberglass shells, or heavy-duty vinyl liners. Regulatory compliance with the Association of Pool & Spa Professionals (APSP) and local zoning boards dictates structural integrity and bather safety across global jurisdictions.
What are the primary structural growth drivers, restraints, challenges, and opportunities shaping the sector?
Our analysis indicates that rising disposable incomes and home renovation booms act as key structural growth drivers. Conversely, severe supply chain bottlenecks for raw polyester resins and strict municipal water conservation mandates serve as primary restraints. Industry participants like Latham Pool Products Inc. navigate these logistical hurdles by expanding localized manufacturing footprints to capture untapped opportunities in suburban retrofitting.
The Shift Toward Smart Automation: Emerging trends and growth patterns
Industry trends highlight an accelerated migration toward IoT-enabled variable-speed pumps, automated chemical feeders, and energy-efficient heat exchangers. Based on our research, consumers increasingly demand sustainable solutions, driving adoption for advanced filtration systems. Companies like Hydropool Industries Inc. leverage these patterns to introduce eco-conscious aquatic designs that reduce overall utility consumption for end-users.
How did the COVID-19 pandemic impact the Inground Swimming Pools Market and shape its recovery trajectory?
The pandemic triggered an unprecedented surge in demand as remote work drove homeowners to invest in backyard leisure spaces. Thursday Pools LLC and similar innovators adapted to supply chain disruptions by scaling fiberglass mold production. The subsequent recovery trajectory stabilized around premium outdoor living investments, proving that pandemic-era behavioral shifts left a permanent upward mark on baseline valuations.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
The competitive landscape features moderate market concentration, balanced between specialized manufacturers and nationwide builders. Key players such as Anthony and Sylvan Pools Corporation and San Juan Products Inc. compete through proprietary composite formulations and extensive dealer networks. Strategic dynamics heavily favor firms offering turnkey warranties and rapid installation times to outpace regional competitors.
Executive Summary: High-level synthesis of key findings for the Inground Swimming Pools Market
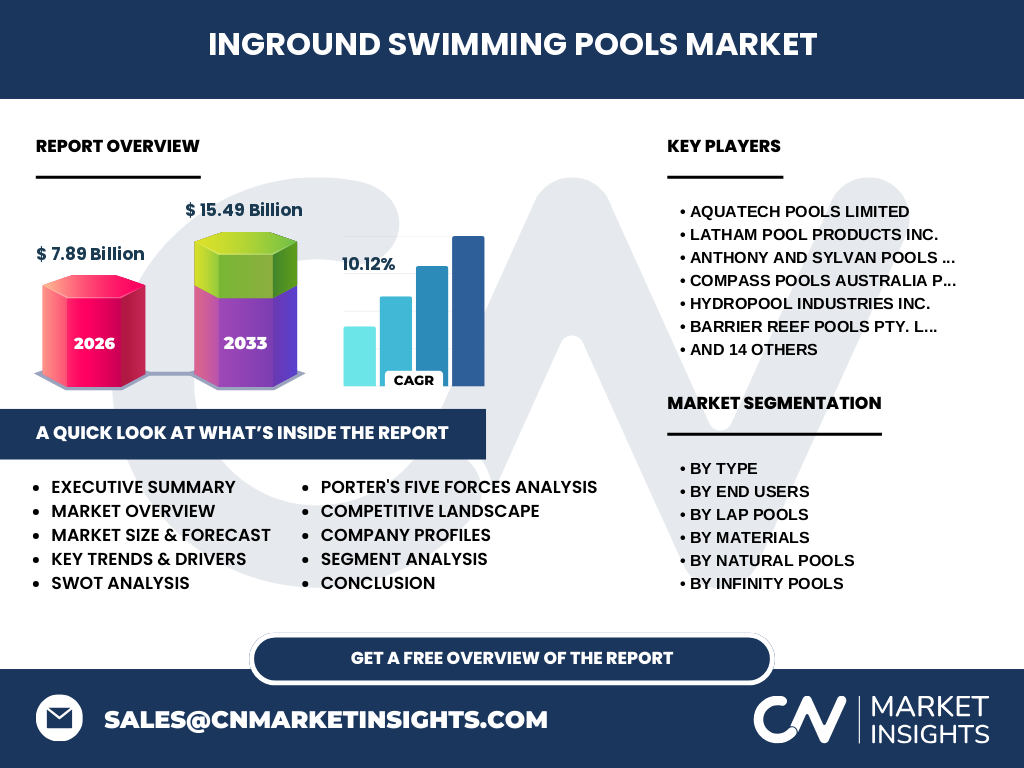
Our comprehensive report reveals that the Inground Swimming Pools Market is poised for robust expansion, scaling from 7.89 Billion in 2026 to 15.49 Billion by 2033 at a notable CAGR of 10.12%. Accelerated by technological integration and lifestyle shifts, the sector offers high-yield opportunities for stakeholders willing to invest in advanced manufacturing and eco-friendly filtration technologies.
Projected Growth Trajectory: Market forecast from 2027 to 2033
The data suggests sustained economic momentum, projecting the market to expand from 7.89 Billion to 15.49 Billion over the forecast window. Achieving a steady 10.12% CAGR from 2027 to 2033, this trajectory reflects robust consumer spending in affluent suburban enclaves and expanding commercial hospitality resorts requiring high-end custom installations.
Segmentation Analysis: Breaking down categories and their market roles
Market segmentation spans multiple categories: By Type (Inground Pools, Infinity Pools, Lap Pools, Natural Pools); End Users (Residential, Commercial, Public, Hospitality); Lap Pools (Indoor, Outdoor, Endless, Dual-Lane, Heated, Custom-Built); Materials (Concrete, Vinyl); Natural Pools (Regeneration Zone, Plant Filtered, Gravel Bed Filtration, Biofilm-Based, Hybrid, Swimming Pond); and Infinity Pools (Overflow Edge, Vanishing Edge, Perimeter Overflow, Knife Edge, Lautner Edge, Glass Wall). Each segment fulfills distinct architectural and functional requirements across global projects.
Regional Market Analysis: Geographic distribution and performance across global territories
Geographic performance is heavily concentrated in regions with favorable year-round warm climates and high disposable incomes. North America dominates global revenue share, supported by robust residential construction sectors. Meanwhile, APAC exhibits rapid growth spurred by expanding luxury hospitality developments and urban real estate projects requiring specialized engineering from regional leaders like Compass Pools Australia Pty. Ltd.
In-Depth Regional Review: Detailed examination of key regional markets
North American markets thrive on suburban backyard transformations, whereas European markets prioritize eco-friendly natural and biofilm-filtered pools due to stringent environmental regulations. In the Southern Hemisphere, Australian hubs drive technical innovations in composite fiberglass manufacturing, spearheaded by firms like Barrier Reef Pools Pty. Ltd., navigating unique soil conditions and strict local council building codes.
Company Profiles: Strategic positioning of leading industry participants
Market leaders occupy distinct strategic niches: Leisure Pools USA and Imagine Pools LLC focus on premium fiberglass shell durability and lifetime structural warranties. Meanwhile, Blue Haven Pools and Spas Inc. and Sun Pools Inc. leverage regional franchise networks to provide customized concrete and gunite designs tailored to specific architectural and geological demands.
Porter's Five Forces Analysis: Competitive forces assessment
Industry rivalry remains intense among established regional builders, while the threat of new entrants is mitigated by high initial capital requirements for excavation equipment and specialized molds. Bargaining power of suppliers is moderate, constrained by raw material costs for vinyl and fiberglass resins. Buyer power is counterbalanced by the specialized engineering expertise required for complex custom builds.
SWOT Analysis: Strengths, weaknesses, opportunities, and threats in the sector
Key strengths include high product durability and strong emotional consumer appeal. Weaknesses involve high upfront capital costs and vulnerability to weather-related installation delays. Opportunities lie in smart automation integration and commercial hospitality expansions. Threats encompass stringent municipal water usage restrictions and volatile raw material prices for concrete and polymer resins.
Value Chain Analysis: Industry structure and value flow from raw materials to end-users
The value chain initiates with chemical and raw material suppliers providing silica, fiberglass rovings, and vinyl polymers. Mid-stream manufacturers such as Freedom Pools Pty. Ltd. and Tallman Pools Inc. fabricate structural components. Downstream distribution relies on certified local dealers, landscape architects, and installation contractors who deliver the finished aquatic asset to residential and commercial end-users.
Investment Insights: Strategic recommendations and high-potential areas
Investors should direct capital toward automated maintenance technologies and sustainable natural pool filtration systems. High-potential areas include expanding manufacturing capacities for fiberglass composite shells to reduce freight logistics hurdles. Collaborating with regional distributors provides a resilient pathway to capture rising demand in high-growth suburban and luxury hospitality markets.
Conclusion and Key Takeaways for Industry Stakeholders
The Inground Swimming Pools Market demonstrates exceptional resilience and growth, driven by a projected 10.12% CAGR reaching 15.49 Billion. Stakeholders must prioritize technological agility, regulatory compliance, and eco-friendly innovations. Companies that successfully balance premium customization with streamlined manufacturing will capture disproportionate market share in this expanding landscape.
Research Methodology: How baseline estimates are triangulated
Our rigorous methodology triangulates baseline estimates by synthesizing trade registry data, primary stakeholder interviews with executives from firms like Swim USA Fiberglass Pools LLC and Alaglas Fiberglass Pools LLC, and secondary macroeconomic indicators. Quantitative regression models cross-reference housing starts and municipal building permits to ensure highly accurate market sizing.
Scope of the Report: Coverage parameters and analytical limitations
This report covers global market dynamics for inground swimming pools from 2026 through 2033, analyzing segmentation by type, material, end user, and geography. Limitations include potential unforeseen macroeconomic disruptions, localized municipal regulatory shifts, and unquantified underground geological anomalies that could impact regional construction timelines and cost structures.
Recent Developments: Company announcements, product launches, partnerships, and strategic moves
Recent industry momentum features aggressive vertical integration and strategic acquisitions. Key innovators like Viking Pools LLC and LoneStar Fiberglass Pools LLC have expanded their automated manufacturing lines and forged partnerships with smart-home technology providers. These strategic moves enhance pool telemetry integration, offering end-users advanced remote diagnostic capabilities for chemical balancing.