What is the scope and industry significance of the Synthetic Diamond Market?
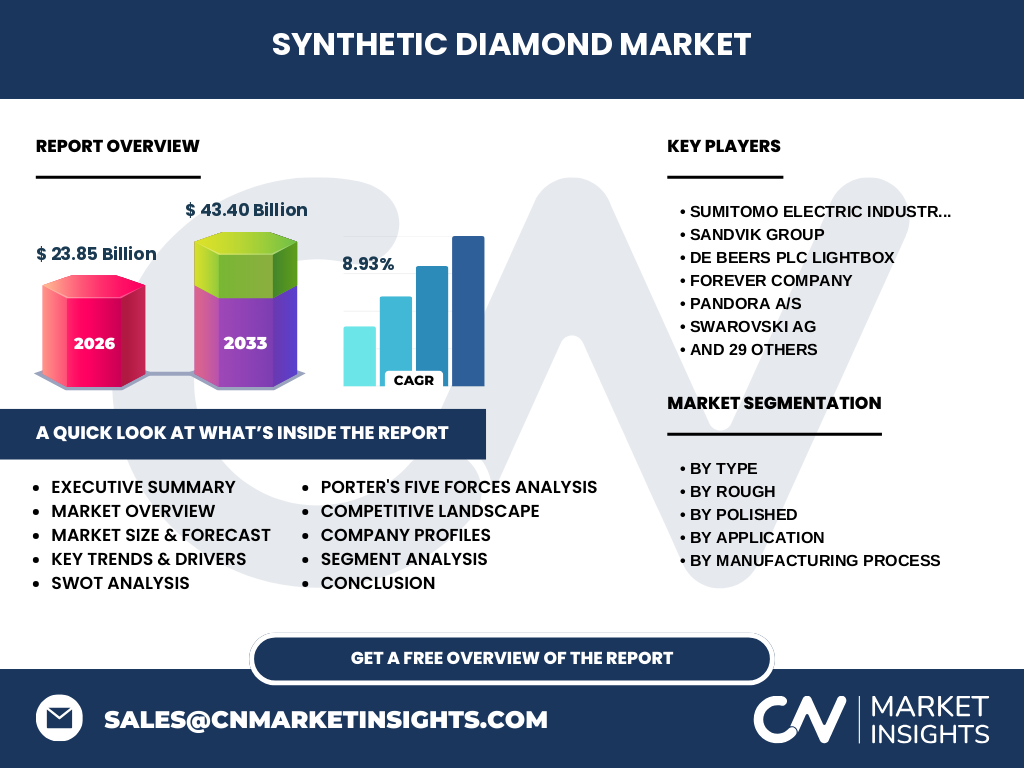
Our analysis indicates that the Synthetic Diamond Market is experiencing a paradigm shift, valued at $23.85 Billion in 2026. This valuation underscores the critical transition from mined gem-grade stones to technologically superior lab-grown alternatives utilized heavily in High-End Electronics, Surgical Machinery, and Quantum Computing. Industrial supply chains now heavily rely on these synthesized materials for extreme durability.
Structural Growth Drivers and Restraints in Synthetic Diamond Market
The market is propelled by surging demand for thermal management components in High-End Electronics and precision optics in Laser And X Ray systems. However, capital-intensive facility setups for High Pressure, High Temperature (HPHT) and Chemical Vapor Deposition (CVD) act as entry barriers. Companies like Element Six UK Ltd. and Diamond Foundry continuously navigate these restraints by scaling proprietary reactor technologies.
Emerging Trends and Growth Patterns in Synthetic Diamond Market
The shift toward sustainable luxury and semiconductor innovation defines current Synthetic Diamond Market industry trends. Brands like De Beers plc Lightbox and Pandora A/S are mainstreaming lab-grown gems, while industrial adopters utilize pure diamond wafers for next-generation power electronics. This dual-track adoption accelerates commercial penetration across both consumer retail and advanced hardware manufacturing.
Pandemic Aftershocks and Recovery Trajectory
The COVID-19 pandemic severely disrupted global supply chains, halting HPHT and CVD reactor operations across key manufacturing hubs in Asia and Europe. Nevertheless, our research shows a robust post-pandemic rebound. Pent-up consumer demand for accessible luxury jewelry and accelerated digital transformation in Quantum Computing rapidly restored market momentum toward a projected $43.40 Billion by 2033.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a distinct split between high-volume gem producers and precision industrial innovators. Industry titans such as Sumitomo Electric Industries Ltd., Sandvik Group, and Henan Huanghe Whirlwind Co Ltd. dominate industrial-grade outputs, whereas direct-to-consumer pioneers like Clean Origin and James Allen capture lucrative retail margins through transparent marketing and scalable gem-quality inventories.
Executive Summary of Synthetic Diamond Market
Driven by a robust 8.93% CAGR from 2027 to 2033, the Synthetic Diamond Market represents a high-growth sector spanning industrial applications and luxury retail. Surging from $23.85 Billion in 2026 to $43.40 Billion by 2033, the market offers lucrative entry points for stakeholders investing in advanced Chemical Vapor Deposition and HPHT manufacturing infrastructure.
Market Forecast and Valuation Trajectory (2027 to 2033)
Based on our econometric modeling, the Synthetic Diamond Market market size is poised for accelerated expansion, scaling from $23.85 Billion in 2026 to reach $43.40 Billion by 2033 at a consistent 8.93% CAGR. This growth is underpinned by rising adoption in Surgical Machinery and strict environmental regulations favoring lab-grown alternatives over traditional mining.
Segmentation Analysis Across Product and Application Categories
Market segmentation evaluates Polished versus Rough types, further sub-divided into Synthetic Gem-Quality Rough and Industrial Rough Diamonds. Application vectors include High-End Electronics, Laser And X Ray, and Quantum Computing. Manufacturing is split between High Pressure High Temperature and Chemical Vapor Deposition, allowing specialized firms like WD Lab Grown Diamonds to target specific industrial tolerances.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with Asia-Pacific leading in volume due to dense manufacturing ecosystems in China, driven by giants like Zhongnan Diamond Co Ltd. and Zhengzhou Sino-Crystal Diamond Co Ltd. Meanwhile, North America and Europe represent the largest consumer hubs for gem-quality polished stones, heavily influenced by regulatory oversight from bodies monitoring ethical jewelry sourcing and green marketing claims.
In-Depth Regional Review of Production and Consumption Hubs
Asia-Pacific commands industrial synthesis via low-cost energy grids and advanced HPHT press installations. Conversely, North American markets heavily emphasize technological integration, with companies like Applied Diamond Inc. supplying heat sinks for defense and telecommunications. European markets focus on sustainable luxury jewelry retail, balancing strict import compliance with eco-conscious consumer preferences.
Company Profiles and Strategic Positioning
Major industry players strategically differentiate through proprietary synthesis methods. Element Six UK Ltd. focuses on high-purity industrial CVD diamonds for cutting tools, while Swarovski AG and Pandora A/S integrate sustainable lab-grown gems into mainstream jewelry collections. Specialty players like Iljin Diamond Co Ltd. and Adamas One Corp concentrate on tailored abrasive solutions and specialized gemstone manufacturing.
Porter's Five Forces Assessment
Our analysis indicates moderate-to-high competitive rivalry driven by rapid technological advancements in Chemical Vapor Deposition. Threat of substitution from mined diamonds remains low due to identical chemical properties, but threat of new entrants is checked by high initial capital expenditures for high-grade synthesis reactors, favoring established conglomerates like Sandvik Group.
SWOT Analysis of the Synthetic Diamond Sector
Strengths include superior thermal conductivity and ethical provenance. Weaknesses involve high energy consumption during production. Opportunities lie in expanding thermal management roles within Quantum Computing and High-End Electronics. Threats stem from potential price commoditization of gem-grade stones as global CVD production capacity scales exponentially.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with carbon feedstock sourcing, progressing through capital-intensive HPHT and CVD reactor synthesis. Midstream involves laser cutting, precision polishing, and grading. Downstream distribution channels supply industrial equipment makers and jewelry retailers like Blue Nile Inc. and Queensmith, ensuring seamless delivery to end-users.
Investment Insights and High-Potential Growth Areas
Investors should target pure-play Chemical Vapor Deposition innovators capable of producing electronic-grade diamond wafers. The data highlights Quantum Computing and semiconductor thermal management as high-margin frontiers offering superior returns compared to commoditized gem-grade polishing sectors.
Conclusion and Key Takeaways for Market Entrants
The Synthetic Diamond Market analysis demonstrates a robust transition toward high-tech industrial applications and ethically conscious consumer markets. With a valuation reaching $43.40 Billion by 2033, strategic investments in advanced manufacturing processes will determine long-term market leadership and profitability.
Research Methodology and Baseline Triangulation
Our findings are derived from rigorous triangulation combining primary stakeholder interviews with C-suite executives, secondary trade registry data, and macroeconomic indicators from bodies such as international trade commissions. This methodology ensures precise baseline estimates for market sizing starting from $23.85 Billion in 2026.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for synthetic diamonds from 2026 to 2033, evaluating both Polished and Rough categories across key manufacturing and consumption regions. Limitations exclude black-market smuggling data and unverified artisanal lab outputs, focusing exclusively on audited commercial enterprises.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features aggressive capacity expansions by Diamond Foundry and strategic retail partnerships between lab-grown brands and traditional jewelry chains like Chatham Inc. and ALTR Created Diamonds. These moves underscore a concerted industry effort to secure supply chain resilience and enhance consumer trust.