Market overview of the Metal Biocides Market
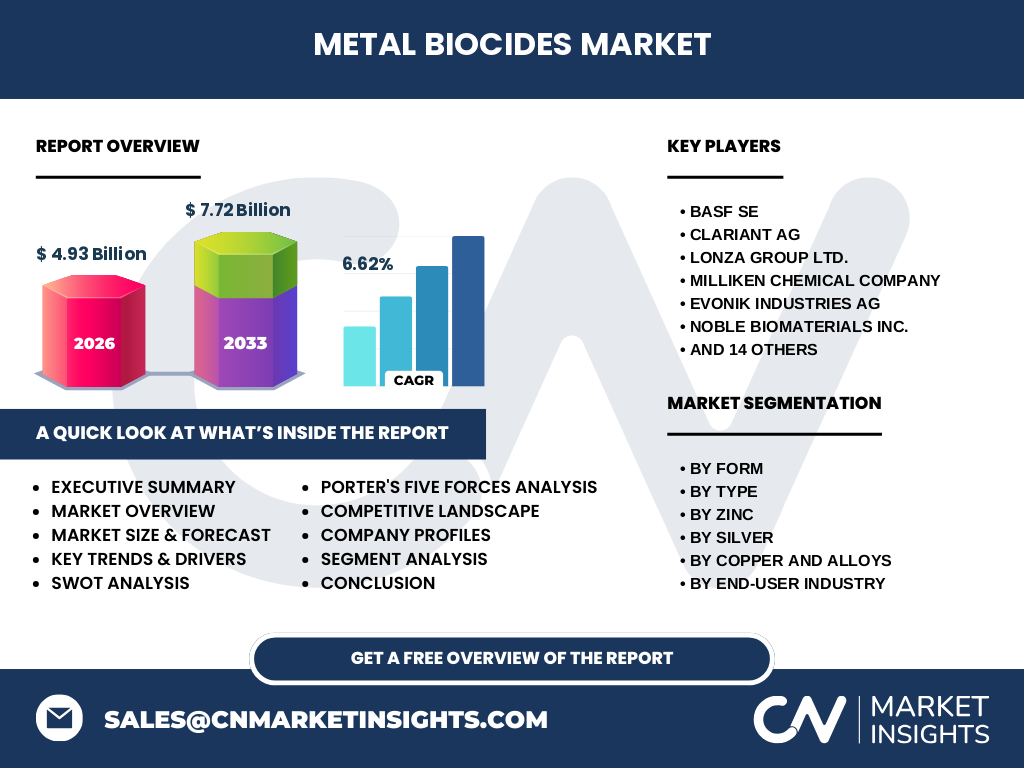
Our proprietary research values the Metal Biocides Market at $4.93 Billion in 2026. This specialized sector encompasses antimicrobial compounds derived from active metals, playing a critical role in mitigating biofouling, microbial contamination, and pathogen transmission across industrial and consumer applications.
What are the structural growth drivers and market restraints?
The market is propelled by stringent hygiene regulations from bodies like the EPA and ECHA, alongside surging demand for antimicrobial coatings. However, stringent toxicological reviews and raw material price volatility for inputs like silver and copper act as primary restraints.
Emerging trends and growth patterns in the Metal Biocides Market
Industry trends highlight a decisive shift toward eco-friendly formulations and nanotechnology integration. Major chemical innovators are prioritizing nanoparticle-infused zinc and silver variants to enhance efficacy in ultra-thin coatings without compromising structural substrate integrity.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically accelerated demand for antimicrobial medical devices and healthcare textiles. While supply chain bottlenecks initially constrained output at major logistics hubs, the post-pandemic recovery trajectory has solidified antimicrobial additives as baseline requirements in commercial real estate.
Competitive benchmarking and strategic dynamics
The market features an intensely consolidated competitive landscape. Industry leaders such as BASF SE, Lonza Group Ltd., and LANXESS Deutschland GmbH leverage vast R&D pipelines, whereas specialty players like SeriTouch Ltd. and Noble Biomaterials Inc. dominate niche textile applications.
Executive summary of key findings
Our analysis indicates the Metal Biocides Market industry trends point toward robust expansion, driven by urbanization and healthcare demands. The market is projected to surge from $4.93 Billion in 2026 to $7.72 Billion by 2033, expanding at a compound annual growth rate of 6.62%.
Long-term market forecast from 2027 to 2033
Driven by accelerating adoption in emerging economies and stringent sanitation mandates, the market is set to expand rapidly. Based on our forecasting models, the sector will maintain a steady 6.62% CAGR, scaling from a baseline of $4.93 Billion in 2026 to reach $7.72 Billion by 2033.
Segmentation analysis by form, type, and end-user industry
The market segments into Liquid, Powder, and Gel formulations, deployed across Silver, Copper and Alloys, and Zinc types. Key end-user verticals encompass Building And Construction, Medical And Healthcare, Textile And Apparel, Transportation, Wood Preservation, Agriculture, and specialized industrial applications.
Geographic distribution and regional market analysis
Regional performance varies significantly based on local regulatory stringency and manufacturing density. Asia-Pacific leads consumption due to extensive textile and construction output, while North America and Europe maintain dominance in high-value medical and healthcare applications enforced by strict environmental mandates.
In-depth regional review of high-growth territories
Asia-Pacific emerges as the primary volume driver, supported by expansive manufacturing bases in China and India. Meanwhile, Western European markets, governed by the Biocidal Products Regulation (BPR), exhibit high demand for sustainable copper and zinc oxide formulations in architectural coatings.
Company profiles and strategic positioning of leading players
Industry giants like The Dow Chemical Company, DuPont de Nemours Inc., and Evonik Industries AG focus on high-throughput synthesis and global supply chain integration. Concurrently, specialized entities such as Troy Corporation and Clariant AG target proprietary biocide blends for paints and coatings.
Porter's Five Forces analysis of competitive intensity
Rivalry is high among established chemical titans, while the threat of substitutes remains moderate due to the unmatched efficacy of metal ions. Supplier power is dictated by raw metal commodity pricing, whereas buyer power is neutralized by specialized, proprietary formulation requirements.
SWOT analysis of the Metal Biocides Market
Key strengths include broad-spectrum antimicrobial efficacy and durability. Weaknesses involve high raw material costs and stringent regulatory hurdles. Opportunities lie in emerging bio-based hybrid metals, while threats stem from potential environmental toxicity classifications by regulatory agencies.
Value chain analysis from raw materials to end-users
The value chain initiates with mining and refining of base metals like zinc, copper, and silver. Refined materials undergo chemical synthesis by tier-one enterprises like Solvay SA and AkzoNobel N.V., before formulation into end-user products for construction, healthcare, and agricultural sectors.
Investment insights and high-potential growth areas
Strategic investments should target silver-based medical textiles and zinc oxide-infused architectural coatings. Companies possessing advanced nano-dispersion capabilities present prime acquisition targets for major chemical conglomerates seeking technological differentiation.
Conclusion and key takeaways for industry stakeholders
The Metal Biocides Market analysis confirms a lucrative growth trajectory, fueled by a 6.62% CAGR leading to $7.72 Billion by 2033. Success relies on navigating complex regulatory frameworks while innovating sustainable, high-efficacy metal formulations.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with C-suite executives at LANXESS and Lonza, and secondary macroeconomic indicators regarding construction and healthcare expenditures.
Scope of the report and coverage parameters
This report covers global consumption, production, and technological advancements across liquid, powder, and gel forms of silver, copper, and zinc biocides from 2026 through 2033. Excluded from this scope are purely organic, non-metal antimicrobial chemical classes.
Recent developments, partnerships, and strategic moves
Recent industry momentum features strategic acquisitions and eco-friendly product launches. For instance, companies like Corbion N.V. and Aarti Industries have optimized synthesis pathways to reduce carbon footprints, aligning with tightening global chemical regulations.