What is the market overview of the Close Task Orchestration Market?
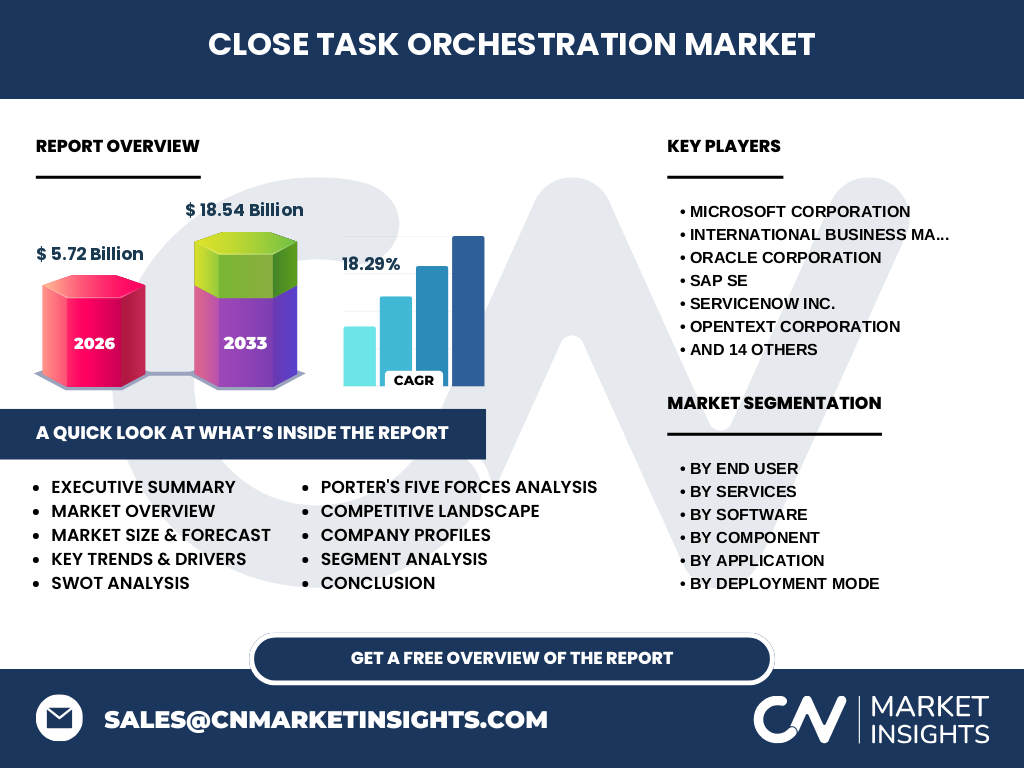
Our analysis indicates that the Close Task Orchestration Market is valued at 5.72 Billion in 2026. This sector encompasses advanced platforms governing automated workflows, transactional reconciliations, and mission-critical end-of-period closing procedures across complex enterprise IT ecosystems.
Key market drivers, restraints, challenges, and opportunities shaping Close Task Orchestration Market
Growth is propelled by regulatory compliance demands from bodies like the SEC and EBA, though integration friction with legacy mainframes remains a persistent constraint. Opportunities thrive in expanding hybrid deployment models for automated financial closing cycles.
Emerging trends and growth patterns in Close Task Orchestration Market
The shift toward intelligent automation and real-time operational analytics dominates current trends. Enterprises are rapidly adopting workflow orchestration platforms to eliminate manual latency in multi-step financial and IT administrative sequences.
How did the COVID-19 pandemic affect the Close Task Orchestration Market and shape its recovery trajectory?
The pandemic exposed vulnerabilities in distributed accounting and IT teams, accelerating digital transformation budgets. Organizations urgently deployed cloud-based task coordination solutions to maintain governance and audit readiness during remote-work mandates.
Competitive landscape and strategic dynamics in the Close Task Orchestration Market
The market features intense competition among enterprise software giants and pure-play automation specialists. Key players like Microsoft Corporation, SAP SE, and UiPath Inc. leverage proprietary AI integrations to capture market share.
Executive summary of the Close Task Orchestration Market
Our comprehensive research projects the market to surge from 5.72 Billion in 2026 to 18.54 Billion by 2033, expanding at a robust 18.29% CAGR. Enterprises prioritize cloud-native workflow engines to optimize operational efficiency and regulatory reporting.
Market forecast and projected growth trajectory from 2027 to 2033
Driven by accelerating digital transformation initiatives across global enterprises, the market is poised for explosive expansion, maintaining an 18.29% CAGR to reach 18.54 Billion by 2033, up from its 2026 baseline.
Segmentation analysis across end users, services, software, components, applications, deployment, and organization size
The market segments by end-user (BFSI, Healthcare, Retail, Manufacturing, IT and Telecom), services (Consulting, System Integration, Training, Managed), software (Workflow Orchestration, Task Scheduling, API Management, Monitoring), components, applications, deployment mode, and organization size.
Regional market analysis and geographic performance distribution
North America commands the largest market share due to early adoption of cloud automation and stringent regulatory mandates. Meanwhile, Asia-Pacific exhibits the highest incremental growth, fueled by rapid IT infrastructure modernization across emerging financial hubs.
In-depth regional review of key markets in Close Task Orchestration
In North America, high compliance scrutiny under Sarbanes-Oxley drives rapid adoption. In Europe, GDPR and localized labor regulations dictate strict data residency requirements, accelerating demand for hybrid deployment architectures and localized managed orchestration services.
Company profiles and strategic positioning of leading innovators
Industry leaders employ distinct strategies: ServiceNow Inc. and Pegasystems Inc. focus on enterprise workflow depth, while Automation Anywhere Inc. and Celonis SE emphasize intelligent task automation and process mining integration.
Porter's Five Forces analysis of competitive intensity
Competitive rivalry is high due to rapid innovation cycles among tech giants. Supplier power remains moderate, while buyer power is elevated as enterprises demand customizable, multi-tenant cloud orchestration frameworks with transparent pricing models.
SWOT analysis of the Close Task Orchestration Market
Strengths include high operational ROI and automated audit trails. Weaknesses involve high initial deployment costs. Opportunities lie in AI-driven predictive scheduling, while threats stem from rising cybersecurity vulnerabilities targeting API integration layers.
Value chain analysis from foundational infrastructure to end-user deployment
The value chain spans cloud infrastructure providers, core software developers offering workflow platforms, system integrators managing custom deployments, and enterprise end-users utilizing managed orchestration services for operational reporting.
Investment insights and high-potential areas for capital allocation
Investors should target niche vendors specializing in hybrid-cloud workflow orchestration and AI-powered monitoring software. The data suggests high growth velocity within the BFSI and healthcare verticals for compliance-driven automation tools.
Conclusion and key takeaways for industry stakeholders
The projected leap to 18.54 Billion by 2033 underscores that close task orchestration is no longer optional for large enterprises. Firms must invest in scalable cloud solutions to maintain compliance and operational agility.
Research methodology for baseline estimates and data triangulation
Our analysis triangulates data by combining primary interviews with C-level IT executives, exhaustive trade registry disclosures, and macroeconomic indicators, cross-referenced with enterprise software adoption metrics to ensure high forecast accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics from 2026 to 2033 across specified software, service, deployment, and end-user segments. Limitations include unforeseen macroeconomic disruptions and rapid shifts in proprietary enterprise cloud architectures.
Recent developments, partnerships, and strategic product launches
Recent market activity highlights major players like Oracle Corporation and WorkFusion Inc. integrating generative AI into task scheduling tools. Strategic partnerships between cloud providers and robotic process automation firms continue to reshape competitive boundaries.