What is the scope and industry significance of the Climbing Helmet Market?
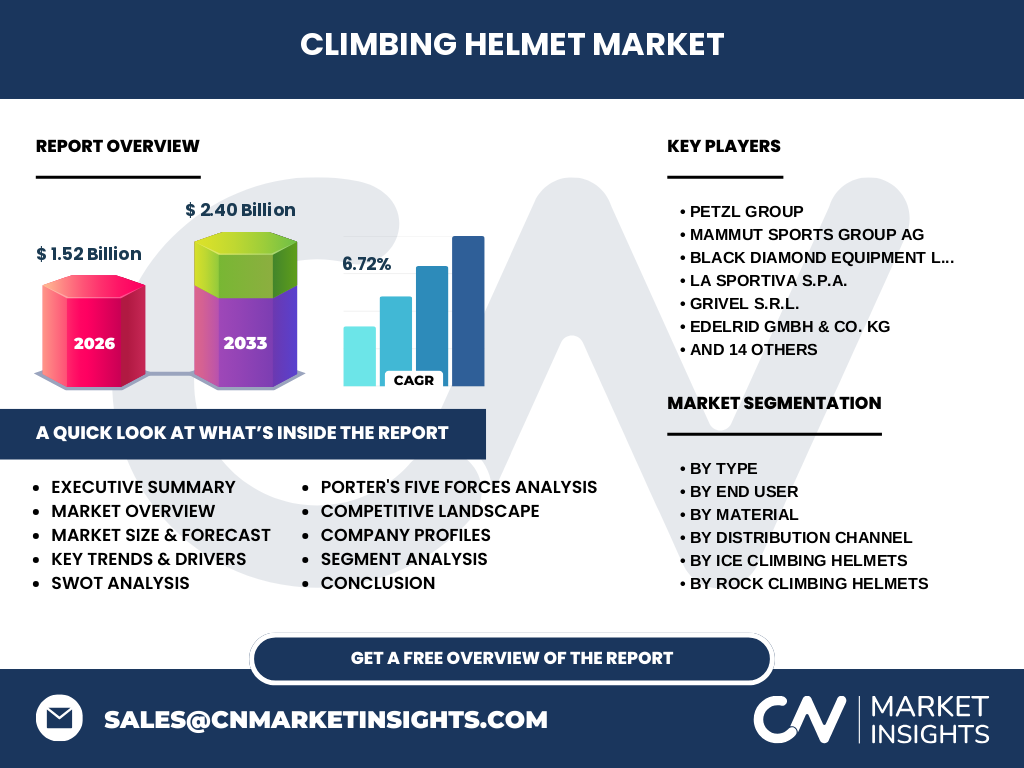
Our analysis indicates that the Climbing Helmet Market represents a critical safety equipment sector valued at 1.52 Billion in 2026. This industry encompasses specialized protective gear governed by stringent EN 12492 and UIAA 106 safety standards, safeguarding athletes against falling rock and impact hazards across global alpine and indoor venues.
What are the key market drivers, restraints, challenges, and opportunities shaping the Climbing Helmet Market?
Growth is propelled by rising participation in extreme adventure tourism, though strict regulatory compliance and high raw material costs for carbon fiber and polycarbonate act as restraints. Manufacturers find lucrative opportunities in integrating lightweight MIPS technology to mitigate rotational brain injuries during high-altitude multi-pitch ascents.
Structural Growth Drivers
The expansion of commercial indoor climbing gyms and the surging popularity of outdoor sport climbing are primary structural growth drivers. Consumers increasingly prioritize advanced head protection, prompting brands to utilize high-density foam and expanded polystyrene (EPS) for enhanced energy absorption during leader falls.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains originating from key manufacturing hubs, leading to temporary closures of specialty outdoor retail stores. However, the subsequent outdoor recreation boom catalyzed a sharp post-COVID recovery, accelerating direct-to-consumer e-commerce adoption across the industry.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features established innovators like Petzl Group, Mammut Sports Group AG, and Black Diamond Equipment Ltd., alongside specialized European players such as Grivel S.r.l. and EDELRID GmbH & Co. KG. Market concentration is moderate to high, with leaders focusing on proprietary shell durability and ultralight designs.
Executive Summary
Our comprehensive research forecasts the Climbing Helmet Market industry trends to expand significantly, reaching 2.40 Billion by 2033 at a robust 6.72% CAGR from 2027. Strategic investments in sustainable bio-resins and aerodynamic mountaineering profiles will dictate future market leadership.
Market Forecast 2027 to 2033
Driven by rising disposable incomes and surging adventure tourism in emerging economies, the market is projected to scale from its 2026 baseline of 1.52 Billion to 2.40 Billion by 2033. This trajectory reflects a steady 6.72% CAGR, underpinned by continuous product innovation.
Segmentation Analysis of the Climbing Helmet Market
The market is categorized into distinct segments: By Type (Rock Climbing Helmets, Ice Climbing Helmets, Mountaineering Helmets, Sport Climbing Helmets), By End User (Professional Climbers, Recreational Climbers), By Material (Polycarbonate, Fiberglass, Carbon Fiber, EPS, High-Density Foam), and By Distribution Channel (Online Stores, Specialty Outdoor Retailers, Sports Equipment Stores).
Geographic Distribution and Regional Market Performance
Regional performance varies based on proximity to major mountain ranges and consumer safety awareness. North America and Europe dominate consumption, leveraging established alpine rescue networks and mature specialty retail chains, while the Asia-Pacific region demonstrates the fastest emerging demand for entry-level gear.
In-Depth Regional Review
European markets benefit from rigorous CE certifications enforced by bodies like the UIAA, driving high replacement rates among alpine guides. Meanwhile, North American consumers show strong preference for multi-use hybrid helmets suitable for both traditional trad climbing and glacier travel.
Company Profiles and Strategic Positioning
Industry stalwarts like La Sportiva S.p.A., DMM International Ltd., and Singing Rock s.r.o. leverage rigorous European alpine testing grounds to refine their product portfolios. Brands such as KONG S.p.A. and SKYLOTEC GmbH focus heavily on industrial and professional vertical rescue segments alongside recreational climbing.
Porter's Five Forces Analysis
The threat of new entrants remains low due to stringent UIAA and CE certification hurdles and high tooling costs for polycarbonate injection molding. Supplier power is moderate, governed by raw material pricing for advanced composite fibers, while buyer power is tempered by safety-first purchasing criteria.
SWOT Analysis of the Industry
Key strengths lie in advanced shock-absorption material science, whereas weaknesses involve high seasonal inventory carrying costs. Opportunities abound in smart-helmet IoT integration for avalanche beacon telemetry, with regulatory liability and counterfeit safety gear posing persistent threats.
Value Chain Analysis
Value creation flows from petrochemical and composite raw material suppliers through injection-molding and assembly facilities. Products then route through freight hubs to specialty outdoor retailers and online fulfillment centers before reaching professional and recreational end-users.
Strategic Investment Insights
High-potential investment areas center on proprietary ventilation technologies and lightweight carbon fiber layups. Stakeholders should target partnerships with alpine gear distributors in high-growth tourism corridors to capture expanding recreational demand.
Conclusion and Key Takeaways
The Climbing Helmet Market market size expansion to 2.40 Billion by 2033 highlights a thriving safety-conscious consumer base. Companies investing in sustainable manufacturing and multi-standard certified protection will capture outsized market share during the 2027 to 2033 forecast period.
Research Methodology
Our baseline estimates are rigorously triangulated by combining global trade registry import-export data, primary stakeholder interviews with chief executive officers of firms like BEAL SARL and Trango LLC, and secondary macroeconomic indicators from outdoor recreation industry associations.
Scope of the Report
This report covers global revenue estimations and volume shipments from 2026 to 2033, analyzing material innovations, regional regulatory frameworks, and distribution channel dynamics. Excluded from this scope are industrial construction hard hats that lack mountaineering UIAA certifications.
Recent Developments in the Climbing Helmet Market
Recent strategic moves include Blue Ice Europe SAS and OCÚN s.r.o. launching ultralightweight alpine touring helmets optimized for ski-mountaineering. Concurrently, Edelweiss S.A. and Aludesign S.p.A. have expanded their eco-friendly packaging initiatives and automated QA testing lines.