What is the scope and industry significance of the Instant Grocery Market?
The Instant Grocery Market represents a transformative hyper-local fulfillment ecosystem engineered for ultra-fast delivery of essential goods. Our analysis indicates the market size reaches 12.68 Billion in 2026, driven by dense urban micro-fulfillment centers and dark store logistics that bypass traditional supply chain bottlenecks managed by regulatory bodies like the FDA.
Structural Growth Drivers and Restraints Shaping the Instant Grocery Market
Growth is accelerated by consumer demand for hyper-convenience, while logistical hurdles like urban traffic congestion and rising last-mile delivery labor costs act as primary restraints. Strategic investments in automated picking technology by innovators such as Ocado Retail Limited help mitigate these operational friction points.
Emerging Trends and Growth Patterns in the Instant Grocery Market
The sector is witnessing a rapid pivot toward predictive inventory analytics and eco-friendly electric fleet integration. Industry trends highlight how dark store operators leverage real-time SKU turnover data to optimize fresh food storage, reducing spoilage rates under strict municipal cold-chain compliance standards.
How did the COVID-19 pandemic permanently alter the Instant Grocery Market trajectory?
The pandemic catalyzed a structural shift in consumer purchasing habits, catapulting ultra-fast delivery from a luxury novelty to essential infrastructure. Pandemic lockdowns forced traditional retail giants like The Kroger Co and Target Corporation to accelerate their digital transformation and hyper-local delivery capabilities.
Competitive Benchmarking and Strategic Dynamics in the Instant Grocery Market
Market concentration is high in dense metropolitan zones, where specialized players compete fiercely with omnichannel goliaths. Firms like DoorDash Inc, Maplebear Inc (Instacart), and GoPuff utilize aggressive customer acquisition strategies and proprietary batching algorithms to defend their market share against Amazon.com Inc.
Executive Summary: High-Level Synthesis of Instant Grocery Market Findings
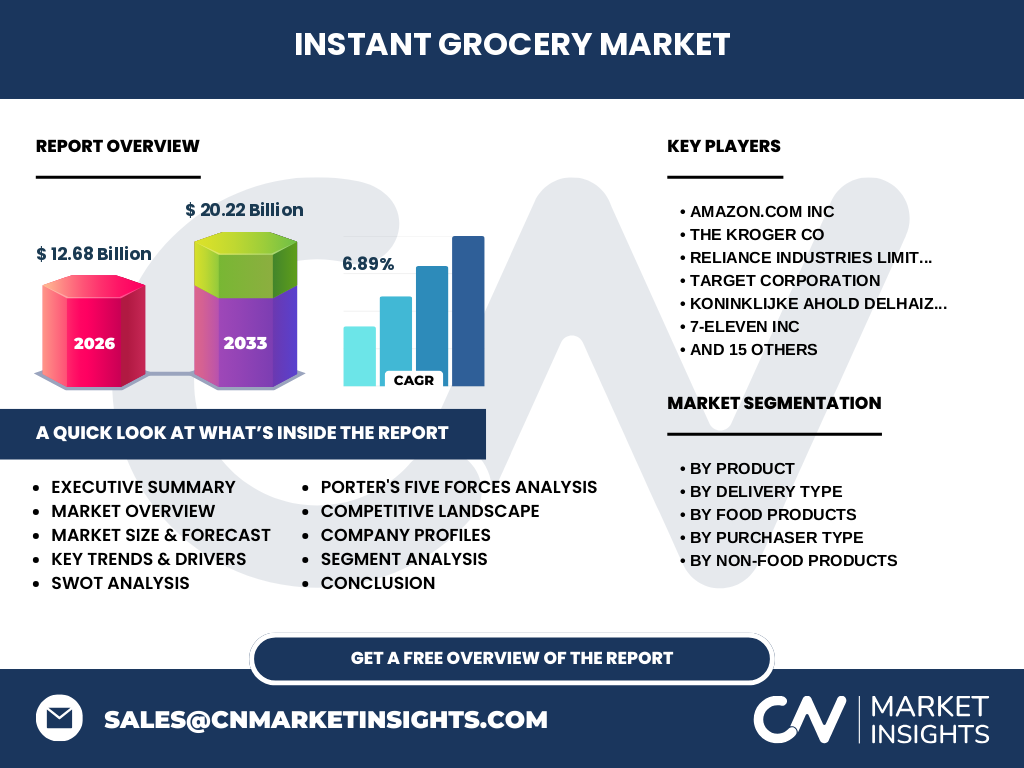
Our comprehensive Instant Grocery Market analysis projects robust expansion, moving from 12.68 Billion in 2026 toward 20.22 Billion by 2033. This trajectory reflects a solid 6.89% CAGR, underpinned by technological maturity in micro-fulfillment and shifting urban demographics favoring immediate gratification.
What is the long-term market forecast for the Instant Grocery Market from 2027 to 2033?
Projections indicate the industry will expand from 12.68 Billion in 2026 to reach 20.22 Billion by 2033, maintaining a steady 6.89% CAGR. This growth is sustained by maturing dark store economics and expansion into suburban fringe markets by operators like Yandex Lavka and Buymie Technologies Ltd.
Segmentation Analysis of the Instant Grocery Market
The ecosystem is categorized across multiple vectors: By Product (Food Products, Non-Food Products), By Delivery Type (Home Delivery, Click and Collect), By Food Products (Fresh Food, Packaged Food, Frozen Food, Beverages), By Purchaser Type (One Time, Subscriber), and By Non-Food Products (Household Products, Personal Care Items, Health & Wellness Products, Pet Care Products), each fulfilling distinct consumer missions.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly based on urban density, labor availability, and municipal zoning laws governing micro-fulfillment hubs. North America and Europe currently dominate transaction volumes, while emerging urban centers in Asia-Pacific show rapid adoption driven by high smartphone penetration and dense residential layouts.
In-Depth Regional Review of Key Instant Grocery Markets
Metropolitan hubs in North America and Western Europe exhibit the highest order frequencies, supported by sophisticated third-party logistics networks. Localized constraints, such as strict European labor regulations and North American parking ordinances for delivery couriers, continuously shape operational strategies for regional leaders like Koninklijke Ahold Delhaize NV.
Company Profiles and Strategic Positioning in the Instant Grocery Market
Industry participants deploy distinct operational models to capture value; for instance, Uber Technologies Inc and Postmates Inc leverage existing ride-share driver networks for flexible batch deliveries. Meanwhile, traditional grocers like Albertsons Companies Inc, Safeway Inc, Meijer Inc, and Wegmans Food Markets Inc integrate instant delivery with established physical supermarket footprints.
Porter's Five Forces Analysis of the Instant Grocery Industry
Competitive rivalry is intense due to low consumer switching costs and aggressive discounting among delivery apps. Supplier power remains moderate given the large base of CPG brands, whereas threat of substitution is high when consumers revert to planned weekly supermarket trips instead of instant ordering.
SWOT Analysis of the Instant Grocery Sector
Strengths include unmatched delivery speed and high customer engagement, while weaknesses involve persistent last-mile unit economics challenges. Opportunities lie in expanding high-margin private-label non-food offerings, countering threats from tightening labor laws and fuel cost volatility affecting fleets used by firms like Shipt Inc and Mercato Inc.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with agricultural producers and CPG manufacturers, flowing through regional distribution hubs into hyper-local dark stores managed by companies like 7-Eleven Inc and Giant Food LLC. Inventory is picked within minutes of order placement, utilizing advanced scanner tech before final dispatch to the consumer.
Strategic Investment Insights and High-Potential Areas
Investors should direct capital toward automated picking infrastructure and AI-driven demand forecasting software that reduces perishable food waste. High-potential areas include B2B dark grocery supply solutions and specialized software integration for traditional retailers seeking to match the speed of pure-play instant delivery apps.
Conclusion and Key Takeaways for Industry Stakeholders
The Instant Grocery Market is transitioning from a cash-burning growth phase to a disciplined, unit-economics-focused maturity. Achieving profitability requires strategic density in urban operations, sophisticated inventory management for fresh foods, and diversified product portfolios spanning both food and non-food essentials.
Research Methodology: Triangulating Instant Grocery Market Data
Our baseline estimates are rigorously triangulated by combining corporate registry disclosures, primary stakeholder interviews with logistics executives, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in our market sizing and revenue forecasts across all identified segments.
Scope of the Report and Coverage Parameters
This report covers global instant grocery delivery operations from 2026 through 2033, analyzing B2C transactions across specified product and delivery categories. Limitations include exclusion of traditional scheduled e-commerce grocery orders that exceed standard hyper-local delivery timeframes.
Recent Developments and Strategic Moves in the Instant Grocery Ecosystem
Recent industry activity features aggressive consolidation, strategic retail partnerships, and technological upgrades aimed at cutting delivery times below the fifteen-minute threshold. Major ecosystem players continually refine their dark store automation and expand non-food product categories to maximize average order value and operational efficiency.