What is the scope and industry significance of the Cryogenic Valve Assembly Market?
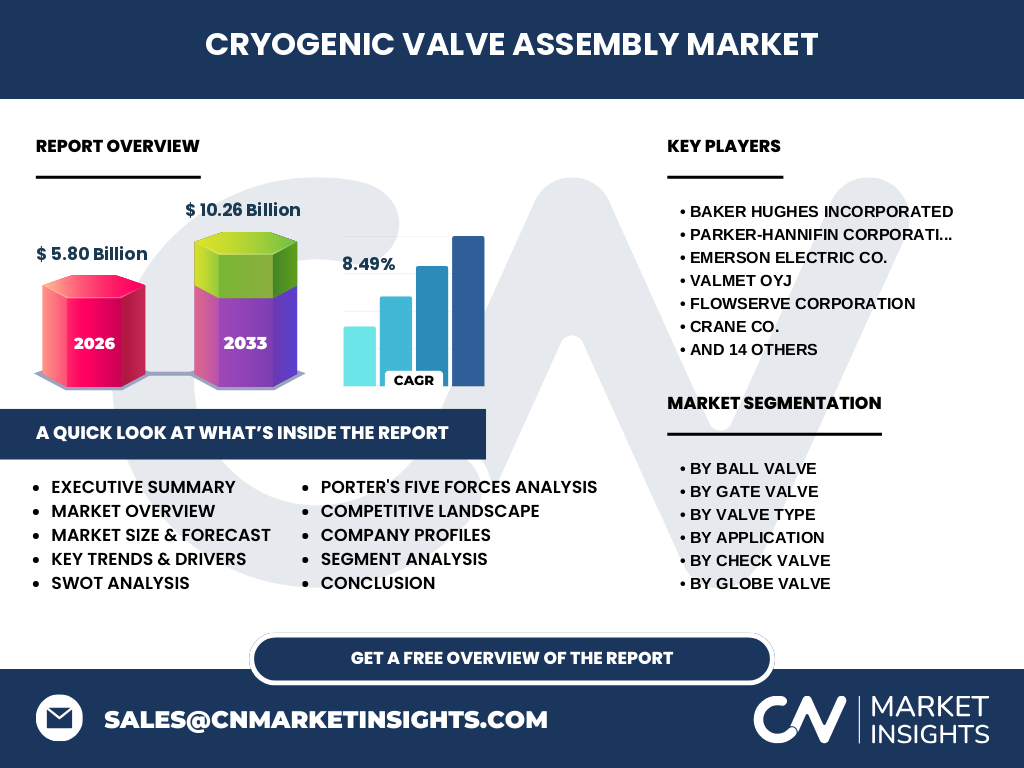
Our analysis indicates that the Cryogenic Valve Assembly Market valued at 5.80 Billion in 2026, plays a critical infrastructure role in managing liquefied gases below -150 degrees Celsius. Operating under strict ASME and ISO frameworks, these assemblies secure critical nodes across liquefied natural gas and industrial gas supply chains.
Key market drivers, restraints, challenges, and opportunities shaping Cryogenic Valve Assembly Market
Growth is propelled by surging clean energy investments, while severe material embrittlement at extreme low temperatures presents a primary engineering challenge. Market opportunities abound for suppliers utilizing specialized nickel alloys and stellite coatings to combat extreme thermal shock.
Emerging trends and growth patterns in Cryogenic Valve Assembly Market
The shift toward zero-emission logistics has accelerated demand for liquid hydrogen infrastructure. Industry innovators are integrating advanced polytetrafluoroethylene (PTFE) seals to eliminate fugitive emissions, aligning with tightening environmental mandates from the EPA and European regulators.
How did the COVID-19 pandemic affect the Cryogenic Valve Assembly Market and shape its recovery trajectory?
Pandemic-induced supply chain bottlenecks for raw materials like stainless steel initially slowed project execution. However, post-pandemic economic stimulus packages focused on green energy transitions fueled a robust rebound, driving accelerated adoption of automated ball and globe valve solutions.
Competitive landscape, major players, market concentration, and strategic dynamics
The landscape features high market concentration among established leaders like Emerson Electric Co., Flowserve Corporation, and Baker Hughes Incorporated. These tier-one players leverage global distribution networks and extensive intellectual property portfolios to outpace regional competitors.
Executive summary of key findings about Cryogenic Valve Assembly Market
The Cryogenic Valve Assembly Market is poised for exceptional expansion, driven by widespread industrial gas applications and clean energy initiatives. Strategic positioning in advanced metallurgy and localized manufacturing will dictate long-term market share dominance among leading global contenders.
What is the projected market forecast for the Cryogenic Valve Assembly Market from 2027 to 2033?
Based on our research, the market is projected to reach 10.26 Billion by 2033, expanding at a robust CAGR of 8.49%. This trajectory reflects accelerating global investments in Liquefied Natural Gas (LNG) terminals and aerospace propulsion systems.
Segmentation analysis of the Cryogenic Valve Assembly Market
The market breaks down by valve type into ball, butterfly, check, gate, and globe valves, with extensive use across cryogenic air separation units and storage systems. Construction utilizes specialized materials like graphite and PCTFE to handle media ranging from liquid oxygen to liquid argon.
Regional market analysis and geographic distribution performance
Geographic performance highlights strong momentum in regions with extensive marine export terminals and chemical processing hubs. North America and Asia-Pacific lead adoption due to massive infrastructure spending on energy transport and stringent industrial safety compliance standards.
In-depth regional review of key markets
Asia-Pacific dominates volume consumption driven by rapid industrialization in energy and power sectors, while North America prioritizes technological upgrades in existing hydrocarbon facilities. European markets focus heavily on compliance with stringent emissions directives set by regional authorities.
Company profiles and strategic positioning of leading market participants
Industry stalwarts like KITZ Corporation, Valmet Oyj, and Crane Co. focus on proprietary stem designs and fugitive emission certifications. Meanwhile, specialized players like Cryofab Inc. and Herose GmbH target niche cryogenic transport and storage segments.
Porter's Five Forces analysis of the industry
Bargaining power of buyers remains moderate due to the customized nature of extreme-temperature engineering. Threat of substitutes is remarkably low, given that standard valves fail under cryogenic stress, whereas rivalry among established multinational manufacturers is intense.
SWOT analysis of the Cryogenic Valve Assembly Market
Strengths lie in advanced proprietary sealing technologies and robust material science expertise. Weaknesses involve high capital expenditures for testing facilities. Opportunities stem from hydrogen fuel adoption, while threats include volatile raw material costs for nickel alloys.
Value chain analysis from raw materials to end-users
The value chain starts with the extraction of raw metals like stainless steel and specialty polymers, progressing through precision machining, cryogenic pressure testing, and final integration by end-users in electronics, chemicals, and energy sectors.
Investment insights and strategic recommendations
Investors should target manufacturers specializing in triple offset butterfly and trunnion mounted ball valves tailored for liquid hydrogen. High-potential areas include partnerships with emerging LNG bunkering facility operators across major international shipping corridors.
Conclusion and key takeaways for stakeholders
The Cryogenic Valve Assembly Market offers compelling growth prospects underpinned by the global energy transition. Success requires continuous R&D investment in material science and strict adherence to international cryogenic testing standards.
Research methodology used for baseline estimates and data triangulation
Baseline estimates are triangulated by cross-referencing trade registry data, primary stakeholder interviews with chief engineering officers, and secondary macroeconomic indicators from energy ministries and global trade associations to ensure high forecast accuracy.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue projections from 2026 to 2033, segmented by valve variants, construction materials, cryogenic mediums, and end-user verticals. Limitations include unforeseen geopolitical disruptions impacting international raw material logistics.
Recent developments, company announcements, and strategic moves
Recent industry momentum highlights strategic acquisitions and product launches aimed at enhancing fugitive emission capabilities. Companies like Bray International Inc. and Emerson Electric Co. have expanded their cryogenic test bench facilities to meet surging global demand.