Market overview — definition, scope, and industry significance of Brazing Materials Market
The Brazing Materials Market encompasses high-purity filler metals and alloys essential for creating permanent, leak-tight metallurgical bonds without melting the base metals. Valued at USD 2.75 Billion in 2026, the sector is foundational for advanced manufacturing, bridging critical thermal and electrical applications across aerospace, automotive, and electrical engineering domains.
Key market drivers, restraints, challenges, and opportunities shaping Brazing Materials Market
Growth is primarily propelled by lightweighting mandates in electric vehicle manufacturing and stringent ISO standards for joint integrity. However, supply chain volatility involving precious raw materials acts as a restraint. Market opportunities lie in developing eco-friendly, cadmium-free filler alloys to comply with environmental regulations like RoHS and REACH.
Emerging trends and growth patterns in Brazing Materials Market
A notable industry trend is the accelerated adoption of vacuum-furnace-compatible nickel alloys and automated paste dispensing systems. Technological miniaturization in electronics demands ultra-precise foil and powder preforms, favoring firms investing in proprietary atomization techniques to enhance joint reliability.
COVID-19 impact analysis — how the pandemic affected Brazing Materials Market and the recovery trajectory
The pandemic severely disrupted supply chains for critical metals like silver and copper, temporarily stalling heavy industrial and automotive output. Recovery has been swift, driven by pent-up demand in electronics and robust government infrastructure investments that revitalized commercial construction and aerospace supply channels.
Competitive landscape — major players, market concentration, and strategic dynamics
The market features a mix of multinational conglomerates and specialized alloy specialists. Industry leaders like Lincoln Electric Holdings Inc. and Materion Corporation leverage aggressive R&D and strategic acquisitions, while regional players such as Safina a.s. compete through customized, high-purity alloy formulations.
Executive summary — high-level synthesis of key findings about Brazing Materials Market
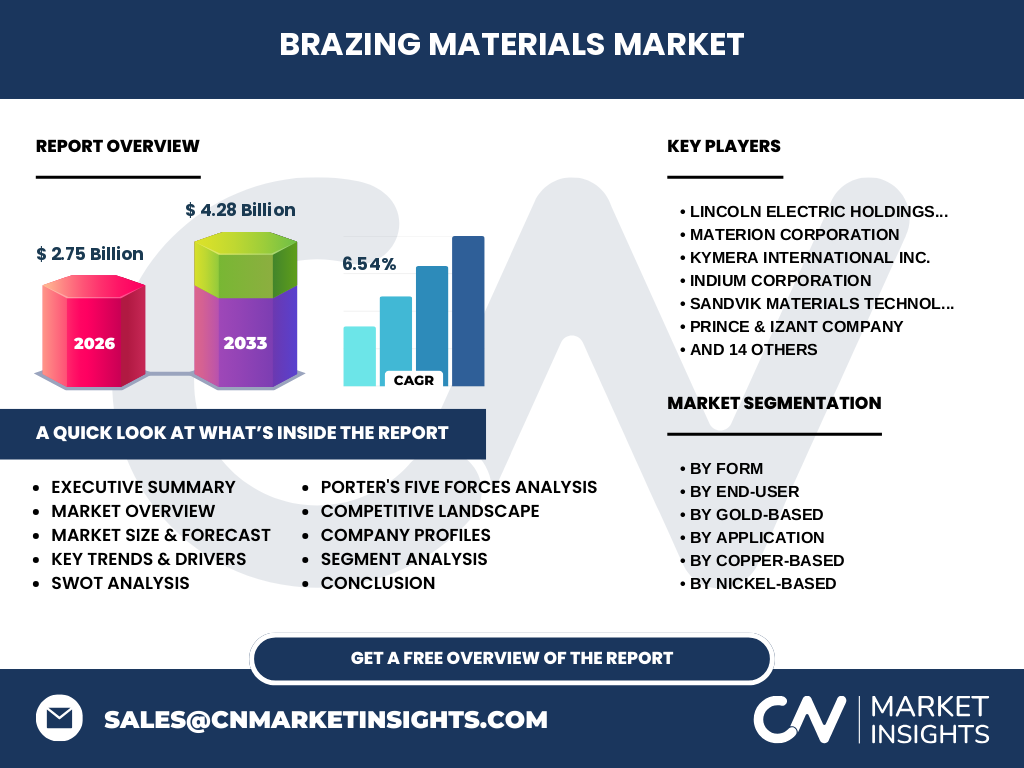
Our comprehensive analysis of the Brazing Materials Market projects expansion from USD 2.75 Billion in 2026 to USD 4.28 Billion by 2033, registering a solid 6.54% CAGR. Electrification and aerospace revival serve as the twin pillars sustaining this long-term upward trajectory.
Market forecast — projected growth from 2027 to 2033
The market is poised for robust expansion, scaling from its 2026 baseline to reach USD 4.28 Billion by 2033 at a 6.54% CAGR. This trajectory reflects increasing deployment in high-performance heat exchangers, EV battery cooling plates, and next-generation renewable energy infrastructure.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Market segmentation spans product types (Silver-Based, Copper-Based, Aluminum-Based, Gold-Based, Nickel-Based), forms (Powder, Paste, Foil, Rod or Wire), applications (Automotive, Aerospace, Electrical, Construction), and end-users (Industrial, Residential, Commercial). Product versatility dictates that silver and copper alloys dominate industrial volume, while gold and nickel alloys capture high-margin aerospace niches.
Regional market analysis — geographic distribution and performance across regions
Geographic performance mirrors regional industrial output, with Asia-Pacific leading in volume due to dense electronics and automotive manufacturing hubs. North America and Europe follow closely, prioritizing high-value aerospace applications and strict adherence to environmental compliance standards.
In-depth regional review — detailed examination of key regional markets
Asia-Pacific remains the primary growth engine, fueled by massive electronics manufacturing in East Asia and automotive production across emerging economies. Meanwhile, North America exhibits steady demand driven by strict defense and aerospace specifications that mandate premium nickel and gold-based brazing solutions.
Company profiles — strategic positioning of leading companies in Brazing Materials Market
Industry participants deploy distinct competitive plays. Sandvik Materials Technology AB and Wall Colmonoy Corporation focus on high-temperature, corrosion-resistant nickel alloys for extreme environments. Conversely, firms like Indium Corporation and Prince & Izant Company excel in specialized micro-joining preforms for electronics.
Porter's Five Forces analysis — competitive forces assessment
Industry rivalry is intense among established alloy manufacturers, yet mitigated by high switching costs in certified aerospace and automotive applications. Supplier power remains moderate to high due to commodity price fluctuations for silver and copper, whereas the threat of substitutes is low given the unmatched mechanical strength of brazed joints.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Strengths include superior joint integrity and broad material compatibility. Weaknesses involve exposure to raw material price volatility. Opportunities center on EV thermal management systems, while threats comprise stringent environmental regulations restricting traditional cadmium-bearing formulations.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain initiates with mining and refining base metals like copper, nickel, and precious metals. Intermediate refiners convert these into powders, pastes, and wires. Distributors and specialized formulators like Fusion Inc. or Aimtek Inc. then supply OEMs in automotive and aerospace sectors.
Investment insights — strategic recommendations and high-potential areas
Investors should target manufacturers specializing in flux-coated aluminum and vacuum-grade nickel alloys, which directly support EV lightweighting and clean energy infrastructure. Strategic partnerships with primary metal refineries offer a hedge against commodity price swings.
Conclusion and key takeaways
The Brazing Materials Market demonstrates robust fundamentals, projected to achieve USD 4.28 Billion by 2033. Success in this landscape hinges on continuous material innovation, environmental compliance, and deep technical integration with high-growth end-user sectors like electric mobility and aerospace.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by synthesizing customs trade registry data, primary qualitative interviews with C-suite executives across named industry participants, and secondary macroeconomic indicators tracking industrial manufacturing indices and metal commodity pricing trends.
Scope of the report — coverage parameters and limitations
This report covers global revenue and volume projections from 2026 to 2033, segmented comprehensively by product, form, application, and end-user. Limitations include unforeseen geopolitical trade disruptions and sudden raw material supply shocks that may cause short-term market deviations.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent strategic moves emphasize eco-friendly transitions. Companies such as Kymera International Inc. and Tokyo Braze Co. Ltd. have introduced advanced cadmium-free alloy pastes and automated delivery systems designed to enhance manufacturing efficiency and meet stringent global environmental directives.