What is the market overview and industry significance of the Eco-Friendly Fashion Brands Market?
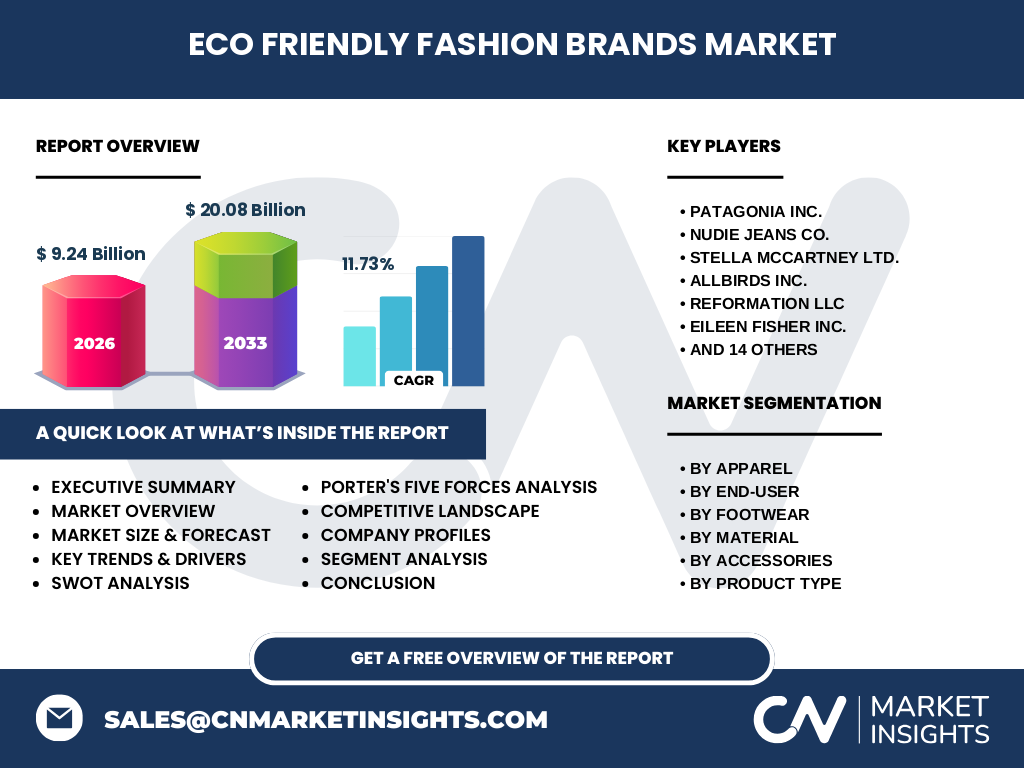
Our analysis indicates that the Eco-Friendly Fashion Brands Market represents a fundamental restructuring of global apparel commerce, valued at $9.24 Billion in 2026. This sector encompasses sustainable sourcing, ethical labor, and circular manufacturing frameworks, moving well beyond niche appeal into a core economic driver governed by strict European Union PEF standards and global ESG mandates.
What are the key market drivers, restraints, challenges, and opportunities shaping the Eco-Friendly Fashion Brands Market?
The Eco-Friendly Fashion Brands Market industry trends are propelled by rising consumer demand for transparency and tightening textile regulations like the EU Strategy for Sustainable Textiles. However, supply chain bottlenecks for certified organic cotton and hemp, alongside high processing costs, act as major restraints. Opportunities abound in biodegradable footwear innovations and closed-loop garment recycling loops.
Emerging trends and growth patterns in the Eco-Friendly Fashion Brands Market
Market trajectories show an accelerating shift toward regenerative agriculture and traceable supply chains utilizing blockchain ledger technology. Brands are increasingly replacing synthetic materials with advanced botanical alternatives like bamboo and recycled fabric. This evolution heavily favors innovators capable of scaling sustainable activewear and loungewear without sacrificing technical performance.
How did COVID-19 impact the Eco-Friendly Fashion Brands Market and what does the recovery trajectory look like?
The pandemic severely disrupted inventory flows through major logistics hubs like the Port of Los Angeles and Port of Shanghai, exposing vulnerabilities in fast-fashion supply chains. Conversely, COVID-19 acted as a catalyst for conscious consumerism, accelerating the post-pandemic recovery of the Eco-Friendly Fashion Brands Market as shoppers prioritized durability, ethical labor, and local sourcing.
Competitive landscape: major players, market concentration, and strategic dynamics
The competitive ecosystem features pioneers like Patagonia Inc. and Stella McCartney Ltd. alongside digital-native disruptors such as Allbirds Inc. and Reformation LLC. Market concentration is moderate but tightening as legacy conglomerates acquire sustainable startups to capture eco-conscious consumer segments and navigate impending carbon-offset regulations.
Executive summary of key findings in the Eco-Friendly Fashion Brands Market
Our comprehensive research confirms that the Eco-Friendly Fashion Brands Market is entering a hyper-growth phase, projected to reach $20.08 Billion by 2033 at an impressive 11.73% CAGR from 2027. Success requires vertically integrated supply chains, absolute raw material transparency, and multi-channel distribution strategies spanning online stores and high-end specialty boutiques.
Market forecast and projected growth trajectory from 2027 to 2033
Driven by compounding consumer awareness and regulatory pressures, the market will expand rapidly from its 2026 baseline of $9.24 Billion to achieve $20.08 Billion by 2033. This sustained 11.73% CAGR reflects robust consumer adoption across diverse product categories, particularly in sustainable footwear and organic apparel lines.
Segmentation analysis of the Eco-Friendly Fashion Brands Market
The market breaks down across several critical vectors: By Product Type (Apparel, Footwear, Accessories, Other Product Types including activewear and swimwear); By Material (Organic Cotton, Recycled Fabric, Hemp, Bamboo); By End-User (Men, Women, Kids); and By Distribution Channel (Online Stores, Specialty Stores, Supermarkets).
Regional market analysis and geographic distribution performance
Geographic performance highlights Western Europe as the dominant revenue contributor, bolstered by strict European Commission eco-design directives. North America follows closely, driven by urban consumer demand in coastal metropolitan hubs. Meanwhile, Asia-Pacific emerges as the fastest-growing manufacturing and consumer frontier for sustainable textiles.
In-depth regional review of key markets within the global landscape
In Europe, markets like Germany and the UK lead in regulatory compliance and consumer adoption of circular fashion models. The North American market relies heavily on direct-to-consumer digital channels championed by brands like Pact LLC and Amour Vert Inc., whereas Asia-Pacific regional growth is anchored by expanding domestic middle classes in urban centers.
Strategic positioning and company profiles in the Eco-Friendly Fashion Brands Market
Industry leaders employ distinct positioning: VEJA S.A. dominates sustainable footwear through ethical sourcing of wild rubber and organic cotton, while Eileen Fisher Inc. pioneers circular take-back systems. Companies like Nudie Jeans Co. leverage lifetime repair guarantees, cementing brand loyalty through tangible environmental stewardship.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers is moderate-to-high due to limited global yields of certified organic fibers. Threat of new entrants remains elevated due to low digital storefront barriers, though customer switching costs and brand trust favor established eco-pioneers like prAna LLC and Finisterre Ltd.
SWOT analysis of the Eco-Friendly Fashion Brands Market
Strengths include high brand affinity and alignment with global climate goals. Weaknesses involve higher price points and complex supply chain auditing. Opportunities lie in scaling recycled fabric innovations, while threats include greenwashing scrutiny and raw material price volatility driven by climate change.
Value chain analysis from raw materials to end-users
The value chain initiates with sustainable agricultural harvesting of organic cotton, hemp, and bamboo, progressing through eco-friendly dyeing mills powered by renewable energy. It culminates in ethical cut-and-sew facilities managed by brands like Kowtow Ltd. and People Tree Ltd. before reaching consumers via specialized online and physical retail channels.
Investment insights and high-potential growth areas
Investors should target early-stage innovators in agricultural biotechnology, alternative leather materials, and automated clothing recycling infrastructure. Brands utilizing circular business models—such as rental, resale, and repair services championed by firms like Outerknown Inc.—offer superior long-term risk-adjusted returns.
Conclusion and key takeaways for industry stakeholders
The Eco-Friendly Fashion Brands Market is no longer a peripheral segment but a defining pillar of modern apparel economics. Achieving success through 2033 requires unwavering supply chain transparency, rigorous third-party certifications, and deep integration of circular economy principles across all product categories.
Research methodology for baseline estimates and data triangulation
Our proprietary research methodology triangulates data by synthesizing primary stakeholder interviews with sustainable fashion executives, exhaustive secondary analysis of global trade registries, and macroeconomic indicators tracking disposable income shifts and environmental regulatory enforcement across key jurisdictions.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics for the Eco-Friendly Fashion Brands Market from 2026 to 2033, analyzing apparel, footwear, accessories, and specialized product lines. Limitations include potential lag in unofficial artisan supply chain data and unlegislated regional definitions of 'eco-friendly' claims.
Recent developments, corporate announcements, and strategic partnerships
Recent market dynamism is highlighted by strategic collaborations, such as Girlfriend Collective Inc. expanding its closed-loop recycling infrastructure and tentree Inc. scaling its tree-planting impact initiatives. Such maneuvers illustrate how major participants are actively hardening their competitive moats against impending regulatory audits.