Market Overview: Defining the Drillships Market
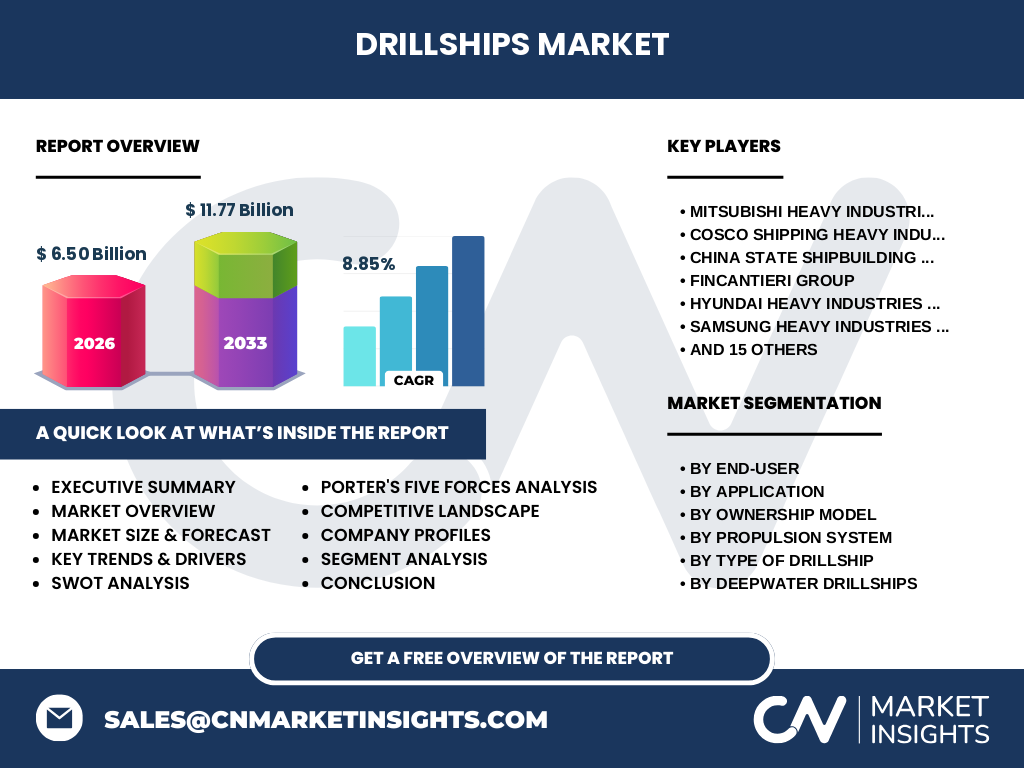
Our analysis indicates that the Drillships Market valued at 6.50 Billion in 2026, represents the pinnacle of offshore hydrocarbon exploration technology. These self-propelled floating vessels operate in deepwater and ultra-deepwater frontiers, navigating complex logistical hurdles governed by strict regulatory bodies like the BSEE and IMO while utilizing specialized raw materials such as high-grade marine steel and advanced titanium drill risers.
Structural Growth Drivers, Restraints, and Opportunities
The Drillships Market industry trends highlight robust demand driven by rising global energy consumption and deepwater discoveries. However, high capital expenditure and stringent environmental compliance imposed by bodies like the EPA act as restraints. Significant opportunities lie in transitioning to low-emission technologies, favoring shipbuilders integrating advanced Dynamic Positioning systems.
Emerging Technological Patterns in the Drillships Market
The shift toward Dual Fuel And Low Emission Propulsion Systems is transforming the Drillships Market market size landscape. Operators are deploying High-Pressure High-Temperature modules and automated riser handling to boost operational efficiency off the coasts of Brazil and West Africa, minimizing carbon footprints in harsh operating environments.
How COVID-19 Disrupted and Reshaped Offshore Operations
The pandemic severely suppressed offshore activity, causing fleet utilization drops and shipyard delays across major hubs in South Korea and Singapore. Our research shows the post-pandemic recovery trajectory accelerated consolidation, as resilient players like Valaris Limited optimized operations and leveraged rising commodity prices.
Competitive Benchmarking and Strategic Dynamics
Market concentration in the Drillships Market is heavily influenced by elite Asian shipbuilders such as Samsung Heavy Industries Co. Ltd., Hyundai Heavy Industries Co. Ltd., and Hanwha Ocean Co. Ltd. These giants compete on hull design efficiency, proprietary DP3 station-keeping technology, and the ability to deliver complex ultra-deepwater assets on schedule.
Executive Summary of the Drillships Market
Our exhaustive Drillships Market analysis reveals a high-growth sector expanding from 6.50 Billion in 2026 to 11.77 Billion by 2033 at a CAGR of 8.85%. This expansion is powered by technological upgrades in deepwater drilling units and heightened E&P spending by major oil and gas corporations globally.
Market Forecast and Long-Term Projections (2027-2033)
The data suggests the Drillships Market will scale dramatically, surging from its 2026 baseline to 11.77 Billion by 2033, achieving an impressive 8.85% CAGR. This trajectory is underpinned by long-term offshore field development contracts in the Golden Triangle and prolific acreage in the Guyana-Suriname basin.
Comprehensive Segmentation Analysis
The Drillships Market breaks down across distinct operational categories:
- End-User: Oil And Gas Companies, Offshore Drilling Contractors, Offshore Research And Scientific Drilling Operators
- Application: Shallow Water, Deep Water, Ultra-deepwater
- Ownership Model: Owned Fleet, Chartered Fleet, Joint Ventures
- Propulsion System: Conventional, Dynamic Positioning, Hybrid, Dual Fuel
- Type: Ultra-Deepwater, Deepwater, Intermediate, Shallow
Geographic Distribution and Regional Performance
Regional performance in the Drillships Market industry trends is heavily concentrated in Latin America, West Africa, and the US Gulf of Mexico. Ultra-deepwater basins in these zones require specialized harsh environment and high-capacity drilling vessels, driving localized shipyard mobilization and specialized supply chain networks.
In-Depth Regional Review of High-Yield Basins
Latin America dominates demand through pre-salt discoveries in the Santos and Campos basins, requiring advanced vessels from builders like Estaleiro Atlantico Sul S.A. Simultaneously, the Asia-Pacific region acts as the primary manufacturing epicenter, anchored by shipyards in China and South Korea producing cutting-edge offshore assets.
Strategic Positioning of Leading Company Profiles
Key industry participants such as China State Shipbuilding Corporation Limited, Cosco Shipping Heavy Industry Co. Ltd., and Keppel Offshore And Marine Limited leverage massive dry-dock infrastructure and state-of-the-art engineering capabilities. Their strategic positioning focuses on modular construction techniques and eco-friendly propulsion retrofits to meet tightening maritime decarbonization mandates.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers in the Drillships Market remains moderate-to-high due to surplus charter capacity during downturns, while supplier power is constrained by specialized marine equipment availability. The threat of new entrants is remarkably low given extreme capital expenditure hurdles and intellectual property barriers in dynamic positioning architecture.
SWOT Analysis of the Global Drillships Sector
Strengths include unmatched operational reach in ultra-deepwater; Weaknesses involve high sensitivity to crude price volatility; Opportunities emerge from carbon capture integration and digital automation; Threats stem from geopolitical trade frictions impacting raw steel and specialized alloy supply chains across global shipyards.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw metallurgies like structural steel and nickel alloys, flowing through specialized equipment manufacturers for top drives and blowout preventers. Shipyards like Dalian Shipbuilding Industry Co. Ltd. and Yantai CIMC Raffles Offshore Ltd. assemble these components before delivery to offshore contractors for deployment.
High-Potential Investment Insights and Strategic Recommendations
Investors should target shipyard assets and contractors specializing in Dual Fuel And Low Emission Propulsion Systems. Our research indicates that early adopters of hybrid power generation and automated riser systems will secure premium day rates as operators prioritize Scope 1 emissions reductions in offshore portfolios.
Conclusion and Definitive Industry Takeaways
The Drillships Market is transitioning into a technology-driven growth phase, underpinned by a solid 8.85% CAGR reaching 11.77 Billion by 2033. Stakeholders must align with sustainability mandates and deploy advanced digital automation to capture high-margin deepwater and ultra-deepwater operational contracts.
Rigorous Research Methodology and Triangulation
Our baseline estimates for the Drillships Market market size are constructed by triangulating primary stakeholder interviews with C-level offshore executives, secondary macroeconomic indicators, national registry data from maritime authorities, and proprietary econometric modeling of global rig utilization rates.
Scope of the Report and Analytical Parameters
This report encompasses a comprehensive evaluation of the Drillships Market across five primary segmentation vectors, regional sub-markets from 2026 to 2033, and macro-economic constraints. Limitations include unforeseen geopolitical shocks and sudden regulatory shifts in deepwater leasing permissions across major sovereign waters.
Recent Strategic Developments, Partnerships, and Product Launches
Recent milestones in the Drillships Market feature strategic joint ventures, yard consolidations, and green vessel rollouts by industry leaders like Seatrium Ltd. and Lamprell plc. These moves emphasize modular design configurations and smart digital twin integrations designed to minimize non-productive time offshore.