What is the scope and industry significance of the Licensed Toy Market?
Our analysis indicates the Licensed Toy Market encompasses branded merchandise spanning Action Figures, Dolls And Plush Toys, and Construction Sets. The market size reaches 31.41 Billion in 2026, driven by intellectual property partnerships requiring stringent compliance with safety bodies like the Consumer Product Safety Commission (CPSC).
Key market drivers, restraints, challenges, and opportunities shaping Licensed Toy Market
Growth is propelled by blockbuster cinematic releases and digital streaming franchises, while strict raw material volatility for plastics and electronic components poses supply chain restraints. Strategic opportunities lie in sustainable bio-plastics and omnichannel retail integration across Hypermarkets, Supermarkets, and Online channels.
Emerging trends and growth patterns in Licensed Toy Market
The industry is experiencing a massive pivot toward adult collector demographics (Kidults) driving sales in Collectible Figures and Board Games. Digital convergence via augmented reality features embedded in STEM Kits and Action Figures is redefining consumer engagement.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe port congestion and raw material scarcity, yet accelerated digital commerce for companies like Hasbro Inc. and Mattel Inc. Post-recovery, the market rebounded strongly, stabilizing supply chains through nearshoring and diversified manufacturing hubs across Southeast Asia.
Competitive landscape and strategic dynamics
Market concentration remains moderate to high, dominated by major players like the LEGO Group, Spin Master Corp., and Bandai Co. Ltd. Strategic dynamics focus on securing exclusive entertainment licenses from major studios to capture high-margin pre-school and collector segments.
Executive summary of the Licensed Toy Market
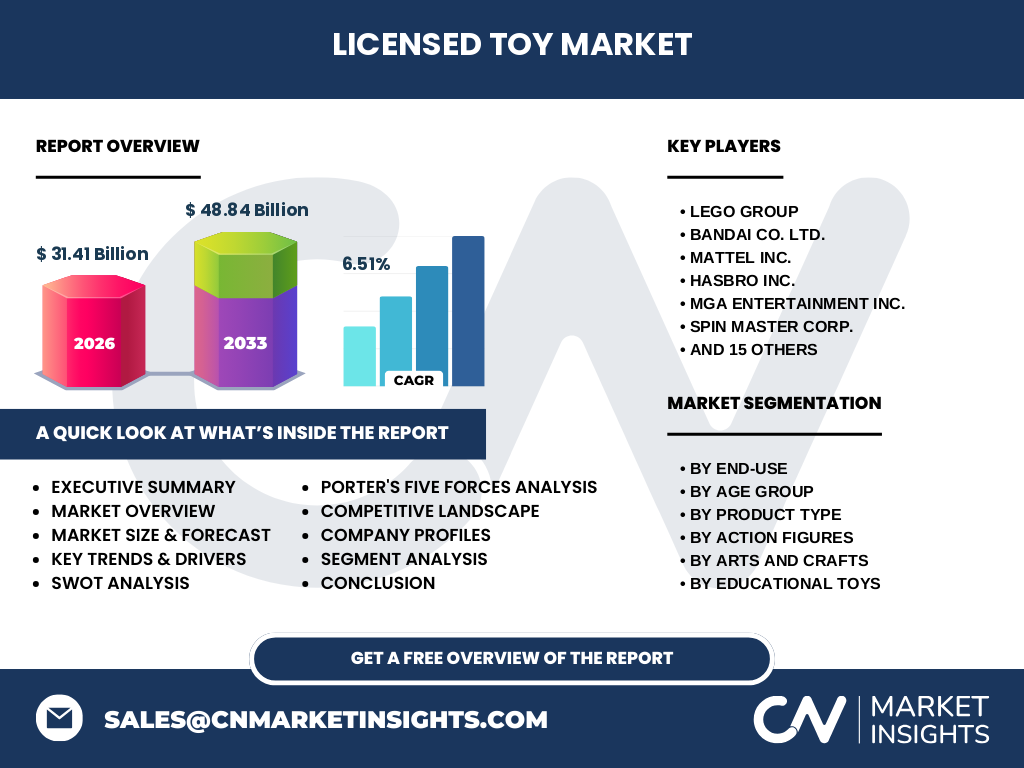
Valued at 31.41 Billion in 2026, the sector is projected to surge to 48.84 Billion by 2033 at a CAGR of 6.51%. Proprietary insights reveal that intellectual property integration and direct-to-consumer digital platforms remain primary value creators.
Market forecast from 2027 to 2033
Driven by robust demand for character-based merchandise, the sector is forecast to expand from 31.41 Billion in 2026 to 48.84 Billion by 2033. This reflects a steady 6.51% CAGR, fueled by global expansion in emerging Asian economies.
Segmentation analysis across product types and demographics
Segmentation spans End-Use (Individual, Commercial), Age Groups (Below 1 to 12+), and Product Types (Action Figures, Arts And Crafts, Construction Sets, Games And Puzzles). Educational Toys and STEM Kits are capturing increased market share due to parental demand for developmental play.
Regional market analysis and geographic distribution
North America dominates consumption due to high media saturation and powerful retail networks. Meanwhile, Asia-Pacific exhibits the fastest regional growth, supported by expanding middle-class disposable incomes and domestic manufacturing strengths in countries like China and Japan.
In-depth regional review of key markets
North America leverages mature online distribution and hypermarket penetration. Europe enforces rigorous chemical safety standards via EN 71 directives, directly impacting material selection for plush and molded plastic toys produced by regional heavyweights like Schleich GmbH.
Company profiles and strategic positioning
Industry leaders like Funko Inc. dominate collectible niches, whereas the LEGO Group commands the Construction Sets category through modular brick innovation. Mattel Inc. and Hasbro Inc. leverage multi-brand cinematic universes to sustain long-term retail placement.
Porter's Five Forces analysis
Supplier power is moderate due to standardized raw material availability, while buyer power is high given vast retail alternatives. Threat of substitution remains subdued due to strong emotional attachment to licensed entertainment brands.
SWOT analysis of the sector
Strengths include powerful IP portfolios and global distribution networks. Weaknesses involve high licensing royalty costs. Opportunities reside in sustainable materials, while threats stem from counterfeit merchandise and shifting youth media consumption habits.
Value chain analysis from raw materials to end-users
The value chain originates with raw resin and textile sourcing, moving through mold injection, IP licensing agreements, and global logistics via major ports. Final distribution occurs through Specialized Stores, Departmental Stores, and digital platforms.
Investment insights and high-potential areas
Investors should target direct-to-consumer digital platforms and eco-friendly manufacturing startups. Companies focusing on adult collector subsets (Kidults) and interactive educational technology offer superior margin expansion potential.
Conclusion and key takeaways
The Licensed Toy Market presents robust expansion opportunities, scaling from 31.41 Billion to 48.84 Billion at a 6.51% CAGR. Success hinges on agile IP acquisition, digital integration, and sustainable supply chain practices.
Research methodology and data triangulation
Our baseline estimates are triangulated using trade registry data, primary executive interviews with stakeholders from MGA Entertainment Inc. and Moose Toys Pty Ltd., and secondary macroeconomic indicators parsed through proprietary regression models.
Scope of the report and coverage parameters
This report covers global revenue performance across all major product categories, distribution channels, and regional blocks from 2026 through 2033. Limitations exclude unverified grey-market retail channels and unlicensed counterfeit goods.
Recent developments and strategic moves
Recent industry momentum features major partnerships between toy conglomerates and streaming giants. Companies like Spin Master Corp. and Jakks Pacific Inc. have aggressively launched eco-friendly product lines and expanded omnichannel retail agreements.