Market overview of the Pipette Market
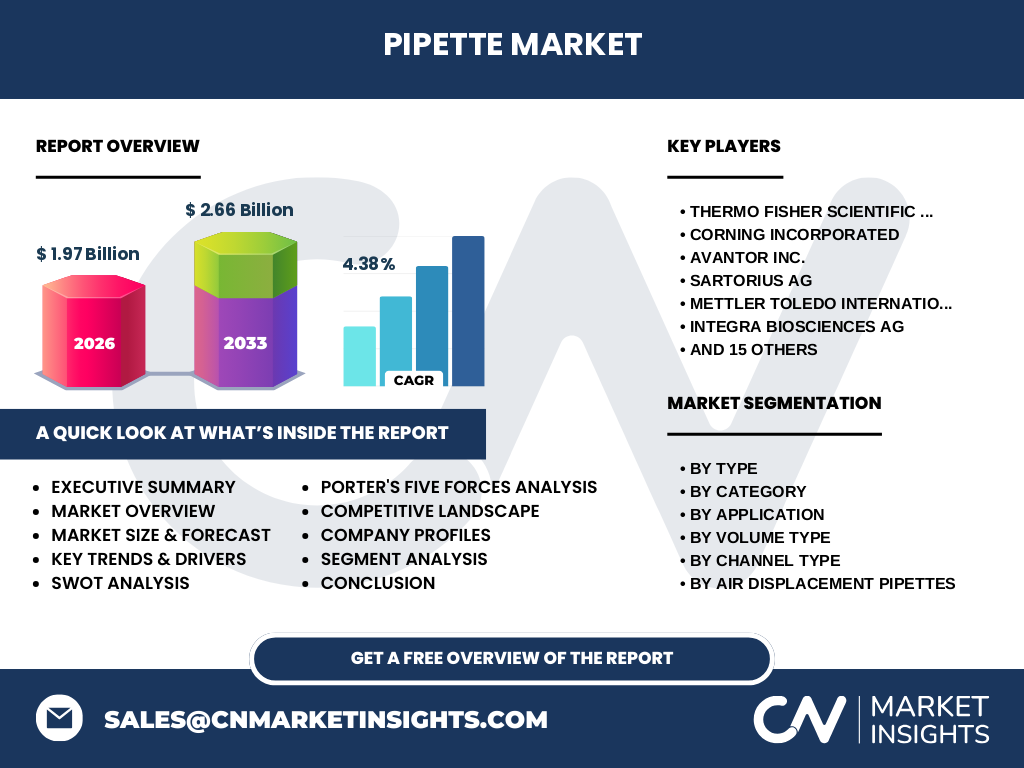
Our analysis indicates that the Pipette Market valued at 1.97 Billion in 2026 is foundational to life sciences. Encompassing air displacement and positive displacement tools, this sector drives precision liquid handling across pharmaceutical and biotech laboratories globally.
Structural Growth Drivers and Restraints
Growth is anchored by rising biopharmaceutical R&D investments and automation adoption. However, supply chain bottlenecks for medical-grade polymers and strict FDA and ISO regulatory compliance hurdles act as key restraints for emerging manufacturers in the Pipette Market.
Emerging Trends in Liquid Handling
The shift toward electronic pipettes and multi-channel configurations is accelerating. Laboratories increasingly demand ergonomic designs and Bluetooth connectivity to minimize repetitive strain injuries and ensure precise traceability during high-throughput screening assays.
COVID-19 Impact and Post-Pandemic Recovery
The pandemic caused an unprecedented surge in demand for diagnostic testing tools, heavily straining manufacturing lines. The current recovery trajectory focuses on supply chain diversification and localized inventory buffering to mitigate future geopolitical and logistical disruptions.
Competitive Benchmarking and Industry Concentration
The Pipette Market features high concentration, led by giants like Thermo Fisher Scientific Inc., Eppendorf AG, and Sartorius AG. These players dominate through proprietary tip compatibility ecosystems and extensive global distribution networks across major biotech hubs.
Executive Summary of the Pipette Market
Our research forecasts the Pipette Market to reach 2.66 Billion by 2033, expanding at a CAGR of 4.38% from 2027. Strategic consolidation and digital integration of manual operations remain the primary value creators for stakeholders.
Market Forecast from 2027 to 2033
Driven by robust monoclonal antibody pipelines and forensic DNA profiling, the market is set for steady expansion. Our data suggests compound annual growth of 4.38% will lift valuations from 1.97 Billion in 2026 to 2.66 Billion by 2033.
Segmentation Analysis by Type and Application
The market splits across air and positive displacement types, electronic and manual categories, and single versus multi-channel formats. Pharmaceutical laboratories and biotech laboratories represent the highest-value application segments demanding certified volumetric accuracy.
Regional Market Analysis and Geographic Distribution
North America dominates revenue generation due to concentrated biopharma clusters and NIH funding. Meanwhile, Asia-Pacific emerges as the fastest-growing region, fueled by expanding contract research organizations (CROs) in China and India requiring reliable liquid handling tools.
In-Depth Regional Review
Regional performance hinges on local regulatory stringency and research funding. European markets favor sustainability-focused, autoclavable designs, while North American facilities prioritize high-throughput electronic systems to optimize labor costs and reduce pipetting errors.
Strategic Positioning of Leading Companies
Industry leaders like Corning Incorporated, Mettler Toledo, and Gilson Inc. differentiate via precision calibration services and modular product lines. Emerging players such as Accumax Lab Devices compete aggressively on cost-effective manual alternatives.
Porter's Five Forces Analysis
Supplier power remains moderate due to specialized resin availability, while buyer power is high among large pharma procurement teams. Threat of substitutes is low because certified liquid handling accuracy is irreplaceable in regulated assays.
SWOT Analysis of the Industry
Strengths include high switching costs and patented ergonomic technologies. Weaknesses involve calibration maintenance overheads. Opportunities lie in emerging genomics markets, while threats stem from low-cost counterfeit pipette tips damaging equipment integrity.
Value Chain Analysis
The value chain flows from petrochemical resin suppliers and precision mold makers to instrument manufacturers, distributors, and end-users. Value is captured primarily at the manufacturing and proprietary tip-matching stages rather than raw material extraction.
Investment Insights and High-Potential Areas
High-potential investment opportunities center on IoT-enabled smart pipettes and eco-friendly, biodegradable tip manufacturing. Venture capital flows toward startups reducing ergonomic fatigue and integrating seamlessly with automated liquid handling workstations.
Conclusion and Key Strategic Takeaways
The Pipette Market offers reliable growth underpinned by essential life science applications. Success requires balancing digital innovation, stringent ISO compliance, and robust distribution partnerships across expanding emerging economies.
Research Methodology
Our baseline estimates are triangulated using a rigorous mix of trade registry data, primary stakeholder interviews with laboratory directors, and secondary macroeconomic indicators from global health organizations to ensure maximum market accuracy.
Scope of the Report and Limitations
This report covers global revenue estimations, volumetric shipment data, and strategic profiles across the specified segments from 2026 to 2033. Limitations include unforeseen geopolitical trade restrictions and sudden regulatory policy shifts across regional jurisdictions.
Recent Developments and Strategic Moves
Recent industry moves feature strategic acquisitions and new product launches emphasizing wireless calibration tracking. Companies like Integra Biosciences and Sartorius AG continue expanding automated pipetting partnerships to capture high-throughput genomic testing demand.