What is the scope and industry significance of the Online Education Market?
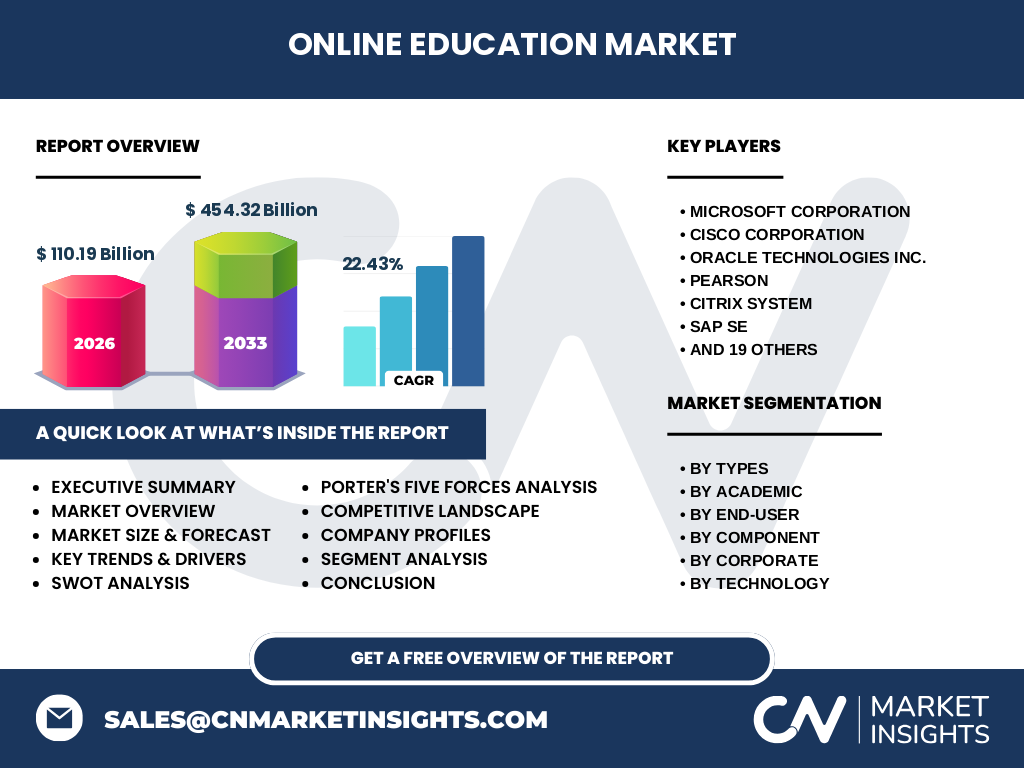
Our analysis indicates that the Online Education Market represents a transformative shift in global learning, valued at 110.19 Billion in 2026. This sector encompasses digital academic curricula, corporate upskilling platforms, and advanced learning management technologies regulated by national education bodies.
What are the primary drivers and restraints shaping the Online Education Market industry trends?
Growth is propelled by widespread mobile e-learning adoption and corporate compliance demands, though constrained by localized digital infrastructure deficits. Industry leaders like Coursera and Udemy Training Technologies Inc. capitalize on these shifts by bridging enterprise skill gaps globally.
What are the emerging trends and growth patterns in the Online Education Market analysis?
The sector exhibits a rapid pivot toward application simulation tools and bite-sized podcasts, disrupting traditional pedagogical models. Duolingo Inc. and MasterClass exemplify this trend, leveraging gamification and high-production-value content to capture shifting consumer attention spans.
How did COVID-19 impact the Online Education Market and accelerate recovery?
The pandemic acted as an unprecedented catalyst, forcing academic institutions and SMBs to adopt virtual classrooms overnight. Our research shows this emergency pivot permanently altered baseline demand, cementing digital delivery as a permanent pillar of modern education alongside legacy infrastructure.
Competitive Benchmarking and Market Concentration in the Online Education Market
The landscape features intense rivalry among tech giants like Microsoft Corporation and specialized platforms such as Byju's and Unacademy. Market concentration is moderate, with enterprise players competing against agile edtech startups through aggressive strategic acquisitions and ecosystem integration.
Executive summary of key findings for the Online Education Market report
Driven by robust demand across academic and corporate segments, the Online Education Market is poised for explosive expansion. Strategic investments in learning management systems will yield high returns as institutions modernize infrastructure to meet evolving regulatory and workforce requirements.
What is the long-term market forecast for the Online Education Market from 2027 to 2033?
Our forecasting models project the market to surge from 2027 through 2033, reaching an impressive 454.32 Billion by the end of the forecast period. This trajectory reflects a formidable CAGR of 22.43%, driven by persistent enterprise digital transformation and lifelong learning mandates.
Segmentation analysis of the Online Education Market by types, components, and end-users
The market segments into Academic and Corporate streams, utilizing hardware components like laptops, mobiles, and personal computers. End-users span K-12, Massive Open Online Courses, SMBs, and Large Enterprises, each requiring tailored deployment strategies from platform providers like Blackboard Solutions Inc.
Geographic distribution and regional performance in the Online Education Market
Regional adoption varies significantly, influenced by broadband penetration and government edtech funding. North America leads in corporate compliance spending, while Asia-Pacific exhibits hyper-growth in K-12 and vocational training, spearheaded by regional innovators navigating complex local regulatory frameworks.
In-depth regional review of high-growth territories
Emerging economies in Asia-Pacific and Latin America represent prime expansion zones, supported by smartphone proliferation and affordable mobile data plans. Providers like Simplilearn and Toppr capitalize on these localized dynamics by offering region-specific curriculum and localized payment integrations.
Strategic positioning and company profiles in the Online Education Market
Leading entities employ distinct positioning strategies; for instance, Pearson and McGraw-Hill Educational Services LLC leverage legacy publishing trust, whereas Docebo and Cisco Corporation focus on robust enterprise learning management systems and secure virtual collaboration infrastructure.
Porter's Five Forces analysis of competitive intensity
Supplier power remains low due to abundant content creators, while buyer power is high given plentiful alternative learning platforms. Threat of substitution is mitigated by proprietary certification value, though competitive rivalry among firms like Edmodo and OpenLearning keeps pricing pressures elevated.
SWOT evaluation of the Online Education Market industry
Key strengths include global accessibility and scalable delivery models, contrasted with weaknesses like lower completion rates for unstructured courses. Opportunities abound in AI-driven personalization, while cybersecurity threats and stringent data privacy regulations represent persistent industry-wide risks.
Value chain analysis from technology development to end-users
The value chain flows from software development and content authoring through cloud infrastructure providers to end-users in academia and enterprise. Firms like Oracle Technologies Inc. and SAP SE provide foundational enterprise architecture, ensuring seamless data flow across the entire educational ecosystem.
Strategic investment insights and high-potential opportunity areas
Investors should target niche verticals such as corporate compliance training and rapid e-learning tool development. Companies possessing proprietary application simulation tools and robust mobile optimization offer the highest potential for near-term valuation appreciation and strategic acquisition interest.
Conclusion and key takeaways for stakeholders
The Online Education Market offers compelling growth for forward-thinking stakeholders willing to navigate evolving technological standards and regional compliance hurdles. Capitalizing on the 22.43% CAGR requires aligning product roadmaps with enterprise upskilling and flexible mobile-first delivery demands.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with edtech executives, and secondary macroeconomic indicators. This multi-layered approach ensures precise market sizing and reliable long-term forecasting for the Online Education Market.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue streams across academic and corporate learning segments through 2033. Limitations include unforeseen macroeconomic policy shifts and localized regulatory interventions that may temporarily alter regional adoption velocities without invalidating the broader structural growth thesis.
Recent developments, partnerships, and strategic moves in the industry
Recent market dynamism is characterized by strategic mergers, AI integration partnerships, and cloud infrastructure expansions by firms like PowerSchool Group LLC and Tata Interactive Systems. These corporate maneuvers underscore an industry-wide race to deliver immersive, data-driven learning environments.