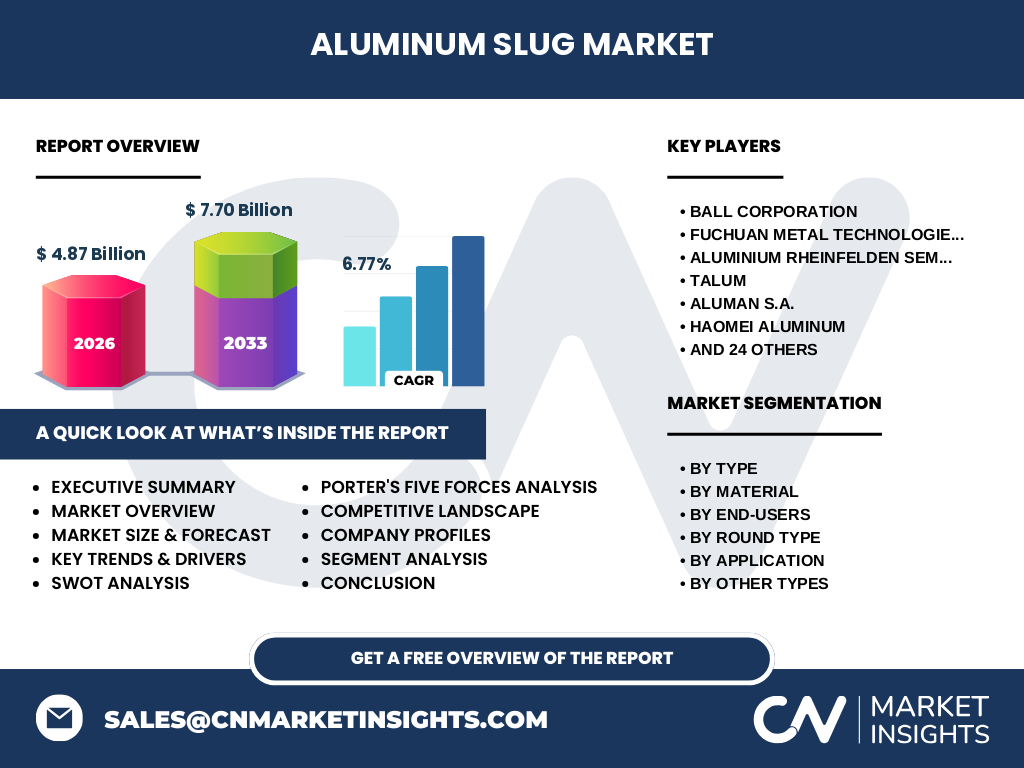
Market overview of the Aluminum Slug Market
The Aluminum Slug Market is valued at $4.87 Billion in 2026, serving as the foundational semi-finished feedstock for impact extrusion processes. These high-purity metal discs are critical inputs manufactured by key players like Novelis Inc. and Impol Aluminum Corporation, destined to be transformed into seamless packaging containers, aerosol cans, and specialized technical components across global manufacturing sectors.
What are the core drivers and challenges shaping the Aluminum Slug Market?
Our analysis indicates that structural growth is propelled by rising demand for sustainable packaging in the personal care and pharmaceutical sectors, championed by innovators like Ball Corporation and Envases Group. Conversely, the market faces persistent headwinds from volatile London Metal Exchange (LME) raw material pricing, strict European REACH environmental regulations, and energy-intensive manufacturing constraints that challenge regional profit margins.
Emerging trends and growth patterns in the Aluminum Slug Market
The data suggests an accelerating shift toward circular economy models, with manufacturers rapidly pivoting to PCR (Post-Consumer Recycled Aluminum) and PIR (Post-Industrial Recycled Aluminum) inputs. Companies such as Norsk Hydro ASA and Constellium SE are leading this green transition, capturing premium market share by offering certified low-carbon slugs that satisfy stringent corporate Scope 3 emissions targets.
How did the COVID-19 pandemic impact the Aluminum Slug Market?
Pandemic-induced supply chain disruptions caused severe procurement bottlenecks for primary aluminum and disrupted operations at major European ports. However, the crisis ultimately accelerated structural demand for pharmaceutical and aerosol packaging, enabling agile suppliers like Alcoa Corporation and Kaiser Aluminum Corporation to orchestrate a robust, margin-accretive recovery trajectory through automated production lines.
Competitive landscape and strategic dynamics of the Aluminum Slug Market
The competitive landscape is moderately consolidated, featuring vertically integrated global giants alongside specialized regional extruders like Fried. v. Neuman GmbH and Alucon Limited. Strategic positioning relies heavily on proprietary alloy development, energy-efficient continuous casting technologies, and long-term supply agreements with major packaging converters to secure high-volume manufacturing contracts across competitive global markets.
Executive summary of the Aluminum Slug Market research report
Our comprehensive executive synthesis reveals that the Aluminum Slug Market is positioned for robust expansion, scaling from $4.87 Billion in 2026 to $7.70 Billion by 2033 at a notable 6.77% CAGR. Growth is heavily underpinned by surging demand for lightweight, infinitely recyclable metal packaging across pharmaceutical, automotive, and personal care end-user verticals.
Market forecast and projected growth trajectory through 2033
Based on our econometric modeling, the Aluminum Slug Market will expand from its 2026 baseline of $4.87 Billion to reach $7.70 Billion by 2033, registering a steady 6.77% CAGR. This trajectory reflects compounding adoption rates for green virgin aluminum and customized round slugs within high-growth emerging economies and technologically advanced manufacturing hubs.
Segmentation analysis across types, materials, and applications
The market demonstrates diverse segmentation dynamics. By type, it spans Round Type, Square And Rectangular Type, Perforated Type, and Other Types. Material breakdowns feature PCR, PIR, and Green Virgin Aluminum. End-user demand is led by automotive, food and beverages, and pharmaceutical applications, utilizing specialized formats like pre-perforated slugs and multi-layered configurations.
Regional market analysis and geographic performance
Geographic distribution highlights distinct regional manufacturing paradigms. Europe maintains a dominant regulatory and sustainability-driven foothold led by specialists like Aluminium-Werke Wutöschingen AG & Co. KG, while Asia-Pacific represents the highest-volume growth engine driven by rapid industrialization, extensive automotive supply chains, and massive domestic packaging consumption in countries like China and India.
In-depth regional review of industrial clusters and trade corridors
Regional performance is anchored by robust industrial ecosystems. North America focuses heavily on high-margin technical parts and aerosol applications supported by Hydro Extrusion North America LLC, whereas European markets prioritize closed-loop recycling loops and stringent carbon border adjustment mechanisms, directly impacting regional slug import dynamics and domestic extrusion economics.
Strategic company profiles in the Aluminum Slug Market
Industry leaders maintain distinct competitive moats. Companies like Novelis Inc. and Norsk Hydro ASA leverage massive upstream smelting integration and proprietary low-carbon alloys. Meanwhile, specialized mid-tier players such as Fuchuan Metal Technologies Co. Ltd. and Talum compete effectively through hyper-customized slug geometries and agile regional distribution networks.
Porter's Five Forces analysis of the industry
Our five forces evaluation shows that supplier power remains moderate due to consolidated primary aluminum producers like Aluminum Bahrain B.S.C. and Hindalco Industries Limited. Buyer power is counterbalanced by the high technical specification requirements for impact extrusion, while the threat of substitution is low given aluminum's unmatched strength-to-weight ratio in packaging.
SWOT analysis of the Aluminum Slug Market
Key market strengths include exceptional metal recyclability and advanced alloy performance. Weaknesses center on high energy consumption during smelting. Opportunities abound in lightweight electric vehicle components and circular packaging mandates, while threats involve persistent macroeconomic tariff volatility and competing polymer packaging innovations.
Value chain analysis from raw materials to end-users
The value chain initiates with bauxite mining and alumina refining by major conglomerates like Alcoa Corporation, flowing into primary aluminum casting. Intermediate processors convert these into precision-cut slugs via continuous casting and punching, which downstream manufacturers then impact-extrude into finished tubes, cans, and structural components for global brand owners.
Investment insights and high-potential areas for stakeholders
Strategic investment should target closed-loop recycling infrastructure and proprietary Green Virgin Aluminum production facilities to capture tightening sustainability premiums. Venture capital and private equity participants will find high growth potential in customized round and perforated slug manufacturing lines servicing the expanding pharmaceutical delivery device sector.
Conclusion and key strategic takeaways
In summary, the Aluminum Slug Market offers compelling growth, projected to reach $7.70 Billion by 2033 at a 6.77% CAGR from its $4.87 Billion baseline in 2026. Success in this sector decisively favors environmentally proactive enterprises investing in circular material sourcing, advanced alloy optimization, and automated, high-precision manufacturing processes.
Research methodology behind our baseline estimates
Our proprietary research methodology triangulates data from multiple authoritative sources. We combine exhaustive primary interviews with C-level executives at firms like UACJ Corporation and Gränges, cross-referenced against global trade registries, customs export-import databases, and secondary macroeconomic indicators to deliver highly accurate market sizing and forecasts.
Scope of the report and analytical boundaries
This report encompasses global market evaluations for the Aluminum Slug Market across all specified material grades, geometric configurations, and end-user verticals from 2026 through 2033. Geographic coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, excluding non-extrusion grade aluminum applications and unverified secondary scrap markets.
Recent developments and strategic corporate maneuvers
Recent industry momentum is defined by aggressive sustainability partnerships and capacity expansions. Market leaders are actively investing in hydrogen-powered melting furnaces and securing long-term renewable energy power purchase agreements, ensuring compliance with tightening international carbon emissions frameworks while scaling production for next-generation aerosol and automotive applications.