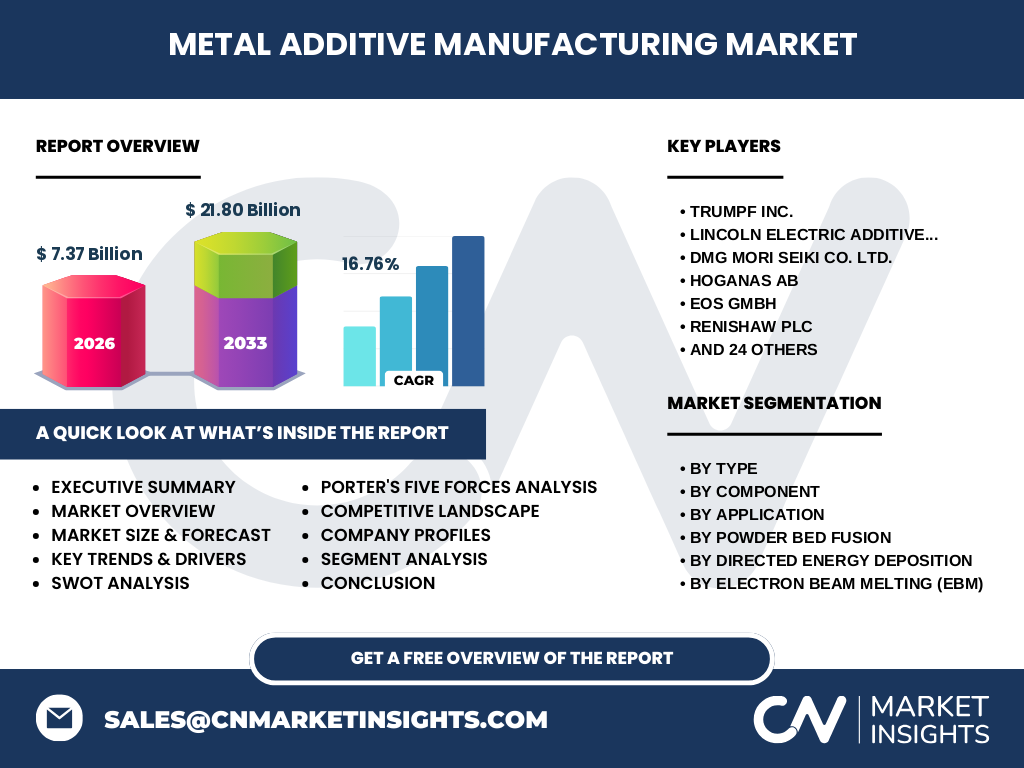
Market overview of the Metal Additive Manufacturing Market
Our analysis indicates that the Metal Additive Manufacturing Market represents a transformative paradigm shift in industrial production, valued at 7.37 Billion in 2026. This sector encompasses advanced technologies like Selective Laser Melting and Electron Beam Melting, which fabricate end-use components directly from 3D CAD data. Operating under stringent regulatory frameworks such as FAA and ISO/ASTM standards, the industry is revolutionizing aerospace, automotive, and medical manufacturing by enabling complex geometries previously impossible with traditional CNC machining.
Structural Growth Drivers and Market Restraints
The market is propelled by a relentless push for lightweighting in aerospace and the demand for patient-specific implants in the medical sector. Key growth catalysts include innovations in reactive metal powders by suppliers like Höganäs AB and high-speed multi-laser systems from pioneers like EOS GmbH. However, growth is constrained by high equipment capital expenditures, qualified feedstock certification hurdles, and stringent occupational safety regulations regarding fine reactive metal dust handling.
Emerging Industry Trends and Technological Shifts
The industry is rapidly shifting toward serial production, moving away from pure prototyping. Automation and closed-loop powder handling are becoming vital to mitigate operator exposure and ensure batch consistency. Innovators such as Desktop Metal Inc. and Markforged Inc. are democratizing metal printing via bound metal deposition, while binder jetting gains traction for high-throughput automotive component manufacturing, significantly reducing cost-per-part metrics.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic severely disrupted global supply chains and aerospace manufacturing schedules, causing temporary contraction in industrial capital spending. However, the crisis acted as an accelerator for digital supply chain resilience. Enterprises increasingly turned to localized AM solutions to bypass maritime shipping bottlenecks. Recovery has been robust, led by critical healthcare demands and aerospace supply chain diversification, laying the groundwork for accelerated post-pandemic commercial adoption.
Competitive Landscape and Strategic Dynamics
Market concentration is moderately high, characterized by aggressive strategic consolidation and intellectual property acquisitions. Industry heavyweights like GE Additive, Trumpf Inc., and 3D Systems Inc. dominate through comprehensive hardware, software, and proprietary material ecosystems. Competitive advantage increasingly hinges on print speed, build volume scalability, and integrated quality assurance software that satisfies rigorous aerospace and medical qualification protocols.
Executive Summary of Key Findings
Our comprehensive research confirms that the Metal Additive Manufacturing Market is entering a hyper-growth phase, projected to surge to 21.80 Billion by 2033 at a robust 16.76% CAGR. Based on our research, this expansion is driven by surging demand for lightweight alloy structures and continuous advancements in machine reliability. Companies mastering serial production economics will capture dominant market share.
Market Forecast from 2027 to 2033
The market trajectory displays exponential growth momentum, expanding from the 2026 baseline of 7.37 Billion to reach 21.80 Billion by 2033. This growth trajectory is underpinned by a sustained 16.76% CAGR. The data suggests that declining feedstock costs, faster deposition rates via technologies like Directed Energy Deposition, and expanding serial manufacturing adoption will be the primary engines of this acceleration.
Segmentation Analysis by Type, Component, and Application
Market segmentation reveals diverse technological adoption. By Type, the market splits across Selective Laser Melting, Electron Beam Melting, Powder Bed Fusion, and Directed Energy Deposition. Components comprise Systems, Materials, and Services/Parts. Applications span Automotive, Aerospace, Healthcare, and Tools. Powder Bed Fusion and the Aerospace sector currently command the largest revenue shares, driven by exacting material property requirements.
Regional Market Analysis and Geographic Distribution
Geographic performance reflects concentrations of advanced industrial manufacturing and aerospace hubs. North America leads in market adoption due to heavy defense spending and early commercial aerospace uptake. Europe follows closely, anchored by stringent environmental regulations and robust automotive engineering centers in Germany. Asia-Pacific is emerging as the fastest-growing region, powered by industrial investments in China, Japan, and South Korea.
In-Depth Regional Review of Key Markets
North America benefits from a mature ecosystem of Tier-1 aerospace contractors and agile AM service bureaus. Europe maintains dominance in high-end medical implants and toolmaking, supported by regional leaders like Renishaw PLC and Materialise NV. Meanwhile, Asia-Pacific growth is propelled by governmental initiatives supporting advanced manufacturing infrastructure, with domestic firms like XiAn Bright Laser Technologies scaling rapidly.
Company Profiles and Strategic Positioning
Leading industry participants employ distinct growth strategies. SLM Solutions Group AG and DMG Mori Seiki Co. Ltd. focus on multi-laser industrial scale machines for heavy manufacturing. Stratasys Ltd. and XJet Ltd. leverage specialized binder jetting and nano-particle jetting technologies. Meanwhile, Norsk Titanium AS and Sciaky Inc. target large-scale structural aerospace components using proprietary Directed Energy Deposition platforms.
Porter's Five Forces Analysis of the Industry
Competitive rivalry is intense among established machine OEMs, while the threat of new entrants remains moderate due to high intellectual property barriers and capital expenditure requirements. Buyer power is high as enterprise clients demand turnkey production cells. Supplier power regarding reactive metal powders is notable, though mitigated by expanding material supplier ecosystems like Höganäs AB.
SWOT Analysis of the Metal Additive Manufacturing Sector
Strengths include design freedom and superior buy-to-fly ratios for aerospace components. Weaknesses involve high machine downtime and slow build rates for massive parts. Opportunities lie in serial production integration and sustainable alloy recycling initiatives. Threats include macroeconomic cyclicality and intellectual property infringement risks in localized digital manufacturing.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with plasma atomization of high-purity metal powders by specialized metallurgists. It flows through software preprocessing, AM system manufacturing by OEMs, printing operations by tier suppliers, and mandatory post-processing like heat treatment and hot isostatic pressing before reaching end-users in aerospace, medical, and automotive sectors.
Investment Insights and High-Potential Areas
High-potential investment vectors include proprietary closed-loop quality monitoring software, post-processing automation startups, and green powder atomization technologies. Our analysis indicates that venture capital and private equity firms should prioritize software and materials innovations over hardware commoditization to maximize long-term valuation returns.
Conclusion and Key Takeaways
The Metal Additive Manufacturing Market is transitioning from a prototyping novelty to an indispensable pillar of modern industrial manufacturing. With a projected 16.76% CAGR reaching 21.80 Billion by 2033, stakeholders must prioritize software integration, material qualification, and automation to unlock true serial production economics.
Research Methodology and Data Triangulation
Baseline estimates are triangulated using a rigorous mixed-methods approach. This combines trade registry data, customs import-export logs for metal powders and machinery, primary stakeholder interviews with C-suite executives across OEMs, and secondary macroeconomic indicators from manufacturing indices to ensure high statistical fidelity.
Scope of the Report and Coverage Parameters
This report covers global market sizing and forecasting from 2027 to 2033, analyzing regional dynamics, technology types, components, and core industrial applications. Limitations include the exclusion of non-metal additive technologies (such as polymers and ceramics) and unregistered localized shadow manufacturing operations.
Recent Industry Developments and Strategic Moves
Recent market activity is characterized by strategic partnerships between aerospace primes and AM system providers, alongside joint ventures aimed at aerospace powder recycling. Companies like Desktop Metal Inc. and 3D Systems Inc. have announced high-speed platform commercialization, while regional funding rounds in Asia-Pacific have accelerated local adoption of large-format electron beam systems.