What is the scope and industry significance of the Magnesite Market?
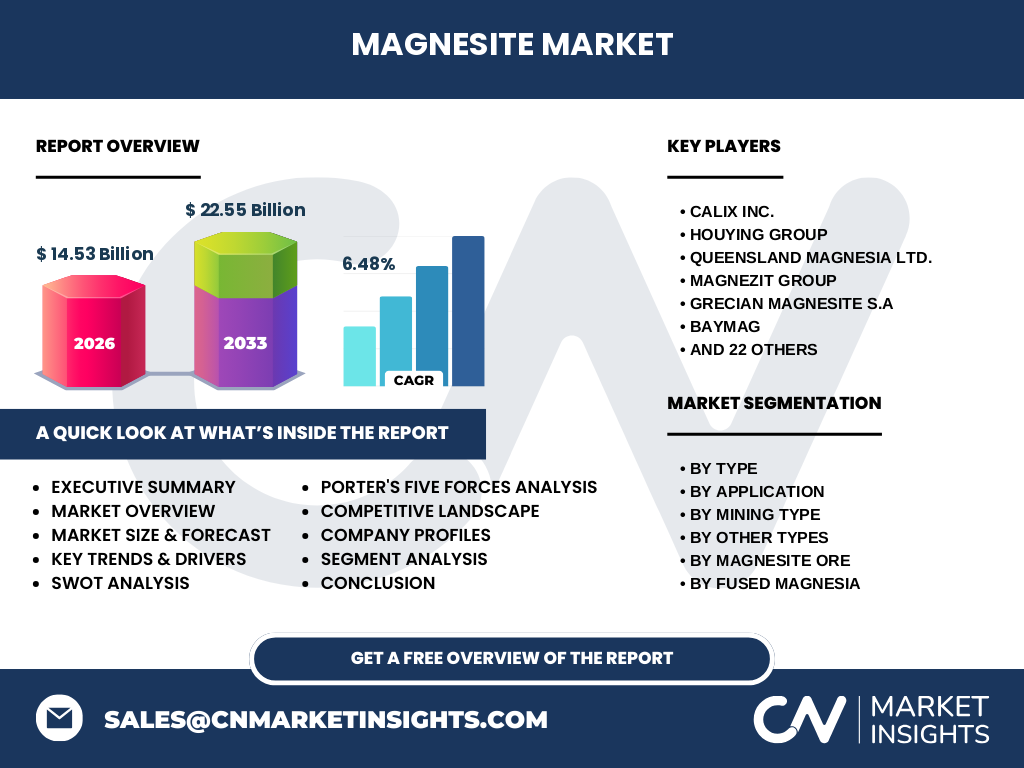
Our analysis indicates that the Magnesite Market represents a foundational pillar for global industrial manufacturing, encompassing the extraction and processing of magnesium carbonate. Valued at 14.53 Billion in 2026, the sector is heavily anchored by critical applications in steelmaking refractories and environmental remediation, driving heavy industry standards forward.
What are the structural growth drivers and challenges shaping the Magnesite Market?
The market is propelled by surging demand for high-temperature refractory materials in basic oxygen furnaces. However, strict environmental compliance by bodies like the European Union and logistical bottlenecks at key export ports constrain raw material output. Balancing strict decarbonization mandates with rising production quotas remains a primary operational hurdle.
Emerging trends and growth patterns in the Magnesite Market
Industry shifts center on the adoption of high-purity fused magnesia for specialized electrical insulation and advanced ceramic components. Manufacturers are increasingly deploying proprietary calcination technologies to reduce carbon footprints, aligning production workflows with stringent global sustainability goals.
How did COVID-19 impact the Magnesite Market and shape its recovery?
Pandemic-induced supply chain fractures and temporary automotive shutdowns severely curtailed demand for caustic calcined magnesia. Recovery has been robustly led by post-lockdown infrastructure stimulus packages and accelerated modernization within global steel mills, stabilizing supply lines across major trade corridors.
Competitive Benchmarking: Major players and strategic dynamics
The Magnesite Market exhibits moderate consolidation, led by tier-one producers like RHI Magnesita GmbH and Magnezit Group. These market leaders leverage vertically integrated supply chains and proprietary sintering methods to secure long-term procurement contracts with multinational steel conglomerates.
Executive Summary: High-level synthesis of key findings
Driven by robust industrial expansion, the Magnesite Market industry trends point toward a solid valuation of 22.55 Billion by 2033. Operating at a steady CAGR of 6.48% from 2027, profitability heavily favors firms investing in advanced dead-burned magnesia technologies.
Market forecast and valuation trajectory from 2027 to 2033
Based on our research, the Magnesite Market market size will expand from its 2026 baseline of 14.53 Billion to reach 22.55 Billion by 2033. This consistent expansion at a 6.48% CAGR underscores sustained demand across refractory and agricultural end-use segments.
Segmentation analysis across product types and applications
The market is deeply segmented by product types—including Magnesite Ore, Dead-Burned Magnesia, and Fused Magnesia—and end-use applications spanning refractory materials, agriculture, and construction. Dead-Burned Magnesia dominates consumption due to its essential role in maintaining high-performance cement kiln linings.
Geographic distribution and regional performance dynamics
Regional performance is heavily skewed toward Asia-Pacific, driven by massive steel manufacturing hubs in China and India. Meanwhile, North American and European markets prioritize high-purity caustic calcined magnesia for specialized environmental applications and strict agricultural soil amendment protocols.
In-depth regional review of key operational hubs
China remains the dominant producer and consumer of raw magnesite, leveraging rich domestic deposits in Liaoning province. Conversely, European operations—anchored by players like Grecian Magnesite S.A.—focus on high-value specialty grades to navigate stringent regional mining regulations and carbon tax frameworks.
Company profiles and strategic positioning of leading enterprises
Key market participants such as Calix Inc. and Baymag focus on sustainable calcination techniques to capture eco-conscious market share. Meanwhile, industrial giants like Houying Group utilize massive output capacities to maintain dominance in high-volume dead-burned magnesia supply chains.
Porter's Five Forces analysis of competitive pressures
Bargaining power of raw material suppliers remains moderate-to-high due to geographic concentration of high-grade ore reserves. Threat of substitutes is low, given the irreplaceable thermal stability provided by fused and dead-burned magnesia in extreme high-temperature industrial furnaces.
SWOT analysis of the industrial landscape
Key strengths include the exceptional thermal properties of processed magnesite, while critical weaknesses involve high energy intensity during calcination. Opportunities abound in renewable energy storage materials, though strict environmental emission caps present a persistent, sector-wide threat.
Value chain analysis from raw extraction to end-user deployment
The value chain initiates with surface or underground mining of raw magnesite ore, progressing through energy-intensive calcination, crushing, and sintering stages. Value multiplication peaks during the synthesis of fused magnesia for electrical insulation and high-temperature ceramic applications.
Investment insights and high-potential growth areas
High-potential capital allocation targets low-emissions processing technology and premium fused magnesia production facilities. Investors should monitor firms integrating green energy solutions to bypass escalating carbon pricing penalties across regulated manufacturing jurisdictions.
Conclusion and strategic industry takeaways
The Magnesite Market offers lucrative growth for proactive stakeholders, backed by a projected valuation of 22.55 Billion by 2033. Success relies on navigating environmental mandates while scaling production of high-margin refractory and agricultural magnesium compounds.
Research methodology and data triangulation protocols
Our baseline estimates are rigorously triangulated by cross-referencing national mining registry data, primary stakeholder interviews with C-suite executives, and macroeconomic industrial output indices. This multi-layered approach ensures precise market sizing and reliable long-term forecasts.
Scope of the report and analytical boundaries
This report covers global production, trade flows, and consumption patterns across key grades of magnesite from 2026 to 2033. Analytical limitations include unpredicted geopolitical disruptions affecting regional export quotas and sudden shifts in global steel output forecasts.
Recent developments, corporate partnerships, and strategic moves
Recent industry momentum highlights strategic joint ventures focused on carbon capture integration within calcination plants. Major players are aggressively expanding fused magnesia capacities to meet soaring electrical vehicle infrastructure demands and advanced ceramic manufacturing specifications.