What is the baseline market overview and industrial significance of the Refractories Market?
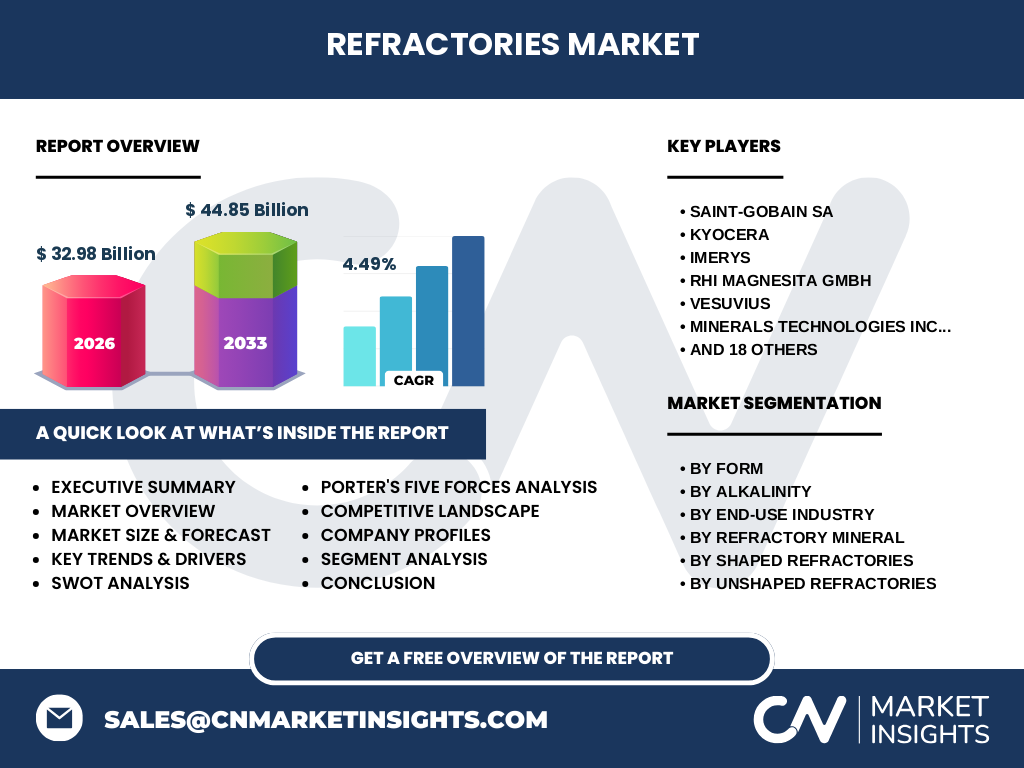
Our analysis indicates that the Refractories Market reaches a valuation of $32.98 Billion in 2026. These specialized thermal-resistant materials form the indispensable backbone of high-temperature industrial processing, protecting core infrastructure in iron-making, cement calcination, and petrochemical cracking from extreme thermal shock and corrosive slag attack.
Key market drivers, restraints, challenges, and opportunities shaping the Refractories Market
Growth is propelled by rising crude steel production and stringent energy efficiency mandates enforced by bodies like the World Steel Association. However, strict environmental regulations governing volatile emissions from synthetic binders and raw material price volatility constrain margins, creating strong opportunities for monolithic innovations.
Emerging trends and growth patterns in the Refractories Market
The industry is experiencing a decisive pivot toward sustainable, carbon-free unshaped solutions and recycling technologies. Major producers like RHI Magnesita and Vesuvius are heavily investing in digital kiln-monitoring services to optimize thermal efficiency and reduce specific energy consumption across client sites.
How did the COVID-19 pandemic affect the Refractories Market and shape its recovery trajectory?
The pandemic triggered severe supply chain disruptions across critical mineral corridors for bauxite and flake graphite, leading to temporary blast furnace shutdowns. Recovery has been robust, accelerated by post-pandemic fiscal stimulus packages targeting global infrastructure and greenfield manufacturing buildouts.
Competitive Benchmarking and Market Concentration in the Refractories Sector
The landscape features a consolidated tier of global giants alongside agile regional specialists. Industry leaders such as Saint-Gobain, Calderys, and Shinagawa Refractories leverage extensive distribution networks and proprietary mineral reserves to dominate high-margin steel and non-ferrous applications.
Executive Summary: High-Level Synthesis of the Refractories Market
Driven by intense thermal processing demands, the Refractories Market is positioned for sustained expansion. Based on our research, the sector is projected to surge from $32.98 Billion in 2026 to $44.85 Billion by 2033, reflecting a solid CAGR of 4.49%.
Market Forecast: Growth Trajectory from 2027 to 2033
The data suggests a steady upward trajectory, expanding the Refractories Market from its 2026 baseline to reach $44.85 Billion by 2033 at a CAGR of 4.49%. This growth is underpinned by rising urbanization in emerging economies and rapid technological upgrades in industrial furnaces.
Segmentation Analysis of the Refractories Industry
The market is classified by Form (Shaped, Unshaped), Alkalinity (Acidic and Neutral, Basic), End-Use Industry (Iron and Steel, Power Generation, Non-Ferrous Metals, Cement, Glass, Others), Mineral type (Bauxite, Alumina, Kaolin, Magnesia, Graphite, Zircon), and sub-segments like bricks, castables, and ramming masses tailored for specific thermal wear zones.
Geographic Distribution and Performance Across Regional Markets
Geographic performance is heavily skewed toward regions with dense heavy industrial manufacturing bases. Asia-Pacific dominates consumption due to massive steel output in China and India, while North America and Europe focus on high-performance monolithic solutions and stringent environmental compliance.
In-Depth Regional Review of High-Growth Industrial Corridors
Asia-Pacific remains the primary growth engine, supported by extensive port infrastructure in Shanghai and Tianjin facilitating raw material imports. Meanwhile, European markets face strict decarbonization pressures from the European Union Emissions Trading System, forcing rapid adoption of carbon-neutral refractory formulations.
Strategic Positioning of Leading Companies in the Refractories Market
Market participants deploy distinct competitive strategies: Morgan Advanced Materials and Imerys focus on specialty high-purity minerals, while HarbisonWalker International and Krosaki Harima emphasize comprehensive refractory management services and localized manufacturing footprint optimization.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of suppliers is moderate-to-high due to localized mining monopolies for refractory-grade bauxite and magnesia. Rivalry among established players is intense, while the threat of substitutes remains constrained by the extreme physical demands of industrial furnaces.
SWOT Analysis of the Refractories Sector
Strengths include advanced thermal performance and deep client integration. Weaknesses involve high energy intensity during manufacturing. Opportunities lie in eco-friendly monolithic formulations, while threats stem from geopolitical trade tariffs on critical raw materials and macroeconomic cyclicality.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with mining raw minerals like bauxite and graphite, progressing through calcination, precise grading, and manufacturing into shaped bricks or unshaped castables. It culminates in professional installation and recycling services for heavy industries like steelmaking.
Investment Insights and High-Potential Areas for Stakeholders
High-potential investment opportunities lie in proprietary recycling technologies for spent refractory linings and advanced digital installation tools. Investors should prioritize firms partnering with steelmakers on net-zero carbon initiatives to secure long-term supply agreements.
Conclusion and Key Takeaways for Industry Participants
The Refractories Market offers robust expansion opportunities, moving steadily toward a valuation of $44.85 Billion by 2033. Success in this evolving landscape requires continuous innovation in eco-efficient product portfolios and proactive alignment with global decarbonization mandates.
Research Methodology for Baseline Estimates and Market Triangulation
Our baseline estimates are derived through rigorous triangulation, combining trade registry data from key ports, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators from the International Monetary Fund to ensure absolute data integrity.
Scope of the Report and Coverage Parameters
This comprehensive research report covers global and regional market sizing, exhaustive segment breakdowns, and competitive benchmarking. Limitations include unpredictable geopolitical shifts impacting raw material mining quotas and sudden trade policy alterations in major producing economies.
Recent Developments in Corporate Partnerships and Strategic Moves
Recent strategic moves highlight an acceleration of green partnerships, with firms like Calderys and RHI Magnesita launching joint ventures focused on automated gunning technologies and circular-economy recycling initiatives designed to reduce industrial landfill waste significantly.