What is the market overview and industry significance of the Crushed Stones Market?
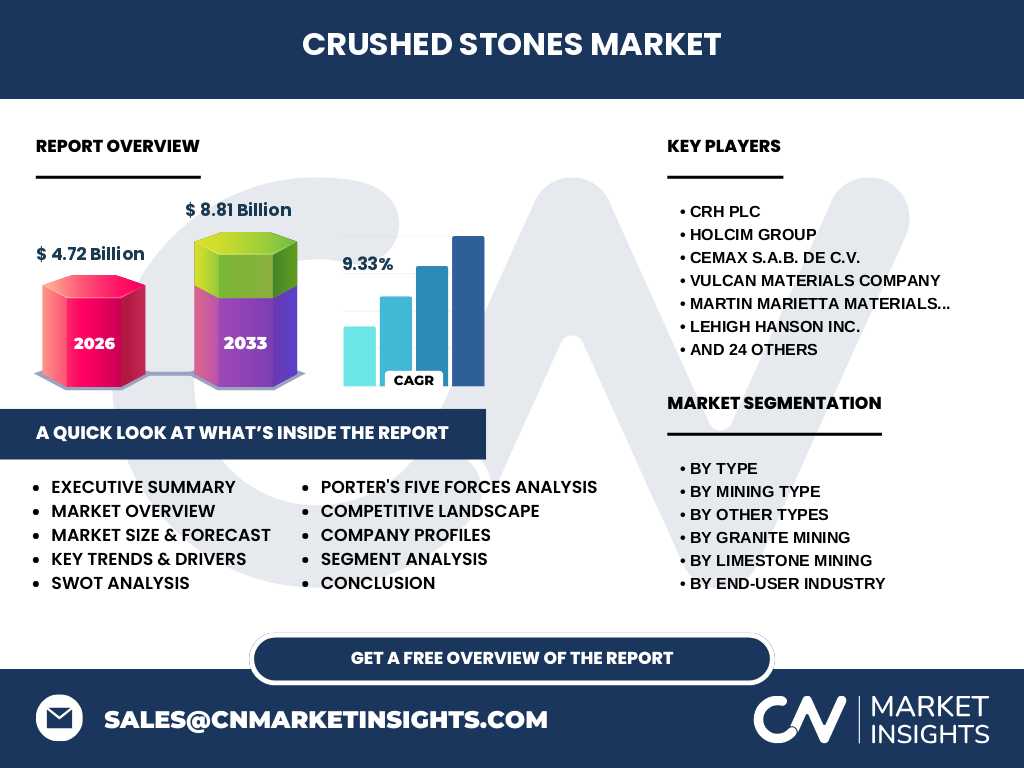
Our analysis indicates that the Crushed Stones Market represents a foundational pillar of global infrastructure development, processing essential raw materials like limestone, granite, and sandstone for heavy civil engineering. The industry in 2026 stands at a robust 4.72 Billion, serving as the bedrock for aggregate supply chains regulated by bodies like the Mine Safety and Health Administration.
Key market drivers, restraints, challenges, and opportunities shaping the Crushed Stones Market
Growth is propelled by aggressive urbanization and transportation investments, though constrained by strict environmental permitting from agencies such as the EPA. Logistics bottlenecks and high freight costs present persistent operational challenges, yet surging demand for sustainable, high-calcium limestone opens lucrative avenues for vertically integrated suppliers to expand margins.
Emerging trends and growth patterns in the Crushed Stones Market
The industry is witnessing a rapid shift toward automated surface mining and digital fleet management to optimize extraction efficiency. Producers increasingly leverage high-calcium and dolomitic limestone innovations to meet stringent decarbonization targets in cement manufacturing and steel metallurgy across major industrial corridors.
COVID-19 impact analysis and recovery trajectory
The pandemic initially fractured regional supply chains and halted non-essential quarry operations, causing severe logistical friction for surface and underground mining. However, robust post-pandemic fiscal stimulus packages injected into transportation infrastructure sparked a sharp V-shaped recovery, elevating demand well past pre-crisis baselines.
Competitive landscape of the Crushed Stones Market
Market concentration remains moderately high, dominated by global giants like CRH plc, Holcim Group, and Vulcan Materials Company. These market leaders leverage extensive reserve footprints and strategic port access to control regional pricing power, while regional players like Martin Marietta Materials and Summit Materials compete aggressively through localized quarry acquisitions.
Executive summary of key findings
Our comprehensive research projects the Crushed Stones Market to expand significantly, reaching 8.81 Billion by 2033 at a CAGR of 9.33%. Accelerated by infrastructure modernization and heavy industrial demand, market leaders are aggressively consolidating limestone and granite reserves to secure long-term pricing dominance.
Market forecast from 2027 to 2033
Driven by sustained macroeconomic investments in public works, the market trajectory displays explosive momentum. The data projects total valuation to scale from 2027 through 2033, achieving a stellar CAGR of 9.33% to culminate at 8.81 Billion, heavily favoring suppliers with expansive high-calcium limestone reserves.
Segmentation analysis of product types and end-users
The market breaks down by Type into Limestone, Granite, and Other Types including Sandstone, Dolomite, and Basalt. Mining methods span Surface Mining and Underground Mining. End-user demand is heavily anchored by Construction and Infrastructure, Cement Manufacturing, and Steel and Metallurgy.
Regional market analysis and geographic distribution
Geographic performance is dictated by proximity to major metropolitan development zones and navigable waterways essential for cost-effective aggregate transport. North America and Europe dominate consumption due to aging infrastructure overhaul, whereas Asia-Pacific demonstrates the fastest expansion speed fueled by aggressive urbanization and industrialization.
In-depth regional review of key markets
North America remains a high-margin stronghold supported by key players like Vulcan Materials and Martin Marietta, navigating stringent state-level zoning laws. Meanwhile, European markets focus on eco-compliant quarrying practices, and developing regions accelerate surface mining output to feed massive transportation infrastructure projects.
Company profiles and strategic positioning
Industry titans such as Cemex S.A.B. de C.V., Lehigh Hanson, and HeidelbergCement AG strategically position themselves via vertical integration, owning everything from primary quarries to downstream asphalt plants. Specialized regional operators like Luck Stone and Dolese Bros. maintain formidable regional moats through dedicated local customer relationships.
Porter's Five Forces analysis
Bargaining power of buyers is moderate due to standardized aggregate specifications, though offset by high local freight costs. Threat of new entrants remains remarkably low, constrained by massive capital expenditure requirements for quarry permits, environmental compliance, and rich limestone or granite reserve acquisition.
SWOT analysis of the sector
Key strengths lie in vast asset-backed reserves and indispensable utility across all construction phases, balanced against regulatory weaknesses regarding carbon emissions. Major opportunities include green cement integration, while primary threats involve stringent environmental litigation and escalating local zoning restrictions.
Value chain analysis from raw materials to end-users
The value flow begins with geological surveying and heavy surface or underground extraction, moves through crushing, screening, and washing phases, and terminates in logistical distribution via rail, barge, or truck to construction sites, cement plants, and steel mills.
Investment insights and high-potential areas
Investors should direct capital toward quarry assets possessing high-calcium limestone and strategic proximity to high-growth transportation infrastructure hubs. Companies investing in automated, low-emission crushing technologies present prime acquisition targets for major conglomerates seeking ESG compliance.
Conclusion and key takeaways
The Crushed Stones Market offers exceptional investment upside, backed by a projected valuation of 8.81 Billion by 2033. Stakeholders must prioritize operational sustainability, localized reserve control, and logistical efficiency to capture outsized market share during this high-growth cycle.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data, annual financial filings from publicly traded entities like CRH and Holcim, primary stakeholder interviews with quarry operators, and macroeconomic construction indices provided by federal oversight bodies.
Scope of the report and coverage parameters
This report evaluates global market dynamics, volume shipments, and revenue valuations across specified product segments from 2026 to 2033. Excluded from this scope are decorative dimension stones and specialized non-aggregate industrial minerals unless utilized directly in cement or metallurgy.
Recent developments, partnerships, and strategic moves
Market participants are actively engaging in strategic bolt-on acquisitions of local aggregate reserves to optimize supply chain resilience. Recent announcements highlight major investments in electrified mining fleets and proprietary crushers aimed at reducing carbon footprints while expanding high-calcium limestone output.