What is the scope and industry significance of the Tight Gas Market?
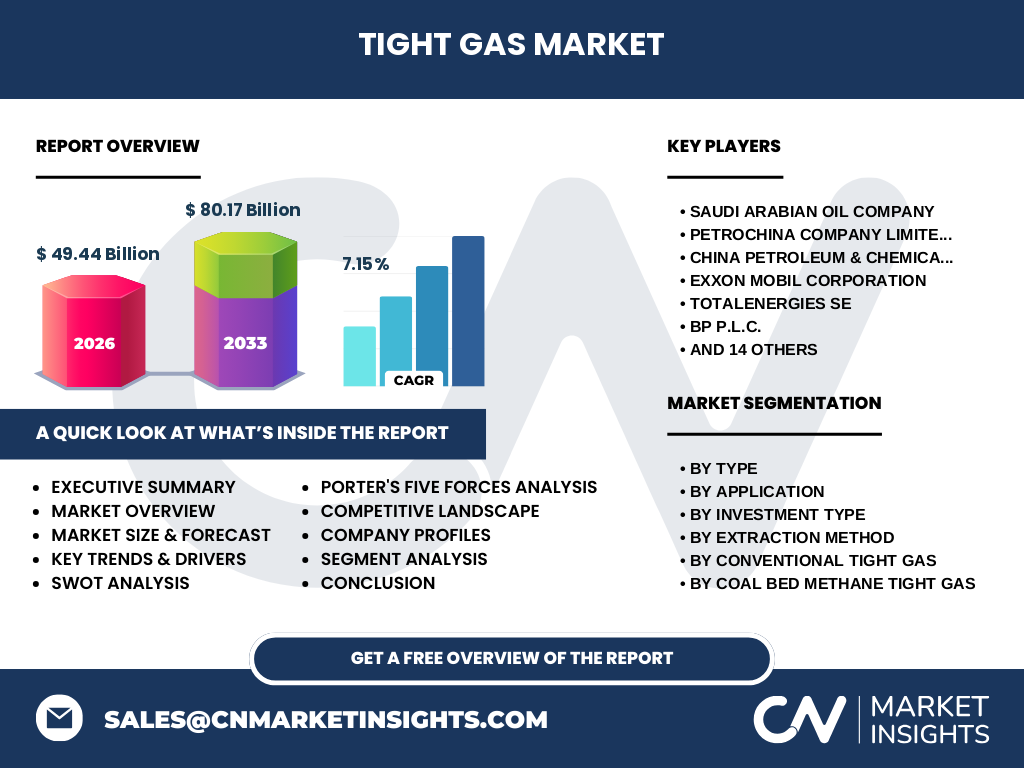
The Tight Gas Market represents a critical frontier in unconventional energy, valued at $49.44 Billion in 2026. Our analysis indicates that developing low-permeability sandstone and carbonate reservoirs is essential for offsetting declining conventional reserves, heavily regulated by bodies like the EIA and regional environmental agencies.
Key market drivers, restraints, challenges, and opportunities shaping Tight Gas Market
Growth is propelled by horizontal drilling innovations, though water scarcity and strict EPA mandates act as heavy restraints. Operators face severe logistical hurdles in remote basins, creating prime opportunities for proprietary proppant technologies and advanced hydraulic fracturing optimization.
Emerging trends and growth patterns in Tight Gas Market
The industry is witnessing a rapid shift toward digital oilfield integration and real-time microseismic monitoring. Data-driven completion optimization allows major operators to maximize cluster efficiency in unconventional tight gas shale reservoirs, significantly reducing wellhead breakeven costs.
COVID-19 impact analysis — how the pandemic affected Tight Gas Market and the recovery trajectory
Pandemic-induced demand destruction forced severe capital expenditure retrenchment across major North American basins. However, our research confirms a robust post-pandemic rebound, as structural energy security concerns accelerated upstream re-evaluations and greenlit stalled midstream infrastructure projects.
Competitive landscape — major players, market concentration, and strategic dynamics
Market concentration is high, dominated by supermajors and aggressive independents. Industry leaders like Saudi Arabian Oil Company, Exxon Mobil Corporation, and BP p.l.c. leverage immense balance sheets to acquire prime acreage, while specialists like EOG Resources Inc. drive horizontal drilling efficiency.
Executive summary — high-level synthesis of key findings about Tight Gas Market
Positioned for rapid expansion, the Tight Gas Market industry trends point toward sustained monetization of complex geology. With a projected valuation of $80.17 Billion by 2033, stakeholders must prioritize technological agility and stringent environmental compliance.
Market forecast — projected growth from 2027 to 2033
Our forecasting models project the market to expand from 2027 through 2033 at a steady CAGR of 7.15%. This trajectory will push total market valuation to $80.17 Billion, driven by relentless global energy demand and improved well productivity in unconventional plays.
Segmentation analysis — break down each segment category, explain what it covers and its market role
The market segments by Type into Conventional Tight Gas, Unconventional Tight Gas Shale Reservoirs, and Coal Bed Methane Tight Gas. Applications span Residential, Commercial, Industrial, Transportation, and Power Generation, while investment focuses on exploration, production, and midstream infrastructure.
Regional market analysis — geographic distribution and performance across regions
Geographic performance is heavily skewed toward North America due to mature shale infrastructure, closely followed by rising production in Asia-Pacific and the Middle East. Regional performance depends heavily on local pipeline network capacity and proximity to major industrial demand hubs.
In-depth regional review — detailed examination of key regional markets
North America remains the epicenter of activity, supported by prolific plays operated by firms like Devon Energy Corporation and Chesapeake Energy Corporation. Meanwhile, China is accelerating domestic unconventional extraction via state-backed entities to meet stringent national decarbonization and energy security quotas.
Company profiles — strategic positioning of leading companies in Tight Gas Market
Industry titans such as TotalEnergies SE, Chevron Corporation, and ConocoPhillips Company utilize diversified asset portfolios to hedge against commodity volatility. Regional players like YPF S.A. and Valeura Energy Inc. focus on hyper-localized geological optimization to secure competitive advantages.
Porter's Five Forces analysis — competitive forces assessment
Bargaining power of suppliers is moderate, constrained by specialized hydraulic fracturing fleet availability. Rivalry is intense among established exploration companies like Pioneer Natural Resources Company and Ovintiv Inc., while the threat of substitution from renewables is partially mitigated by industrial heating demands.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Key strengths lie in advanced extraction tech and vast resource bases, countered by high initial capital expenditures and water management weaknesses. Opportunities abound in liquefied natural gas export integration, whereas regulatory tightening remains a persistent threat to baseline profitability.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain flows from seismic surveying and raw material procurement like proppants, through hydraulic fracturing execution by firms like Halliburton-backed fleets, down to midstream gas gathering, compression, and final distribution to power generation and industrial end-users.
Investment insights — strategic recommendations and high-potential areas
Investors should target midstream infrastructure assets and operators pioneering waterless fracturing technologies. Capitalizing on firms with low debt-to-equity ratios, such as Continental Resources Inc. and Southwestern Energy Company, minimizes exposure to near-term commodity price swings.
Conclusion and key takeaways
The Tight Gas Market market size expansion to $80.17 Billion underscores its vital role in the global energy mix. Success requires marrying aggressive horizontal drilling techniques with robust environmental risk mitigation strategies.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by combining proprietary trade registry data, primary stakeholder interviews with executives from Range Resources Corporation, and secondary macroeconomic indicators from international energy agencies to ensure unmatched analytical precision.
Scope of the report — coverage parameters and limitations
This report encompasses comprehensive global data across onshore and offshore conventional formations, shale reservoirs, and coal bed methane assets. Macroeconomic disruptions or sudden geopolitical shifts affecting LNG shipping lanes remain inherent analytical boundaries for these projections.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent strategic moves feature aggressive acreage swaps and joint ventures aimed at emissions reduction. Major operators like PetroChina Company Limited and China Petroleum & Chemical Corporation have heavily invested in carbon capture integration for tight gas processing facilities.