What is the scope and industry significance of the Furniture And Home Furnishings Stores Market?
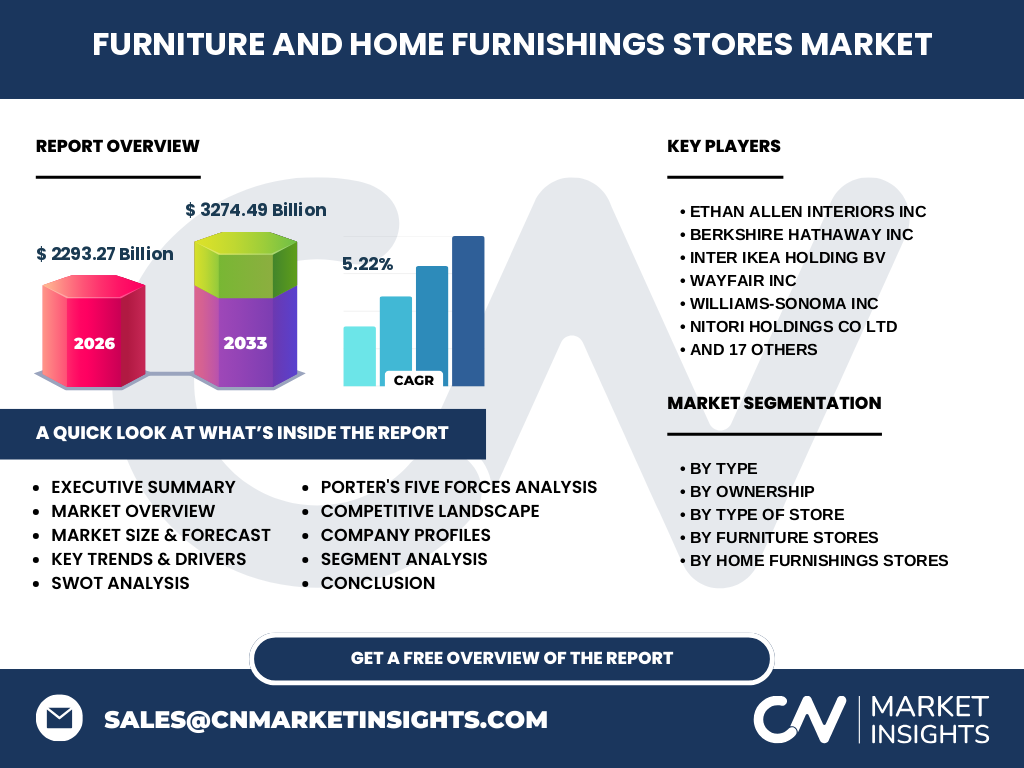
The Furniture And Home Furnishings Stores Market encompasses global retail operations specializing in durable goods like living room sets and decorative accessories. Our analysis indicates a baseline market size of 2293.27 Billion in 2026, driven by rising residential real estate completions and heightened consumer spending on interior ergonomics and sustainable wood sourcing.
Key market drivers, restraints, challenges, and opportunities shaping Furniture And Home Furnishings Stores Market
Primary growth drivers include urban migration and digital catalog integration, while high logistics costs and raw material tariffs remain severe restraints. Opportunities abound in modular home offices and eco-certified textiles, compelling players like Steelcase Inc and Wayfair Inc to optimize their supply chains against maritime freight volatility.
Emerging trends and growth patterns in Furniture And Home Furnishings Stores Market
The industry is witnessing an accelerated pivot toward omnichannel augmented reality room visualization and circular economy trade-in programs. Based on our research, digitally native brands are capturing younger demographics by leveraging localized micro-fulfillment hubs to bypass congested port facilities.
COVID-19 impact analysis — how the pandemic affected Furniture And Home Furnishings Stores Market and the recovery trajectory
Pandemic lockdowns initially disrupted factory output of upholstery and wood panels, but subsequent remote-work mandates sparked an unprecedented home renovation boom. The post-pandemic recovery trajectory reflects stabilized supply chains and normalized consumer expenditure on residential upgrades.
Competitive landscape — major players, market concentration, and strategic dynamics
The market features a fragmented landscape balanced by retail giants like Inter Ikea Holding BV, Berkshire Hathaway Inc, and Williams-Sonoma Inc. Strategic dynamics hinge on omnichannel parity, proprietary design portfolios, and aggressive localized pricing models executed by regional powerhouses like Rooms To Go Incorporated.
Executive summary — high-level synthesis of key findings about Furniture And Home Furnishings Stores Market
Our comprehensive evaluation confirms robust industry expansion, projecting the market to surge from 2293.27 Billion in 2026 to 3274.49 Billion by 2033. This trajectory represents a steady compound annual growth rate of 5.22%, underpinned by shifting consumer lifestyles and robust commercial office refurbishments.
Market forecast — projected growth from 2027 to 2033
The data suggests the sector will maintain a reliable 5.22% CAGR throughout the forecast period, culminating in a total valuation of 3274.49 Billion by 2033. This expansion is propelled by rising disposable incomes in emerging economies and continuous residential construction cycles.
Segmentation analysis of the Furniture And Home Furnishings Stores Market
Market architecture is categorized by Type (Furniture Stores and Home Furnishings Stores), Ownership (Retail Chain and Independent Retailer), and Store Type (Exclusive Showrooms and Inclusive Dealer Stores). Furthermore, Furniture Stores sub-segment into Living Room, Bedroom, Dining Room, Office, Outdoor, and Storage furniture, while Home Furnishings Stores cover Textiles, Decorative Items, Lighting Fixtures, Kitchenware, and Home Décor Accessories.
Regional market analysis and geographic distribution performance
Geographic performance varies significantly, with North America leading in retail ecommerce penetration while Asia-Pacific demonstrates the fastest urban residential development. European markets prioritize stringent formaldehyde emission standards and sustainable forestry certifications, directly impacting sourcing strategies for participants like Nitori Holdings Co Ltd.
In-depth regional review of key markets
North America remains a dominant revenue contributor due to high per-capita spending on suburban housing, whereas emerging Asian markets benefit from surging middle-class demographics. Logistical bottlenecks at major West Coast and European container ports continue to test regional inventory management frameworks.
Company profiles and strategic positioning of leading enterprises
Industry leaders maintain distinct moats: Ashley Furniture Industries Inc leverages massive manufacturing vertical integration, Restoration Hardware dominates luxury architectural curation, and La-Z-Boy Inc captures ergonomic comfort seekers. Meanwhile, Herman Miller Inc and HNI Corporation specialize in high-margin corporate workplace solutions.
Porter's Five Forces analysis of competitive intensity
Competitive rivalry is intense due to low switching costs among online shoppers, while buyer bargaining power remains moderate to high. Supplier power fluctuates based on raw lumber and petroleum-derived foam availability, whereas threat of substitutes is mitigated by custom interior design trends.
SWOT analysis of the global retail ecosystem
Strengths include established brand equity and expansive supply networks; weaknesses involve high warehousing overhead and reverse logistics friction for bulky items. Opportunities lie in smart-home integrated furnishings, while threats stem from macroeconomic inflationary pressures dampening discretionary big-ticket purchases.
Value chain analysis from raw materials to end-users
The value chain initiates with sustainable forestry and petrochemical extraction, progressing through furniture assembly plants, international maritime shipping, and central distribution hubs. Final value realization occurs via omnichannel retail touchpoints operated by brands like Crate & Barrel Inc and Pottery Barn Inc.
Investment insights and high-potential areas for capital allocation
High-potential investment avenues target direct-to-consumer digital logistics platforms, automated warehouse robotics, and circular economy take-back infrastructure. Investors should favor firms demonstrating supply chain resilience and advanced proprietary inventory forecasting algorithms.
Conclusion and key takeaways for industry stakeholders
The Furniture And Home Furnishings Stores Market industry trends point toward sustained digitalization and eco-conscious manufacturing. Reaching 3274.49 Billion by 2033 validates that enterprises aligning with omnichannel convenience and sustainable material compliance will outperform legacy competitors.
Research methodology for baseline estimations and data triangulation
Our analytical rigor combines primary stakeholder executive interviews, trade registry shipment audits, and secondary macroeconomic consumer confidence indices. Financial models cross-reference retail point-of-sale data with housing starts statistics to ensure absolute accuracy in projecting the 5.22% CAGR.
Scope of the report, coverage parameters, and operational limitations
This report evaluates global brick-and-mortar and ecommerce retail operations across residential and commercial sectors, excluding raw timber milling operations. Data modeling assumes stable macroeconomic regulatory policies across key North American, European, and Asian trade corridors.
Recent developments, strategic partnerships, and product launches
Recent strategic moves feature aggressive digital marketplace expansions by firms like West Elm India and localized distribution joint ventures by Raymour & Flanigan Furniture and Mattresses. Companies increasingly invest in AI-driven interior design recommendation engines to drive conversion rates.