What is the market overview and scope of the Nuclear Fuel Market?
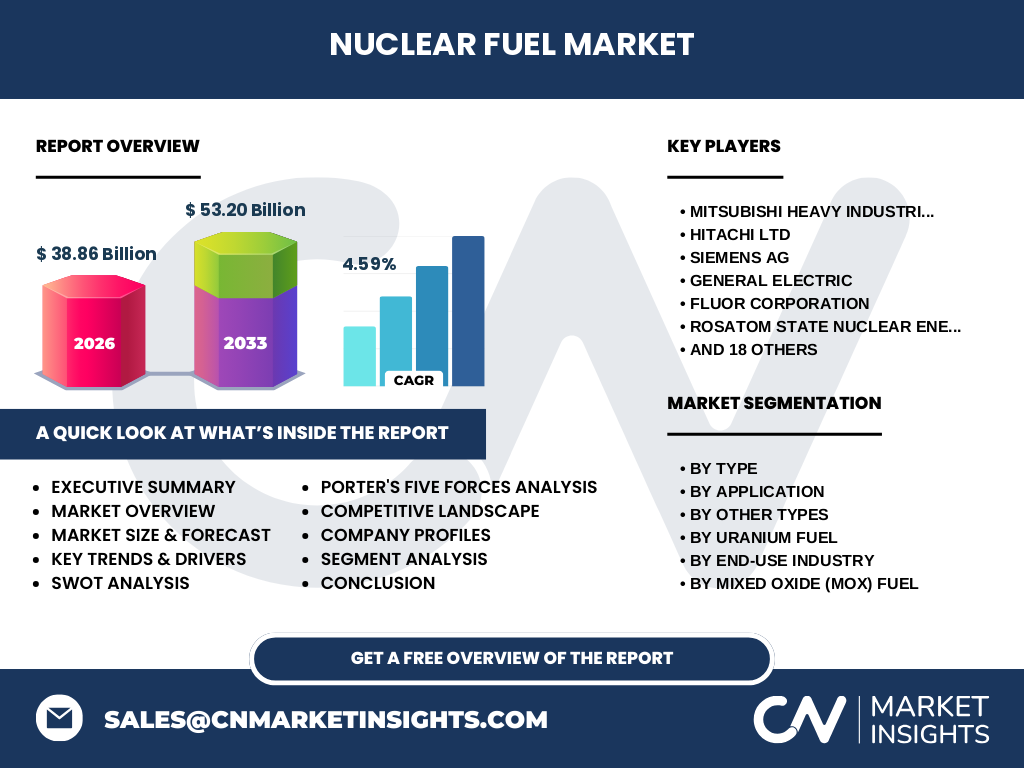
Our analysis indicates that the Nuclear Fuel Market size is valued at 38.86 Billion in 2026. This sector encompasses the end-to-end lifecycle of nuclear materials, including mining, conversion, enrichment, and fabrication for reactor cores, serving as the foundational energy backbone for global base-load electricity generation.
Structural Growth Drivers and Market Restraints
The market is propelled by decarbonization mandates and rising clean energy demand, though restrained by stringent regulatory hurdles from bodies like the IAEA and high capital expenditure. Geopolitical supply chain bottlenecks involving raw uranium extraction present persistent operational challenges for processors.
Emerging Industry Trends and Evolution
The shift toward advanced Small Modular Reactors (SMRs) is transforming consumption patterns, increasing demand for High-Assay Low-Enriched Uranium (HALEU). Operators are optimizing fuel cycles to improve thermal efficiency across both commercial power plants and specialized research facilities.
COVID-19 Impact and Recovery Trajectory
Pandemic-induced labor shortages and border restrictions temporarily disrupted uranium mining operations in Kazakhstan and Canada. However, long-term contracting stability and government-backed energy security initiatives accelerated the sector's robust recovery, insulating baseline revenues.
Competitive Benchmarking and Market Concentration
The industry features high market concentration led by state-backed entities and diversified conglomerates. JSC National Atomic Company Kazatomprom and Cameco Corporation dominate raw supply, while technology leaders like Framatome and Westinghouse control advanced fuel fabrication.
Executive Summary of Key Findings
Synthesizing our proprietary research, the Nuclear Fuel Market analysis reveals a steady projected expansion reaching 53.20 Billion by 2033. Strategic investments in enrichment capacity and reprocessing technologies are critical for capturing high-margin opportunities amid shifting geopolitical alliances.
Market Forecast and Long-Term Projections
Our forecasting models project the market to expand at a steady CAGR of 4.59% from 2027 to 2033. This growth trajectory reflects accelerated reactor life extensions and new builds in emerging economies prioritizing energy independence and carbon reduction.
Comprehensive Segmentation Analysis
Segmentation is categorized by type, application, and end-use industry. Key type classifications include Mixed Oxide (MOX) Fuel, Uranium Fuel, and other specialized variants. Applications span Nuclear Power Plants and Nuclear Research Labs, catering to diverse energy and scientific requirements.
Regional Market Distribution and Performance
Geographic performance varies significantly, with Asia-Pacific leading new reactor deployment rates, particularly in China and India. North America and Europe maintain stable demand driven by fleet modernization, regulatory compliance, and long-term utility procurement strategies.
In-Depth Regional Review of Key Markets
North America relies heavily on domestic enrichment initiatives supported by the Department of Energy, while Eastern Europe maintains strong operational ties with Russian fuel fabricators. Meanwhile, Asian markets are scaling up indigenous fuel fabrication capabilities to secure long-term energy autonomy.
Strategic Company Profiles
Industry participants exhibit diverse strategic positioning. Rosatom State Nuclear Energy Corporation and Orano SA leverage integrated supply chains from mining to reprocessing, whereas specialized innovators like Centrus Energy focus on pioneering domestic HALEU enrichment technologies.
Porter's Five Forces Analysis
Supplier power remains moderate-to-high due to uranium mining oligopolies, while buyer power is constrained by specialized reactor specifications. The threat of substitutes is remarkably low given the unique physics of nuclear fission, though regulatory barriers severely restrict new market entry.
SWOT Analysis of the Sector
Strengths include high energy density and zero operational carbon emissions. Weaknesses center on radioactive waste management liabilities and geopolitical supply risks. Opportunities lie in SMR commercialization, while threats involve public perception shifts and regulatory policy reversals.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from uranium mining and milling, through chemical conversion and isotopic enrichment, to pellet fabrication and assembly. Value capture is highest during the capital-intensive enrichment and fabrication stages handled by firms like Urenco and Global Nuclear Fuel Co Ltd.
Investment Insights and High-Potential Areas
High-potential investment areas include advanced enrichment infrastructure for HALEU and closed-fuel-cycle reprocessing technologies. Strategic partnerships with state-backed utilities offer the most reliable pathway for mitigating supply chain volatility and securing long-term offtake agreements.
Conclusion and Strategic Takeaways
The Nuclear Fuel Market industry trends underscore a resilient sector poised for steady expansion through 2033. Stakeholders must proactively adapt to evolving geopolitical frameworks and embrace advanced fuel technologies to maintain competitive advantage.
Research Methodology and Data Triangulation
Baseline estimates are triangulated using a rigorous methodology combining trade registry data, primary stakeholder interviews with C-suite nuclear executives, and secondary macroeconomic indicators. This multi-tiered approach ensures robust, unbiased market sizing and validation.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for the Nuclear Fuel Market across key regions, detailing segmentation by type, application, and end-use. Limitations include unpredictable geopolitical trade policy shifts and confidential state-level nuclear reserve disclosures.
Recent Industry Developments and Strategic Moves
Recent developments feature major infrastructure investments in domestic enrichment by companies like Centrus Energy and strategic international supply agreements forged by Cameco Corporation. These moves reflect a concerted industry-wide effort to decouple supply chains from geopolitical flashpoints.