What is the scope and industry significance of the Laboratory Glassware And Plasticware Market?
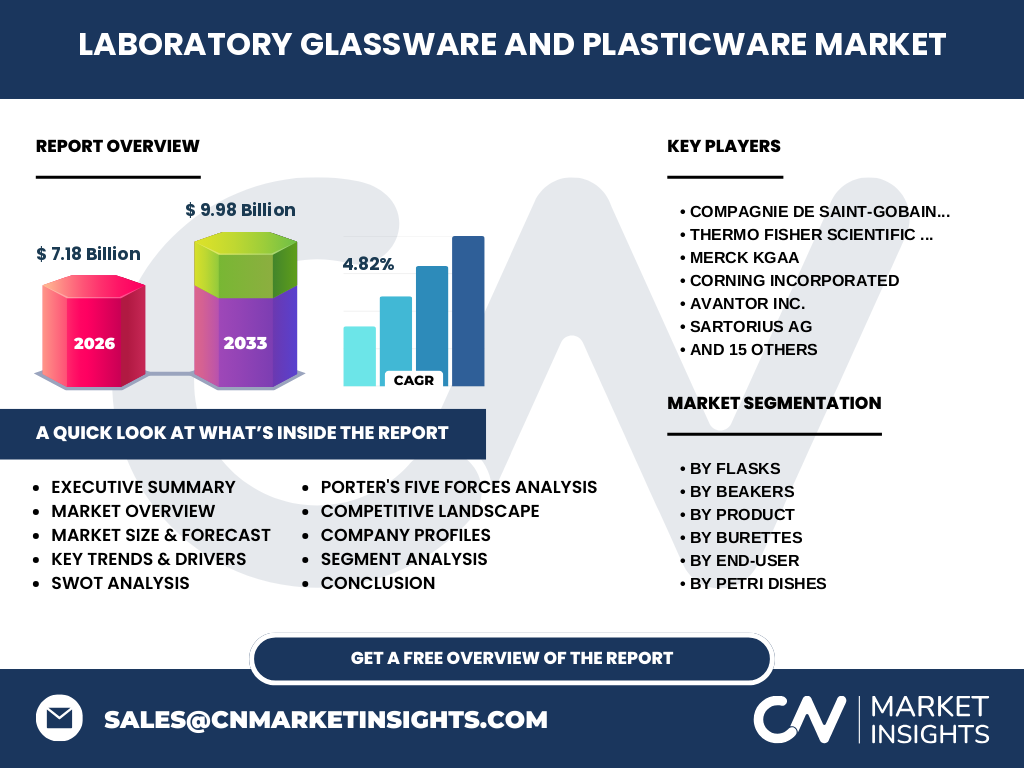
The Laboratory Glassware And Plasticware Market is valued at $7.18 Billion in 2026, forming the foundational infrastructure for life sciences, chemical synthesis, and clinical diagnostics. Our analysis indicates that premium borosilicate glass and high-purity polymers like polypropylene are essential for maintaining sample integrity under rigorous thermal and chemical sterilization protocols governed by ISO standards.
Key market drivers, restraints, challenges, and opportunities shaping Laboratory Glassware And Plasticware Market
Growth is propelled by surging R&D investments in biopharmaceuticals and molecular biology. However, supply chain volatility regarding polymer resins and stringent FDA compliance present operational challenges. Opportunities lie in developing eco-friendly, recyclable consumables and advanced single-use plasticware for high-throughput screening applications.
Emerging trends and growth patterns in Laboratory Glassware And Plasticware Market
The industry is witnessing a definitive pivot toward automation-compatible consumables, such as specialized micropipettes and pipette tips designed for robotic liquid handlers. Laboratories increasingly demand sterile, certified DNase/RNase-free plasticware to eliminate cross-contamination risks during genomic sequencing and high-throughput drug discovery assays.
COVID-19 impact analysis and recovery trajectory for Laboratory Glassware And Plasticware Market
The pandemic triggered an unprecedented surge in demand for diagnostic consumables like Petri dishes, storage containers, and test tubes. While supply chains faced severe bottlenecks, the post-pandemic recovery trajectory has stabilized, supported by sustained governmental funding for pandemic preparedness and expanded clinical testing infrastructure globally.
Competitive landscape, major players, and strategic dynamics
The market exhibits a consolidated structure dominated by global giants such as Thermo Fisher Scientific Inc., Corning Incorporated, and Merck KGaA. These industry leaders leverage extensive distribution networks and strategic acquisitions to capture market share, while regional players like Borosil Ltd. and Tarsons Products Limited compete through cost-effective localized manufacturing.
Executive summary of the Laboratory Glassware And Plasticware Market
Our comprehensive research projects the Laboratory Glassware And Plasticware Market to expand from $7.18 Billion in 2026 to $9.98 Billion by 2033, achieving a steady CAGR of 4.82%. This upward trajectory is anchored by robust biopharmaceutical pipelines, stringent quality control mandates, and continuous technological upgrades in laboratory automation.
Market forecast from 2027 to 2033
Driven by compounding investments in clinical research and biotechnology, the market is set to achieve a 4.82% CAGR, pushing total valuation to $9.98 Billion by 2033. This projection reflects sustained multi-sector demand across emerging economies and advanced research clusters in North America and Europe.
Segmentation analysis across product lines and end-users
The market encompasses diverse categories including flasks (Erlenmeyer, volumetric), beakers (low-form, tall-form), burettes, pipettes and pipette tips, petri dishes, and storage containers. End-users span pharmaceutical firms, contract research organizations (CROs), hospitals, and academic institutes, each requiring tailored material properties.
Regional market analysis and geographic distribution performance
Geographic performance is led by North America and Europe, fueled by concentrated biotech hubs and stringent regulatory frameworks. Meanwhile, the Asia-Pacific region demonstrates the fastest growth trajectory, driven by expanding clinical trial outsourcing and rising healthcare expenditures in emerging economies.
In-depth regional review of key operational markets
North America maintains market dominance due to robust venture capital funding in life sciences and established laboratory infrastructure. In contrast, APAC regional growth is accelerated by governmental incentives promoting local pharmaceutical manufacturing and clinical research capabilities in countries like India and China.
Company profiles and strategic positioning of leading enterprises
Industry leaders like Eppendorf SE and Sartorius AG focus on high-precision liquid handling solutions. Meanwhile, DWK Life Sciences Ltd. and Schott AG anchor their positioning in premium laboratory glassware innovation, catering to rigorous analytical chemistry and pharmaceutical packaging applications.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate due to high switching costs associated with validated laboratory protocols. Threat of new entrants remains low, hindered by stringent regulatory approvals, high capital expenditure for precision molds, and entrenched distribution networks of established incumbents like Avantor Inc. and Corning Incorporated.
SWOT analysis of the Laboratory Glassware And Plasticware sector
Key strengths include high product durability and essential utility across scientific workflows. Weaknesses involve vulnerability to raw material price fluctuations. Opportunities emerge in sustainable biopolymer innovations, while threats stem from geopolitical supply chain disruptions and stringent environmental regulations on single-use plastics.
Value chain analysis from raw materials to end-users
The value chain initiates with petrochemical refiners and silica quartz suppliers providing raw resins and borosilicate tubes. Mid-stream manufacturers utilize precision injection molding and thermal blow-forming. The downstream channel relies on specialized distributors supplying contract research laboratories and academic institutions.
Investment insights and strategic high-potential growth areas
Investors should target manufacturers specializing in automation-ready consumables, sterile single-use systems, and sustainable bioplastics. Companies integrating digital traceability, such as RFID-tagged reagent bottles and storage flasks, represent high-margin opportunities for venture capital and strategic deployment.
Conclusion and key takeaways for stakeholders
The Laboratory Glassware And Plasticware Market presents a compelling growth narrative, scaling toward $9.98 Billion by 2033. Success in this sector hinges on navigating supply chain resilience, embracing green polymer alternatives, and aligning product portfolios with high-throughput laboratory automation trends.
Research methodology and baseline estimation triangulation
Our baseline estimates are derived through rigorous triangulation, combining global trade registry data, primary qualitative interviews with C-level executives at firms like Metrohm AG and Gerresheimer AG, and secondary macroeconomic indicators to ensure high data fidelity and market accuracy.
Scope of the report, coverage parameters, and limitations
This report covers global revenue performance for glassware and plasticware across specified product segments and end-user verticals from 2026 to 2033. Limitations include unforeseen macroeconomic shifts, geopolitical trade tariffs, and localized regulatory policy changes impacting polymer supply chains.
Recent developments, corporate announcements, and strategic moves
Recent industry momentum highlights strategic expansions by players like Greiner Bio-One International GmbH and Tarsons Products Limited, focusing on sustainable manufacturing lines and expanding production capacity for automated liquid handling accessories to meet surging biopharmaceutical demand.