What is the scope and industry significance of the Warehouse Data Lake Platforms Market?
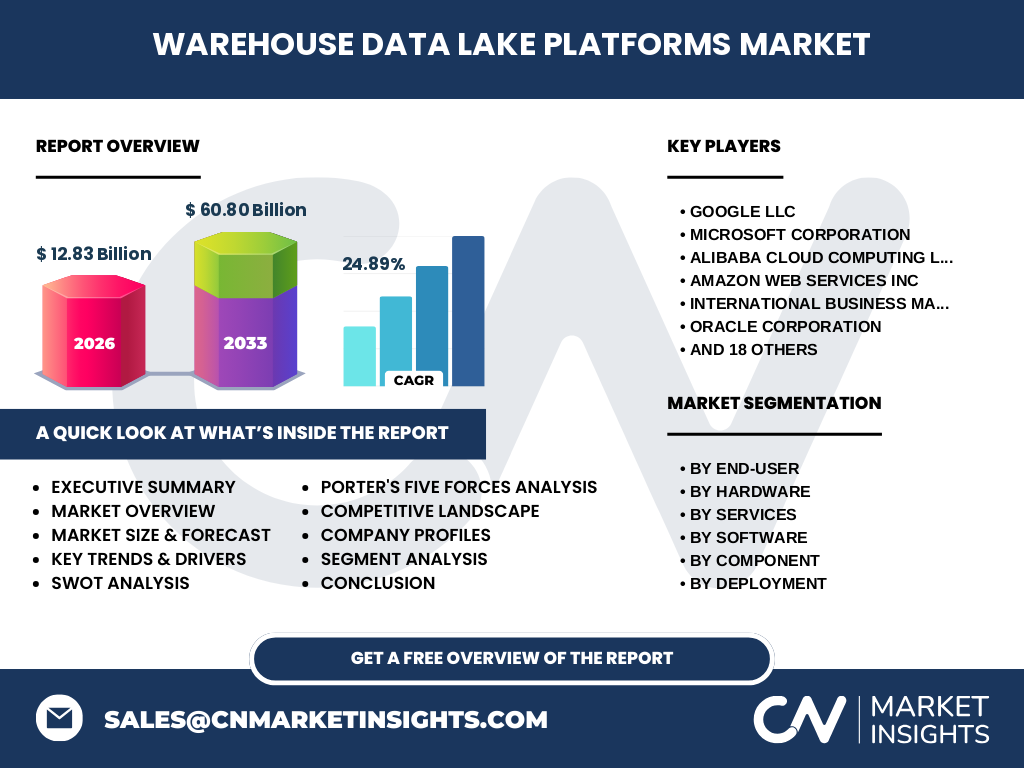
Our analysis indicates that the Warehouse Data Lake Platforms Market represents a vital convergence of scalable storage and high-performance querying. Valued at $12.83 Billion in 2026, this sector underpins modern enterprise data infrastructure. It bridges unstructured analytics and structured transactional reporting under strict regulatory frameworks like GDPR and HIPAA.
Structural Growth Drivers and Market Constraints
The market is propelled by exponential data generation across Retail and E-commerce and BFSI sectors. However, strict data residency laws and complex multi-cloud integration hurdles act as notable restraints. Enterprises must balance cost optimization in Storage Systems with low-latency access requirements.
Emerging Trends Reshaping Data Architectures
The shift toward lakehouse paradigms is revolutionizing how organizations utilize Data Integration Software and Analytics and Reporting Software. Cloud-Based and Hybrid deployments dominate as firms demand real-time streaming capabilities to feed high-performance machine learning models without egress bottlenecks.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic accelerated digital transformation initiatives, forcing distributed workforces to rely heavily on scalable Cloud-Based infrastructure. Post-pandemic recovery has institutionalized decentralized data governance, driving persistent demand for Data Migration Services and resilient Data Center Servers.
Competitive Benchmarking and Market Concentration
The landscape features intense rivalry among hyperscalers like Amazon Web Services Inc, Microsoft Corporation, and Google LLC, alongside specialized innovators like Snowflake Inc and Databricks Inc. Market concentration is high in cloud infrastructure, while open-source formats drive disruption at the query engine layer.
Executive Summary of the Warehouse Data Lake Platforms Market
Our comprehensive research projects the Warehouse Data Lake Platforms Market to surge from $12.83 Billion in 2026 to $60.80 Billion by 2033, expanding at a remarkable 24.89% CAGR. Convergence of lake and warehouse technologies is unlocking unprecedented value for Large Enterprises and agile SMEs alike.
Long-Term Market Forecast from 2027 to 2033
Driven by compounding data volumes and AI adoption, the market is poised for hyper-growth, rocketing from its 2026 baseline to $60.80 Billion by 2033 at a 24.89% CAGR. Consulting Services and Monitoring and Optimization Services will capture significant advisory spend during this expansion window.
Segmentation Analysis Across Components and Deployments
Segmentation spans Software, Services, and Hardware, with software leading via Data Integration Software and Security and Compliance Software. Deployment strategies are split between Cloud-Based, On-Premises, and Hybrid models, addressing diverse latency and compliance requirements in Healthcare and Manufacturing.
Geographic Distribution and Regional Performance
Regional adoption varies significantly based on local data sovereignty mandates and cloud infrastructure maturity. North America leads in enterprise adoption, while Europe prioritizes rigorous compliance via Security and Compliance Software. Asia-Pacific demonstrates the fastest growth due to expanding Information Technology (IT) And Telecommunications sectors.
In-Depth Regional Review of High-Growth Zones
North America anchors global demand, leveraging advanced High Performance Computing Devices and enterprise cloud spending. Meanwhile, APAC markets in Southeast Asia and parts of Latin America are leapfrogging legacy architectures directly into Cloud-Based data lake platforms to support mobile-first consumer economies.
Strategic Positioning of Leading Industry Participants
Industry leaders deploy distinct strategies: Oracle Corporation and SAP SE integrate data lakes tightly with enterprise resource planning systems, while Snowflake Inc and Databricks Inc focus on decoupled storage-compute models. Innovators like Starburst Data Inc and Dremio Corporation specialize in federated query execution.
Porter's Five Forces Competitive Intensity Assessment
Rivalry is fierce among dominant cloud providers and specialized SaaS vendors, keeping competitive rivalry high. Supplier power is moderate due to standardized hardware like Storage Systems, whereas buyer power is substantial as enterprises demand interoperability across Data Integration And Management tools.
SWOT Analysis of the Data Lake Platforms Sector
Key strengths include infinite scalability and unified analytics. Weaknesses involve complex data governance overhead. Opportunities abound in generative AI integration, while threats stem from evolving global cybersecurity regulations and vendor lock-in concerns associated with proprietary formats.
Value Chain Analysis and Industry Structure
The value chain flows from foundational Networking Infrastructure and Data Center Servers to specialized software like Workflow Automation Software and Storage Management Software. System integrators and consultants capture high margins by bridging raw infrastructure with executive Business Intelligence And Analytics dashboards.
Investment Insights and High-Potential Opportunity Areas
Investors should target niche players offering automated governance, real-time streaming ingestion, and cross-cloud interoperability. Small And Medium Enterprises (SME) segments represent an underpenetrated high-growth frontier for turnkey, managed SaaS analytics platforms.
Conclusion and Strategic Takeaways
The evolution toward unified data architecture is irreversible. Reaching $60.80 Billion by 2033 underscores the permanent shift toward data-driven operations. Organizations failing to modernize their storage and analytics stacks risk severe competitive disadvantage in an AI-dominated landscape.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining primary executive interviews with CTOs, secondary macroeconomic indicators, regulatory filings from key players like International Business Machines Corporation and Teradata Corporation, and proprietary trade registry data across major global technology hubs.
Scope of the Report and Analytical Limitations
This report covers global revenue streams from 2026 to 2033 across hardware, software, services, and deployment models. Limitations include unforeseen macroeconomic volatility, rapid shifts in open-source licensing models, and localized regulatory updates affecting cross-border data flows.
Recent Developments and Ecosystem Dynamics
Recent strategic maneuvers include aggressive multi-cloud partnerships by Alibaba Cloud Computing Ltd, product launches from ClickHouse Inc and MinIO Inc focusing on ultra-fast querying, and acquisitions by firms like Fivetran Inc aimed at streamlining automated data pipelining.