What is the market overview and scope of the Metal Working Market?
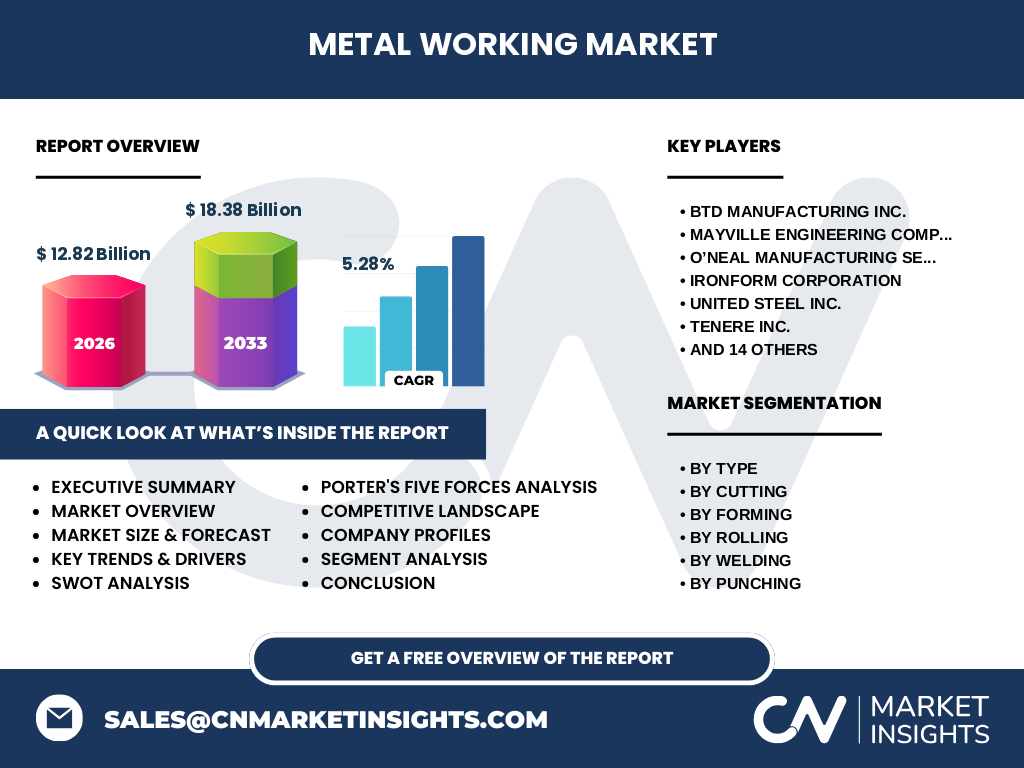
Our analysis indicates that the Metal Working Market commands a substantial valuation of 12.82 Billion in 2026. Encompassing foundational processes like cutting, forming, and welding raw industrial materials, this sector forms the backbone of global manufacturing infrastructure, supplying critical components to energy, construction, and logistics operations worldwide.
What are the core market drivers, restraints, challenges, and opportunities shaping the Metal Working Market?
The market is propelled by robust infrastructure spending across emerging economies, though constrained by volatile raw material costs and stringent OSHA and EPA environmental mandates. Strategic opportunities emerge through automation integration and advanced laser cutting innovations, which significantly lower operational overhead for tier-1 suppliers.
Structural Growth Drivers and Emerging Trends in the Metal Working Market
The industry is witnessing an aggressive shift toward smart manufacturing and digital fabrication workflows. Companies adopting CNC punching and robotic MIG and TIG welding are capturing higher margins, driven by rising demand for lightweight architectural aluminum fabrication and pre-engineered buildings.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
The pandemic severely disrupted supply chains for critical inputs like structural steel, inducing widespread facility shutdowns across major ports and manufacturing hubs. However, the post-pandemic recovery trajectory has been robust, fueled by aggressive fiscal stimulus directed at infrastructure modernization and energy grid expansions.
Competitive Benchmarking and Market Concentration in the Metal Working Market
Market concentration remains moderately fragmented, featuring a mix of specialized regional fabricators and diversified multinational giants. Leading players leverage proprietary progressive die stamping and advanced robotic automation to secure dominant positions against smaller, localized machine shops.
Executive Summary of the Metal Working Market
Our research projects the Metal Working Market to expand from 12.82 Billion in 2026 to reach 18.38 Billion by 2033, registering a solid CAGR of 5.28%. This expansion is anchored by relentless demand for precision machining and structural steel fabrication across energy and utilities.
Market Forecast Projections from 2027 to 2033
Driven by compounding industrialization and technological integration, the sector will maintain a steady 5.28% CAGR through the forecast period. Total market value is anticipated to scale from 12.82 Billion up to 18.38 Billion by 2033, rewarding firms heavily invested in hot and cold rolling technologies.
Segmentation Analysis by Type, Cutting, Forming, and Application
The market segments by type into cutting, forming, welding, stamping, punching, and rolling, with distinct sub-segments like laser cutting and progressive die stamping. Applications span oil and gas, mining, and building construction, where structural steel fabrication and pre-fabricated buildings dominate structural demand.
Geographic Distribution and Regional Market Performance
Regional performance varies significantly, with North America and Asia-Pacific leading consumption due to intensive urban development and heavy equipment manufacturing. Logistical proximity to major shipping ports remains a critical determinant of regional supply chain efficiency and margin retention.
In-Depth Regional Review of the Metal Working Market
North America exhibits high demand for advanced CNC and turret punching machinery, supported by stringent quality standards from the American Institute of Steel Construction. Meanwhile, Asia-Pacific remains a high-volume manufacturing powerhouse driven by rapid industrialization and lower operational labor costs.
Company Profiles and Strategic Positioning of Leading Participants
Industry stalwarts like Mayville Engineering Company Inc., BTD Manufacturing Inc., and Valmont Industries Inc. differentiate themselves through advanced robotic welding and end-to-end fabrication capabilities. Firms such as O’Neal Manufacturing Services leverage expansive regional footprints to optimize supply chain delivery for heavy machinery original equipment manufacturers.
Porter's Five Forces Analysis of the Metal Working Sector
Bargaining power of suppliers is moderate-to-high due to fluctuating steel and aluminum pricing, while competitive rivalry is fierce among established tier-1 fabricators. Threat of substitutes remains low given the irreplaceable structural integrity provided by precision metal forming and welding.
SWOT Analysis of the Metal Working Industry Landscape
Strengths include deeply entrenched client relationships and sophisticated fabrication technologies; weaknesses involve high initial capital expenditure for machinery. Opportunities lie in renewable energy infrastructure components, while threats include skilled labor shortages and geopolitical trade tariffs on raw metals.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with primary metal producers supplying raw coils and plates, flowing through intermediate processors performing laser cutting, stamping, and welding. Final value capture occurs through specialized structural steel fabrication and custom assembly for end-users in energy, mining, and industrial logistics.
Investment Insights and High-Potential Areas for Stakeholders
High-potential capital allocation centers on automated waterjet cutting, fiber laser technology, and specialized pre-engineered building components. Investors should target companies demonstrating advanced digital integration, which insulate margins against inflationary labor and raw material pressures.
Conclusion and Strategic Takeaways for Industry Leaders
The Metal Working Market offers compelling growth, advancing toward 18.38 Billion by 2033 at a 5.28% CAGR. Success requires pivoting toward high-precision automation, sustainable fabrication practices, and robust supply chain diversification to navigate macroeconomic headwinds effectively.
Research Methodology and Baseline Estimate Triangulation
Our proprietary research methodology triangulates data by combining exhaustive primary stakeholder interviews with executives at firms like The Bradbury Co. Inc. and Ironform Corporation. This primary input is cross-verified against global trade registry statistics, customs import-export logs, and secondary macroeconomic industrial indices.
Scope of the Report, Parameters, and Analytical Limitations
This report covers global market sizing, segmental revenue breakdowns, and competitive landscape assessments from 2026 to 2033. Limitations include unforeseen macroeconomic policy shifts, sudden trade tariff alterations, and localized supply chain disruptions that could momentarily skew regional production forecasts.
Recent Developments, Strategic Partnerships, and Corporate Announcements
Recent industry momentum is characterized by strategic facility expansions and technological acquisitions among top players. Companies like Tenere Inc. and Robinson Metal Inc. have actively invested in advanced automated stamping cells to enhance production throughput for automotive and industrial logistics sectors.