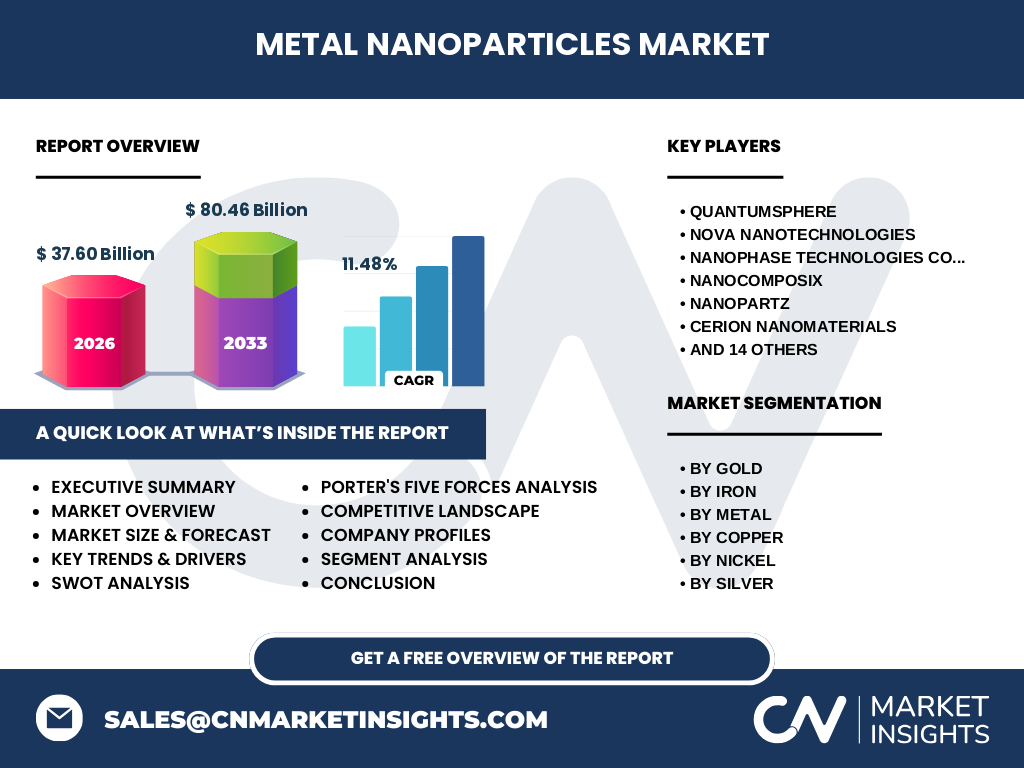
Market overview of the Metal Nanoparticles Market
Our analysis indicates the Metal Nanoparticles Market is valued at 37.60 Billion in 2026. This foundational sector encompasses ultra-fine structures of noble and transition metals like gold, silver, and platinum, driving transformative innovations across pharmaceuticals, electronics, and advanced catalysts by exploiting quantum size effects and high surface-area-to-volume ratios.
Structural Growth Drivers and Market Restraints
Growth is propelled by miniaturization demands in electronics and targeted drug delivery breakthroughs. However, the market faces strict toxicological evaluations by agencies like the EPA and complex handling hazards for reactive elements such as copper and iron nanopowders, constraining rapid commercial deployment.
The Shift Toward Green Synthesis and Emerging Trends
Industry participants are rapidly pivoting from hazardous chemical methods toward bio-based synthesis utilizing plant extracts and microbial agents. This sustainable shift mitigates environmental toxicity concerns while lowering production overheads for key players like nanoComposix and Cerion Nanomaterials.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted global supply chains, halting high-purity precursor shipments through major logistics hubs. Recovery has been robustly accelerated by heightened healthcare investments, driving explosive demand for silver and gold formulations in diagnostic assays and antimicrobial surface coatings.
Competitive Benchmarking and Strategic Dynamics
The market features intense competition among specialized innovators like QuantumSphere, Nanophase Technologies, and Skyspring Nanomaterials. Industry leaders differentiate through proprietary colloidal stabilization techniques and vertically integrated manufacturing tailored for high-purity end-use applications.
Executive Summary of the Metal Nanoparticles Market
Our research underscores a thriving economic landscape, projecting the Metal Nanoparticles Market to expand from 37.60 Billion in 2026 to 80.46 Billion by 2033 at a CAGR of 11.48%, driven by pervasive adoption across electronics and healthcare.
Market Forecast Projections from 2027 to 2033
Based on our econometric modeling, the market will achieve remarkable expansion, surging to 80.46 Billion by 2033. This trajectory reflects a sustained 11.48% CAGR, underpinned by surging commercial scaling of titanium dioxide and platinum alloy catalysts.
Segmentation Analysis of the Metal Nanoparticles Market
Segmentation spans raw metals including gold, silver, copper, nickel, platinum, iron, and titanium, alongside functional groups like metal oxides. End-use verticals are categorized into pharmaceutical and healthcare, electrical and electronics, catalysts, and personal care, each exhibiting distinct adoption velocities.
Geographic Distribution and Regional Market Analysis
Geographic performance highlights North America and Asia-Pacific as primary revenue generators. North America leads in biopharmaceutical R&D expenditure, while Asia-Pacific dominates manufacturing output due to robust electronics fabrication hubs in South Korea, Japan, and Taiwan.
In-Depth Regional Review and Localized Constraints
APAC regional momentum is anchored by aggressive government funding for nanotechnology initiatives. Conversely, stringent European chemical regulations under REACH impose rigorous compliance burdens on importers of nanoparticulate powders, shaping localized market entry strategies.
Company Profiles and Market Positioning
Key innovators such as Tanaka Holdings, Plasmachem GmbH, and US Research Nanomaterials leverage specialized synthesis routes. Their strategic focus centers on custom alloy fabrication and scaling colloidal dispersions for tier-one electronics and pharmaceutical clients.
Porter's Five Forces Analysis
Rivalry is intense among established specialty synthesis providers, though high intellectual property barriers and specialized precursor requirements moderate threat of new entrants. Bargaining power of buyers remains moderate due to the critical, high-performance nature of nanoparticle inputs.
SWOT Analysis of the Metal Nanoparticles Industry
Strengths lie in exceptional catalytic and optical properties. Weaknesses involve particle agglomeration risks. Opportunities abound in printed electronics and cancer therapeutics, while threats stem from evolving regulatory frameworks concerning nanoparticle occupational exposure limits.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with high-purity metal refiners supplying raw bullion and salts, progressing through specialized chemical, physical, or bio-based synthesis houses, and culminating in tier-one component manufacturers and pharmaceutical formulators.
Investment Insights and High-Potential Areas
Investors should target green synthesis technology startups and scalable precious metal alloy producers. High-potential pockets include silver composite antimicrobials and platinum group catalysts destined for hydrogen fuel cell infrastructure.
Conclusion and Key Takeaways
The Metal Nanoparticles Market represents a high-growth technological frontier. Reaching 80.46 Billion by 2033, success in this sector hinges on mastering scalable, eco-friendly synthesis and rigorous regulatory compliance across global supply chains.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by synthesizing customs trade registries, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators regarding global electronics and healthcare expenditure.
Scope of the Report and Coverage Parameters
This report evaluates the global Metal Nanoparticles Market across defined material types, synthesis routes, and regional jurisdictions from 2026 through 2033, explicitly excluding macroscopic metal powders and non-metallic nanomaterials.
Recent Developments and Strategic Industry Moves
Recent industry momentum features strategic joint ventures focused on scaling titanium and gold nanoparticle production lines. Companies like nanoComposix and Inframat Advanced Materials have expanded manufacturing footprints to secure supply resilience amid rising semiconductor sector demand.