What is the market overview, definition, scope, and industry significance of Nanosilica Market?
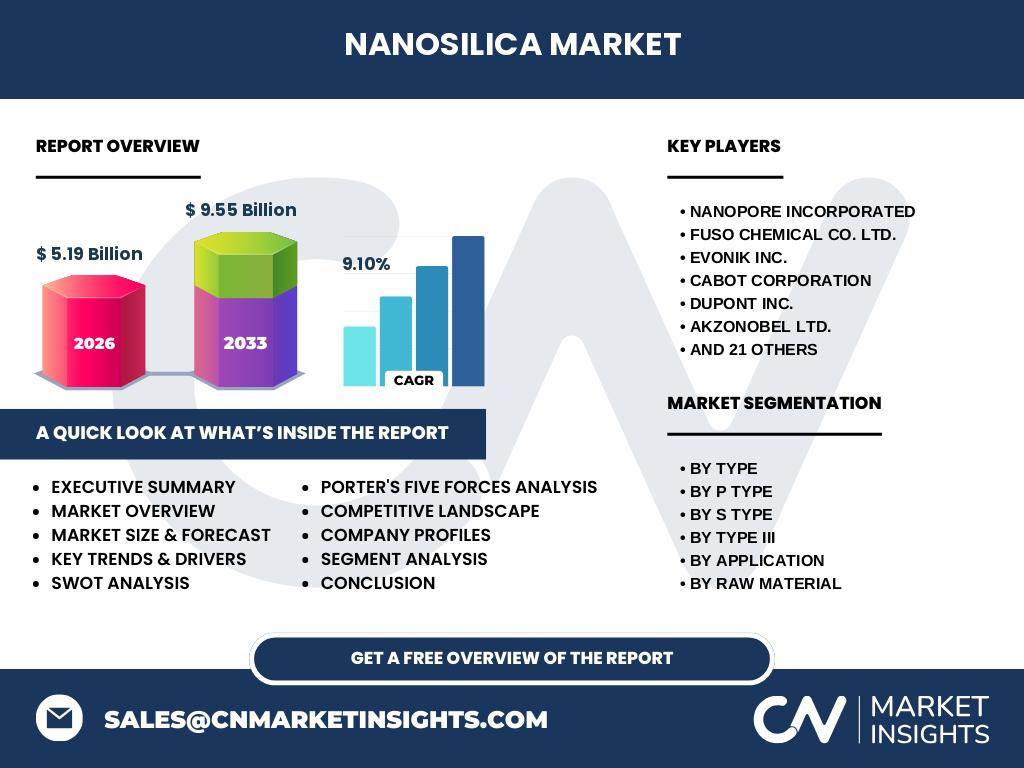
Our analysis indicates the Nanosilica Market represents a critical frontier in advanced nanomaterials, valued at 5.19 Billion in 2026. This sector encompasses high-purity silicon dioxide nanoparticles utilized across elastomeric reinforcement, high-performance concrete, and precision electronics. Regulatory compliance by bodies such as the EPA and REACH governs its deployment, making purity and particle size distribution paramount for industrial success.
Key market drivers, restraints, challenges, and opportunities shaping Nanosilica Market
Structural growth is propelled by demand for lightweight composites and ultra-high-performance concrete. However, strict inhalation toxicity regulations and handling hazards act as primary restraints. Industry participants like Evonik Inc. and Cabot Corporation are capitalizing on opportunities in green tire technologies, offsetting supply chain bottlenecks associated with agricultural raw material sourcing.
The Shift Toward Bio-Based Synthesis: Emerging trends and growth patterns in Nanosilica Market
Market evolution is heavily dictated by a pivot toward sustainable precursors. Innovators are increasingly extracting silica from agricultural residues like rice husk and bagasse rather than traditional quartz mining. This shift reduces carbon footprints while meeting stringent ESG mandates demanded by automotive and electronics conglomerates globally.
COVID-19 impact analysis — how the pandemic affected Nanosilica Market and the recovery trajectory
The pandemic severely disrupted supply chains and delayed construction projects worldwide, dampening near-term consumption in concrete and coatings. Yet, the recovery trajectory has been exceptionally robust, driven by accelerated adoption of antimicrobial medical coatings and semiconductor manufacturing, propelling the sector toward a 9.10% CAGR.
Competitive Benchmarking: major players, market concentration, and strategic dynamics
The Nanosilica Market exhibits a moderately consolidated landscape dominated by chemical heavyweights such as Wacker Chemie AG and DuPont Inc. Alongside specialized nano-pure firms like US Research Nanomaterials Inc., competitive advantage hinges on proprietary surface-modification techniques and backward integration into low-cost agricultural raw material supply chains.
Executive summary — high-level synthesis of key findings about Nanosilica Market
Our comprehensive Nanosilica Market analysis reveals a dynamic valuation trajectory surging from 5.19 Billion in 2026 to 9.55 Billion by 2033. Driven by a robust 9.10% CAGR, stakeholders must navigate stringent particle safety regulations while leveraging bio-derived precursors to capture high-margin opportunities in electronics and green elastomers.
Market forecast — projected growth from 2027 to 2033
The data suggests the Nanosilica Market will expand aggressively through the forecast window, reaching 9.55 Billion by 2033 at a steady 9.10% CAGR. This expansion is underpinned by escalating industrial automation, rising semiconductor fabrication demands across East Asian foundries, and infrastructure upgrades requiring enhanced durability concrete admixtures.
Segmentation analysis — break down each segment category, explain what it covers and its market role
The market segments by Type (P Type, S Type, Type III), Application (Rubber, Health and Medicine, Food, Coatings, Plastic, Concrete, Gypsum, Cosmetics, Electronics, Other), and Raw Material (Rice Husk, Olivine, Bagasse, Other). Pyrogenic Silica and Precipitated Silica dominate the P Type category, serving critical rheology-control functions in sealants and adhesives.
Regional market analysis — geographic distribution and performance across regions
Geographically, Asia-Pacific commands the lion's share of the Nanosilica Market, propelled by extensive tire manufacturing hubs in China, Japan, and India. Meanwhile, North America and Europe focus heavily on high-end medical applications and aerospace coatings, constrained by rigorous workplace safety protocols enforced by OSHA and the European Chemicals Agency.
In-depth regional review — detailed examination of key regional markets
Within Asia-Pacific, nations like Japan—anchored by firms such as Fuso Chemical Co. Ltd.—lead in colloidal silica for semiconductor chemical mechanical planarization (CMP). Conversely, North American growth is anchored by specialized R&D initiatives in nano-composites, though regional manufacturing faces headwinds from strict environmental permitting requirements.
Company profiles — strategic positioning of leading companies in Nanosilica Market
Industry leaders maintain distinct competitive moats. NanoPore Incorporated focuses on thermal insulation nanopores, whereas Akzonobel Ltd. integrates advanced silica into protective marine coatings. Firms like Nanostructured & Amorphous Materials Inc. target academic and industrial R&D laboratories requiring ultra-high purity grades.
Porter's Five Forces analysis — competitive forces assessment
Our analysis indicates moderate-to-high threat of new entrants due to high capital expenditure requirements for nanoscale synthesis facilities. Bargaining power of suppliers is moderate, heavily influenced by agricultural waste availability, while rivalry among established giants like Cabot Corporation and Evonik Inc. remains intense.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Key strengths lie in superior reinforcement and thermal properties. Weaknesses involve high production costs and agglomeration risks during storage. Opportunities abound in biodegradable plastic additives and 5G electronic substrates. Threats include stringent nanoparticle toxicity reviews by regulatory bodies and potential substitution by carbon nanotubes.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with agricultural and mineral raw material extraction (rice husk, olivine), progressing through energy-intensive synthesis methods like pyrolysis or precipitation. Intermediate processing involves surface-modification by specialists before final distribution to tire manufacturers, concrete formulators, and pharmaceutical companies via complex logistics networks.
Investment insights — strategic recommendations and high-potential areas
Investors should direct capital toward bio-derived silica synthesis start-ups and surface-modified grades tailored for electric vehicle lightweighting. Partnerships with established players like Wacker Chemie AG offer pathways to commercial scale, mitigating risks associated with regulatory compliance and capital expenditure outlays.
Conclusion and key takeaways
The Nanosilica Market industry trends highlight an undeniable pivot toward sustainability and high-value electronic integration. With a market size of 5.19 Billion in 2026 expanding to 9.55 Billion by 2033, proactive R&D investments in bio-based precursors will dictate long-term leadership in this rapidly evolving nanomaterials landscape.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data, customs import-export logs for chemical shipments, primary stakeholder interviews with c-suite executives at Nanoshel LLC and Nyacol Nano Technologies Inc., and secondary macroeconomic indicators regarding automotive and construction output.
Scope of the report — coverage parameters and limitations
This report covers global Nanosilica Market dynamics across North America, Europe, Asia-Pacific, and Rest of World, spanning historical data through 2026 and forecasts up to 2033. Limitations include restricted transparency on proprietary pilot-plant capacities in emerging economies and unlisted private synthesis ventures.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent strategic moves feature aggressive capacity expansions by market leaders to meet surging semiconductor and green tire demands. For instance, collaborative R&D agreements between specialty chemical producers and academic institutions have accelerated the commercialization of surface-modified silica grades designed for advanced battery separators.