Market overview and structural significance of the Middleoffice Business Process Outsourcing (BPO) Service Market
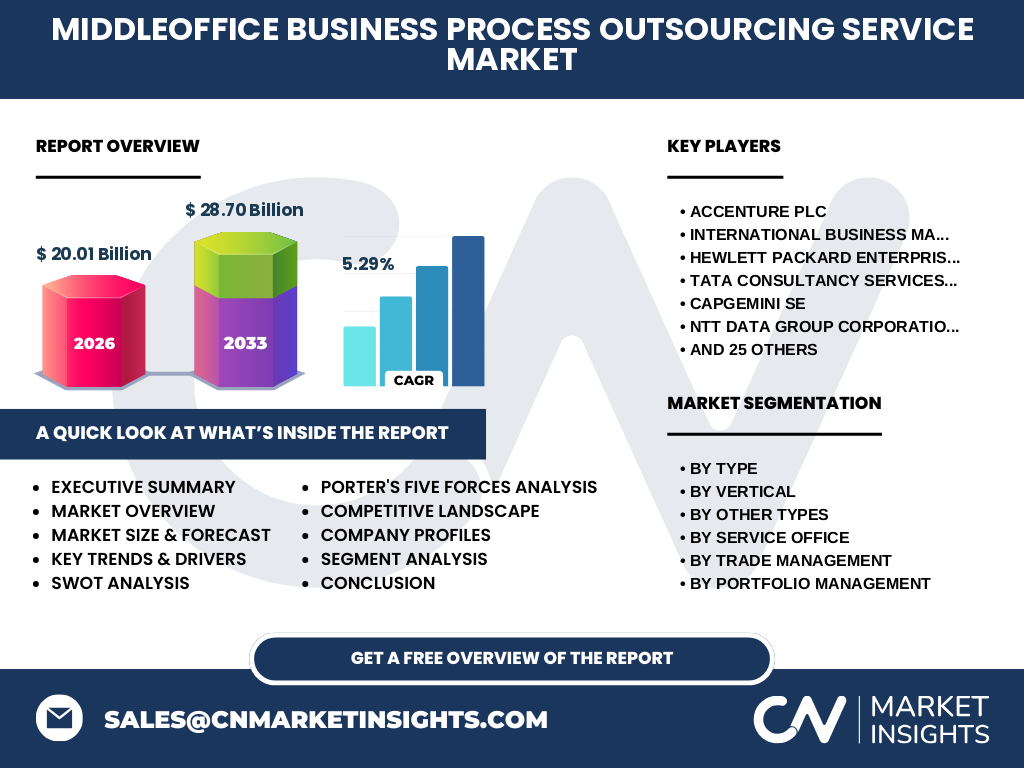
Our analysis indicates that the Middleoffice Business Process Outsourcing (BPO) Service Market represents a critical operational layer for financial institutions navigating complex regulatory mandates from bodies like the SEC and FCA. Valued at $20.01 Billion in 2026, this sector encompasses essential functions including trade confirmation, risk management, and fund administration, enabling firms to reduce overhead and mitigate operational risk through specialized third-party providers.
What key market drivers, restraints, challenges, and opportunities shape the Middleoffice Business Process Outsourcing (BPO) Service Market industry trends?
The market is propelled by escalating compliance burdens and the need for operational scalability. However, data security concerns and legacy system integration hurdles act as notable restraints. Despite these friction points, immense opportunities emerge in cloud-native automation, allowing providers to deliver streamlined solutions for complex asset allocation and liquidity management.
Emerging trends and growth patterns in Middleoffice Business Process Outsourcing (BPO) Service Market
The data suggests a profound industry shift toward hyper-automation and artificial intelligence integration within post-trade services and financial reporting. Leading providers are embedding advanced analytics into their service portfolios, empowering institutions to transition from manual reconciliation workflows to real-time, predictive data management and analytics.
How did the COVID-19 pandemic impact the Middleoffice Business Process Outsourcing (BPO) Service Market and drive its recovery trajectory?
The pandemic exposed vulnerabilities in localized, manual middle-office operations, accelerating structural migration toward cloud-enabled BPO models. Post-COVID recovery has been characterized by robust acceleration, as asset managers and banking institutions institutionalize remote-capable, resilient infrastructure to withstand future macroeconomic shocks.
Competitive benchmarking and strategic dynamics in the Middleoffice Business Process Outsourcing (BPO) Service Market
Market concentration is high, featuring global tech giants and specialized BPO leaders. Firms like Accenture PLC, Tata Consultancy Services Limited, and State Street Corporation leverage proprietary technology platforms to capture market share, often utilizing targeted acquisitions to expand their footprint across complex derivatives processing and fund administration.
Executive summary of the Middleoffice Business Process Outsourcing (BPO) Service Market market size and outlook
Driven by persistent cost pressures and regulatory complexity, the Middleoffice Business Process Outsourcing (BPO) Service Market is poised for sustained expansion. Based on our research, the market is projected to surge from $20.01 Billion in 2026 to $28.70 Billion by 2033, reflecting a steady compound annual growth rate (CAGR) of 5.29%.
Projected growth trajectory from 2027 to 2033 for the Middleoffice Business Process Outsourcing (BPO) Service Market
Our forecasting models indicate an absolute revenue expansion of $8.69 Billion between 2027 and 2033, culminating in a market valuation of $28.70 Billion by the end of the forecast period. This steady 5.29% CAGR highlights the institutional shift toward permanent operational expense reduction.
Segmentation analysis of the Middleoffice Business Process Outsourcing (BPO) Service Market
The market breaks down across multiple verticals and service types. By type, it includes Portfolio Management, Trade Management, and Other Types. Vertical coverage spans Banking, Financial Services, and Insurance (BFSI), Manufacturing, Healthcare and Pharmaceuticals, and Retail and Consumer Goods, with BFSI serving as the dominant revenue catalyst.
Geographic distribution and regional performance across the Middleoffice Business Process Outsourcing (BPO) Service Market
Regional performance is heavily anchored by mature financial hubs in North America and Europe, where stringent compliance mandates necessitate advanced outsourcing. Meanwhile, Asia-Pacific exhibits the fastest adoption velocity, driven by expanding banking sectors in India and Singapore seeking cost arbitrage and digital modernization.
In-depth regional review of outsourcing constraints and regulatory environments
Localized cross-border data sovereignty laws in regions like the European Union impose strict operational constraints on offshore processing. Consequently, regional providers must deploy hybrid onshore-offshore delivery models to maintain compliance while servicing complex asset allocation and trade reconciliation requirements for institutional clients.
Company profiles and strategic positioning within the Middleoffice Business Process Outsourcing (BPO) Service Market
Industry leaders deploy distinct competitive moats. Cognizant, Infosys Limited, and Wipro Limited focus on digital transformation and automation frameworks. Meanwhile, institutional custody specialists like State Street Corporation integrate core middle-office BPO directly with asset servicing infrastructure to secure enterprise stickiness.
Porter's Five Forces analysis of competitive intensity in the market
Competitive rivalry is intense among tier-one IT and BPO vendors, while buyer power remains moderate to high due to enterprise consolidation. Threat of new entrants is constrained by high capital requirements and strict compliance standards, whereas substitute threats are mitigated by the bespoke nature of middle-office operations.
SWOT analysis evaluating strategic positioning and market vulnerabilities
Strengths include robust technological infrastructure and deep regulatory expertise among top players. Weaknesses involve integration friction with legacy bank architectures. Opportunities lie in expanding knowledge process outsourcing, while threats stem from macroeconomic volatility and tightening data privacy regulations globally.
Value chain analysis and industry structure from technology inputs to end-users
The value chain flows from foundational cloud infrastructure and software vendors through specialized BPO service integrators to end-users in banking and asset management. Value creation concentrates heavily in the middle tier, where providers apply proprietary workflow automation to trade processing and financial reporting.
Investment insights and strategic recommendations for stakeholders
Investors should target providers specializing in high-margin niches such as risk management analytics and fund administration. Companies demonstrating proprietary AI integration and robust compliance frameworks will disproportionately capture enterprise budgets during the 2027 to 2033 forecast window.
Conclusion and key takeaways for executive decision-makers
The Middleoffice Business Process Outsourcing (BPO) Service Market transitions from a tactical cost-cutting play to a strategic driver of digital resilience. With a projected valuation of $28.70 Billion by 2033, success depends on scaling automated, compliant, and flexible middle-office solutions tailored to complex financial ecosystems.
Research methodology used to triangulate baseline estimates and market sizing
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with C-suite BPO executives, and secondary macroeconomic indicators. This multi-tiered verification process ensures high fidelity in market sizing and growth projections across all evaluated segments.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue streams, segment dynamics, and regional performances within the Middleoffice Business Process Outsourcing (BPO) Service Market from 2026 to 2033. Limitations include potential unforeseen macroeconomic disruptions and rapidly evolving regulatory frameworks that may alter short-term adoption velocities.
Recent developments, corporate partnerships, and strategic expansions in the industry
Recent market activity highlights aggressive strategic partnerships between tech innovators and financial institutions. Firms like Genpact Limited and ExlService Holdings Inc. continue to announce capability-expanding acquisitions, focusing on enhancing their automated trade confirmation, compliance reporting, and analytics service lines.