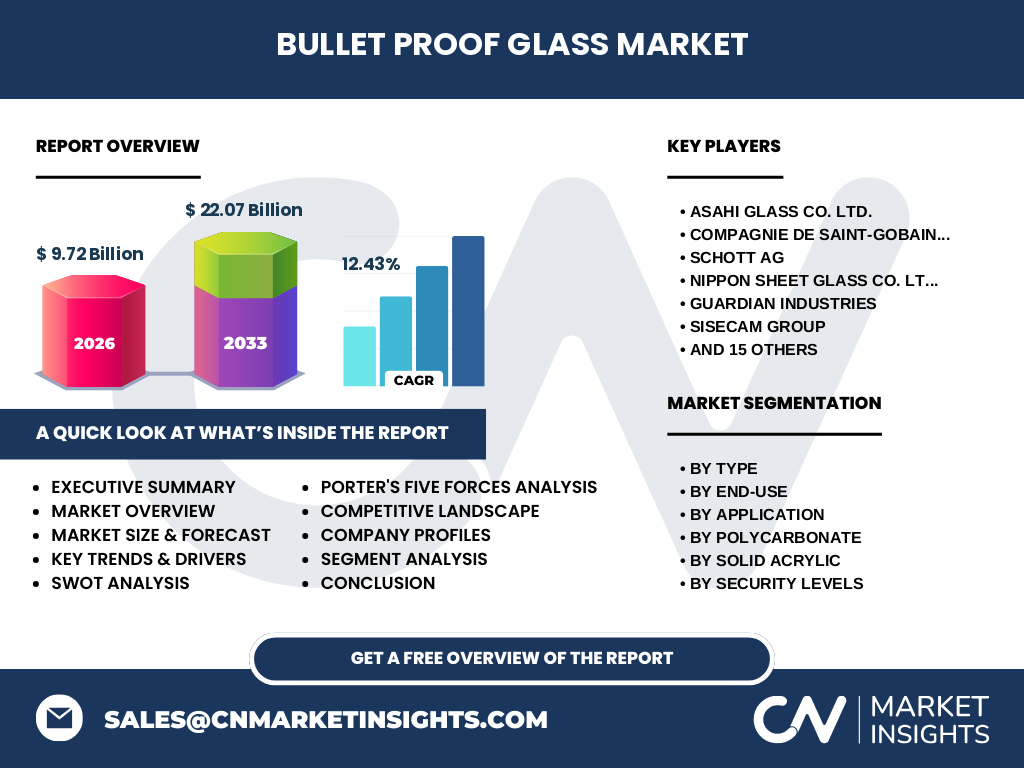
Market overview of the Bullet Proof Glass Market
Our analysis indicates that the Bullet Proof Glass Market is valued at 9.72 Billion in 2026. This specialized sector encompasses high-performance transparent armor solutions utilized across architectural security, cash-in-transit, and defense vehicles, requiring stringent compliance with ballistics standards like UL 752 and EN 1063.
What are the key market drivers, restraints, challenges, and opportunities shaping the industry?
Growth is propelled by rising geopolitical conflicts and urban threat vectors. High manufacturing costs and specialized autoclave processing requirements act as primary restraints. However, massive infrastructure investments in secure government facilities create lucrative expansion opportunities for innovators deploying advanced polycarbonate compositions.
Structural Growth Trends and Emerging Patterns
The data suggests a strong migration toward lightweight, high-threat ballistic protection. Industry participants are aggressively developing ultra-thin architectural laminates that offer multi-hit resistance without compromising natural light transmission or imposing excessive dead-load penalties on building envelopes.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains for critical raw materials like PVB interlayers and polycarbonate resin. Post-crisis recovery has been exceptionally robust, fueled by renewed institutional spending on secure access control, perimeter fortification, and upgraded financial institution teller stations.
Competitive Benchmarking and Market Concentration
The Bullet Proof Glass Market exhibits a consolidated competitive structure dominated by multinational glass titans. Companies such as Compagnie de Saint-Gobain S.A., Schott AG, and Asahi Glass Co. Ltd. leverage extensive R&D capabilities and backward integration to maintain dominant global market shares.
Executive Summary: Key Findings and Market Valuation
Our research confirms a stellar projected market valuation of 22.07 Billion by 2033, expanding at a robust CAGR of 12.43% from 2027. This acceleration highlights the critical need for advanced transparent security across volatile global commercial and defense landscapes.
Market Forecast from 2027 to 2033
Driven by compounding security demands, the market will scale rapidly from its 2026 baseline of 9.72 Billion to reach 22.07 Billion by 2033. This trajectory represents a sustained compound annual growth rate of 12.43%, outpacing historical security glazing expansion rates.
Segmentation Analysis Across Core Categories
Our segmentation framework categorizes the industry by Type (Solid Acrylic, Traditional Laminated, Polycarbonate, Glass-Clad Polycarbonate), End-Use (Automotive, Military, Banking And Finance, Construction), Application, and Security Levels 1 through 8, each playing a vital role in tailoring ballistic protection.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, with North America leading adoption due to strict institutional safety mandates. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, driven by rapid urbanization, massive infrastructure projects, and expanding defense budgets in emerging economies.
In-Depth Regional Review of High-Growth Zones
Urban centers in developing Asian economies and high-risk commercial zones in the Middle East represent prime demand clusters. Localized constraints, such as stringent local building codes and import tariffs on raw polycarbonate sheets, continue to shape regional supplier strategies.
Strategic Positioning of Leading Companies
Industry leaders like Total Security Solutions, Armortex, and SILATEC Sicherheits- und Laminatglastechnik GmbH differentiate themselves through bespoke engineering, rapid prototyping, and proprietary framing integrations that meet rigorous UL and EN ballistic certifications for high-end architectural applications.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power remains moderate due to specialized chemical inputs like SentryGlas Plus (SGP). Threat of substitutes is exceptionally low owing to mandatory ballistic certification thresholds, while intense rivalry among established players drives continuous innovation in multi-layer glass-clad polycarbonate solutions.
SWOT Analysis of the Transparent Armor Sector
Strengths lie in advanced multi-hit ballistic capabilities and superior optical clarity. Weaknesses involve high production costs and heavy weight. Opportunities emerge in VIP electric vehicle armoring, while threats include raw material price volatility and stringent regulatory compliance hurdles.
Value Chain Analysis from Raw Materials to End-Users
The value flow initiates with petrochemical refiners and silica producers supplying raw float glass and polycarbonate resin. Intermediary processors laminate these materials using PVB or polyurethane under extreme heat and pressure before specialized fabricators deliver custom units to end-users.
Investment Insights and Strategic Recommendations
Investors should target manufacturers specializing in lightweight glass-clad polycarbonate and SGP interlayers. Our analysis indicates that firms capable of scaling production for secure electric vehicles and high-security government infrastructure will capture outsized profit margins.
Conclusion and Strategic Takeaways
The Bullet Proof Glass Market represents a high-growth, technology-driven security sector. With a projected expansion to 22.07 Billion by 2033, stakeholders must prioritize material science innovations and strategic regional partnerships to capture emerging market demand.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with chief technical officers, and secondary macroeconomic indicators from regulatory bodies like CEN and the National Institute of Justice.
Scope of the Report and Coverage Parameters
This report evaluates the global Bullet Proof Glass Market across all major material types, security levels, and regional segments from 2026 through 2033. Exclusions involve non-ballistic architectural security films and standard laminated automotive windshields lacking ballistic ratings.
Recent Developments and Industry Announcements
Recent strategic moves feature major joint ventures between glass fabricators and chemical conglomerates aimed at producing lighter multi-layer polycarbonate sheets. Industry leaders like Fuyao Glass Industry Group and Schott AG have ramped up investments in automated autoclave lines to meet surging defense vehicle demands.