What is the scope and industry significance of the Diamond Core Drilling Market?
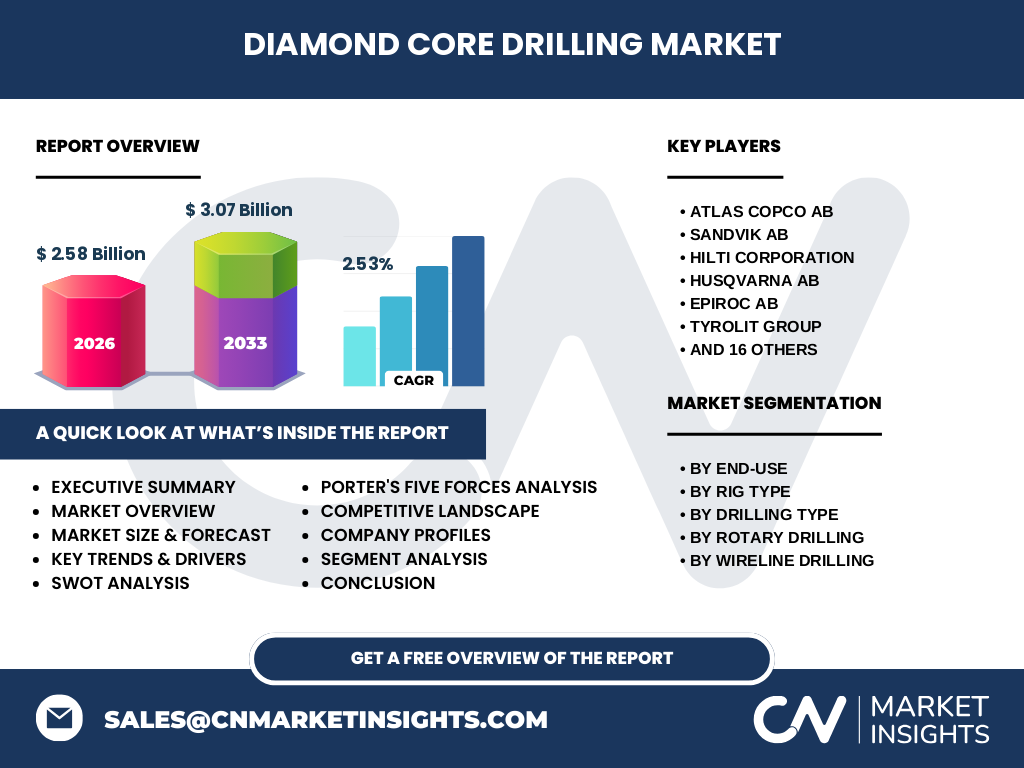
Our analysis indicates that the Diamond Core Drilling Market is valued at 2.58 Billion in 2026. This sector encompasses high-precision exploratory and structural penetration tools critical for modern mining and heavy infrastructure deployment, heavily relying on industrial-grade synthetic diamond segments.
Key market drivers, restraints, challenges, and opportunities shaping the industry
Growth is propelled by rising demand for critical minerals and urban tunneling, though constrained by stringent OSHA silica dust regulations and high initial capital outlays for advanced rigs. Opportunities lie in automated wireline systems minimizing operator underground exposure.
Emerging trends and growth patterns in the sector
The shift toward electric and hydraulic hybrid systems is dominating site upgrades. Electrification reduces carbon footprints in subterranean mines, allowing operators like those utilizing WEKA Elektrowerkzeuge KG solutions to meet strict environmental mandates without sacrificing torque.
How did the COVID-19 pandemic affect the sector and its recovery trajectory?
Pandemic-induced supply chain disruptions for cobalt bond matrices and rig components temporarily halted exploration projects globally. Recovery has been robust, driven by post-pandemic stimulus directed toward critical mineral extraction and urban renewal.
Competitive benchmarking and strategic market dynamics
The competitive landscape features high consolidation among tier-one equipment manufacturers. Industry leaders like Atlas Copco AB, Sandvik AB, and Epiroc AB dominate through proprietary automation technologies, while regional specialists focus on bespoke crawler chassis and localized service networks.
Executive Summary
Valued at 2.58 Billion in 2026, the market is projected to expand to 3.07 Billion by 2033 at a 2.53% CAGR. Strategic focus on wireline automation and sustainable electric rotary systems will separate market leaders from legacy laggards.
Market Forecast from 2027 to 2033
Based on our research, the sector will scale from its 2026 baseline of 2.58 Billion to reach 3.07 Billion by 2033, achieving a steady 2.53% CAGR. This predictable expansion is underpinned by sustained global demand for clean energy transition minerals.
Segmentation Analysis of Rigs, Drilling Types, and End-Uses
The market divides by end-use into Mining and Construction, and by rig types ranging from Truck-Mounted Rigs to Handheld or Manual Core Drills. Drilling methodologies further split into Rotary Drilling and Wireline Drilling, optimizing core recovery rates.
Geographic Distribution and Regional Performance
Regional performance mirrors mining capital expenditures and infrastructure mega-projects. Asia-Pacific leads in consumption due to extensive mineral exploration, whereas North America and Europe prioritize advanced automated wireline and electric systems to comply with stringent workplace safety laws.
In-Depth Regional Review
In North America, strict EPA and MSHA regulations favor dust-suppression integrated rigs from suppliers like Hilti and Husqvarna. Meanwhile, the Latin American and African sectors show heavy reliance on robust truck and skid-mounted systems capable of withstanding remote, harsh terrain.
Strategic Positioning of Leading Companies
Key market participants deploy distinct expansion strategies. Boart Longyear Ltd and Master Drilling Group Ltd. focus on specialized contract drilling services, whereas Tyrolit Group and Di-Corp concentrate on high-wear diamond bit consumable manufacturing and proprietary matrix formulations.
Porter's Five Forces Analysis
Supplier power remains moderate due to specialized synthetic diamond sourcing, while buyer power is high among major mining conglomerates. Threat of substitutes is low given the unmatched precision of diamond core cutting in reinforced concrete and hard rock exploration.
SWOT Analysis of the Industry
Strengths include superior core sample integrity and high penetration rates in hard formations. Weaknesses involve high consumable tool wear. Opportunities center on remote-controlled telemetry, while threats include macroeconomic volatility impacting junior mining exploration budgets.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with industrial diamond synthesis and metal powder sourcing, passing through precision rig and bit manufacturers like Mincon Group PLC and Golz GmbH, before reaching end-user civil contractors and multi-national mining houses.
Investment Insights and High-Potential Areas
Investors should target developers of automated, data-logging wireline systems and eco-friendly electric rotary units. These technologies yield higher margins and directly address customer pain points regarding labor shortages and environmental compliance.
Conclusion and Key Takeaways
The sector presents steady growth, advancing from 2.58 Billion to 3.07 Billion by 2033. Success requires aligning product portfolios with automation, electrification, and rigorous dust-mitigation standards demanded by modern industrial end-users.
Research Methodology
Our baseline estimates are triangulated using a robust mix of primary stakeholder interviews with engineering executives, secondary trade registry data, macroeconomic mining indices, and customs import-export logs for industrial diamond tooling across key global ports.
Scope of the Report
This report covers global market dynamics, segmentation breakdowns, and competitive landscapes from 2026 to 2033. Limitations include localized grey-market manufacturing data exclusions and unlisted private machine-shop fabrication estimates.
Recent Industry Developments
Recent strategic moves feature partnerships between automation software firms and equipment manufacturers like Epiroc AB and Sandvik AB to launch autonomous underground rigs, alongside new product launches focusing on zero-emission electric core drills by WEKA Elektrowerkzeuge KG.