What is the Sintered Steel Market overview and industry significance?
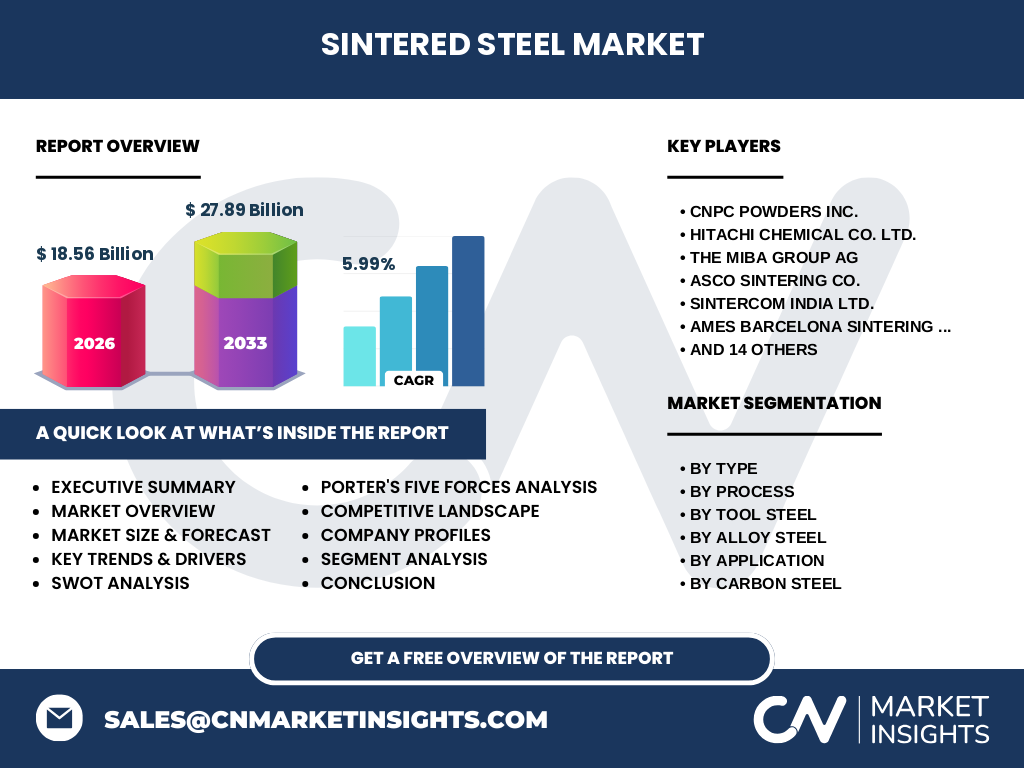
Our analysis indicates that the Sintered Steel Market reached a valuation of 18.56 Billion in 2026. This sector encompasses powder metallurgy components utilizing raw iron powders, graphite, and copper additives, driven by stringent ISO and ASTM material standards. Industry significance stems from near-net-shape manufacturing capabilities that eliminate extensive machining waste for automotive and industrial tier-1 suppliers.
What are the key market drivers, restraints, challenges, and opportunities shaping the Sintered Steel Market?
Growth is primarily propelled by lightweighting mandates from the EPA and European Union emissions standards. However, volatile metal powder pricing acts as a key restraint, squeezing margins for fabricators. Opportunities lie in replacing forged components with high-density powder metallurgy parts through advanced sintering furnaces.
Structural Growth Trends in Sintered Steel Manufacturing
The data suggests an accelerated migration toward Metal Injection Molding (MIM) and Additive Manufacturing processes. End-users demand complex geometries for electric vehicle thermal management systems, forcing fabricators to upgrade sintering lines to handle high-alloy stainless and tool steel powders efficiently.
How did COVID-19 impact the Sintered Steel Market and what is the recovery trajectory?
Pandemic-induced supply chain disruptions caused acute raw material shortages across ferrous powder supply chains. Based on our research, the recovery trajectory has been robust, fueled by post-pandemic automotive rebound and localized reshoring initiatives to mitigate global maritime logistics bottlenecks.
Competitive Benchmarking and Market Concentration
The competitive landscape features established global specialists. Firms like Hoganas AB dominate raw powder supply, while component manufacturers such as Stackpole International Ltd. and The Miba Group AG leverage proprietary sintering profiles to maintain high market concentration and strong OEM supplier relationships.
Executive Summary: Sintered Steel Market Insights
Our comprehensive evaluation highlights a projected expansion to 27.89 Billion by 2033, expanding at a compound annual growth rate of 5.99%. Strategic investments in powder forging and advanced alloy development remain critical for capturing high-margin applications in transmissions and powertrain assemblies.
Market Forecast Projections (2027 to 2033)
The forecast period between 2027 to 2033 will witness accelerated momentum, scaling the market from its 2026 baseline of 18.56 Billion to 27.89 Billion. This expansion is underpinned by a steady 5.99% CAGR, driven by industrial automation and heavy-duty vehicle electrification.
Segmentation Analysis: Types and Processes
Market architecture divides by type into Stainless Steel, Carbon Steel, Alloy Steel, and Tool Steel, alongside processing techniques including Powder Forging Manufacturing and Conventional Manufacturing. Carbon and low-alloy variants dominate structural applications, while MIM addresses intricate electrical and sensor housings.
Regional Market Analysis and Geographic Distribution
Geographic performance reflects automotive manufacturing clusters. North America and Europe lead in high-end alloy adoption due to stringent safety regulations, whereas Asia-Pacific represents the fastest-growing consumption hub, anchored by massive automotive production volumes in China, India, and Japan.
In-Depth Regional Review of Key Production Hubs
Regional analysis highlights North America as a primary adopter of powder forging for light truck transmissions, while European markets focus on lightweighting via austenitic and ferritic stainless steel grades. Localized logistical frameworks heavily influence regional tier-1 sourcing strategies for companies like SSI Sintered Specialties LLC.
Strategic Company Profiles in the Sintered Steel Sector
Key market participants exhibit distinct strategic positioning. ASCO Sintering Co. and Schunk Sinter Metals GmbH focus on high-precision automotive components, while Sintercom India Ltd. and AMES BARCELONA SINTERING S. A. expand their regional footprints through targeted capacity expansions and specialized metallurgical formulations.
Porter's Five Forces Analysis of the Industry
Supplier power remains moderate due to consolidated ferrous powder refiners like Hoganas AB. Buyer power is high among automotive OEMs demanding aggressive cost reductions. Threat of substitution from advanced engineering plastics is mitigated by sintered steel's superior thermal and mechanical load-bearing capabilities.
SWOT Analysis of Sintered Steel Market Participants
Strengths include high material utilization rates exceeding 95%. Weaknesses involve high initial capital expenditure for compaction presses and sintering furnaces. Opportunities abound in renewable energy infrastructure, while threats stem from shifting macroeconomic trade tariffs on imported metal powders.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with powder producers supplying raw grades to component fabricators, who utilize compaction presses and continuous sintering furnaces. Finished parts flow directly to transport, electrical, and industrial end-users through specialized logistics networks operating near major manufacturing clusters.
Investment Insights and High-Potential Areas
High-potential investment avenues center on additive manufacturing integration and high-alloy powder production. Strategic stakeholders should target acquisitions of regional component manufacturers possessing proprietary tooling capabilities to capture rising demand in electric vehicle drivetrain components.
Conclusion and Strategic Takeaways
The Sintered Steel Market demonstrates resilient fundamentals, supported by a 5.99% CAGR toward 2033. Success in this landscape requires continuous metallurgical innovation, process automation, and close engineering collaboration with automotive and industrial OEMs to overcome margin pressures.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with executives from Federal-Mogul Goetze Limited and Stackpole International Ltd., and secondary macroeconomic indicators sourced from international trade and metallurgical associations.
Scope of the Report and Coverage Parameters
This report covers global market sizing, segmental breakdowns across material types and production processes, and regional evaluations from 2026 through 2033. Limitations include inherent forecasting uncertainties regarding raw material commodity price volatility and shifting geopolitical trade agreements.
Recent Industry Developments and Strategic Moves
Recent developments feature strategic partnerships and capacity investments by key players such as Hitachi Chemical Co. Ltd. and Umicore S. A. Companies are actively launching proprietary high-density alloy powders designed to withstand extreme thermal stresses in modern hybrid and electric vehicle transmissions.