What is the market overview and industry significance of the Food And Beverage Metal Cans Market?
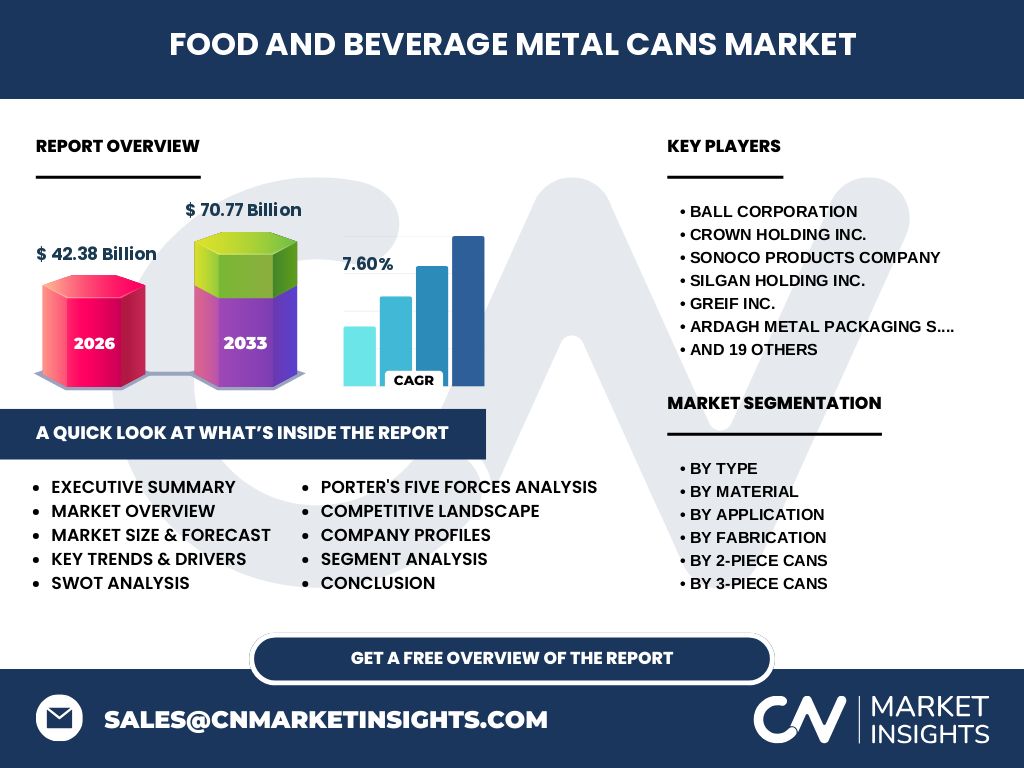
The Food And Beverage Metal Cans Market is valued at $42.38 Billion in 2026, serving as an indispensable pillar of the global packaging sector. Our analysis indicates that rigid metal packaging remains critical for preserving perishable food and beverage items through extensive global supply chains.
What are the key market drivers, restraints, challenges, and opportunities shaping the Food And Beverage Metal Cans Market?
Growth is propelled by surging demand for infinitely recyclable packaging materials like aluminum. However, structural headwinds such as volatile bauxite and steel coil pricing constrain margin expansion. Industry participants find lucrative opportunities by innovating lightweight 2-Piece Cans to reduce freight expenses.
Emerging trends and growth patterns in the Food And Beverage Metal Cans Market
The shift toward premium Printed and Embossed finishes allows craft beverage brands to stand out on retail shelves. Based on our research, sustainability mandates from the EU Packaging and Packaging Waste Regulation are accelerating the adoption of high-recycled-content aluminum.
How did the COVID-19 pandemic impact the Food And Beverage Metal Cans Market and what does the recovery trajectory look like?
The pandemic triggered unprecedented spikes in at-home beverage consumption, straining primary producers like Ball Corporation and Crown Holdings Inc. Despite initial supply chain bottlenecks at major container ports, the market achieved a robust post-pandemic recovery, laying the groundwork for a 7.60% CAGR.
Competitive benchmarking and strategic dynamics in the Food And Beverage Metal Cans Market
Market concentration remains high, dominated by global leaders such as Ardagh Metal Packaging S.A., Silgan Holdings Inc., and Can-Pack S.A. Strategic positioning focuses heavily on multi-plant regional footprints to minimize costly long-distance logistics for heavy steel and aluminum payloads.
Executive summary of key findings regarding the Food And Beverage Metal Cans Market
Our comprehensive evaluation highlights a thriving industry projected to reach $70.77 Billion by 2033. Driven by a stellar 7.60% CAGR from 2027 to 2033, the Food And Beverage Metal Cans Market represents a high-conviction sector for sustainable packaging investments.
Market forecast trajectory from 2027 to 2033
The data suggests sustained expansion, scaling the market from its 2026 baseline to $70.77 Billion by 2033. This trajectory is underpinned by steady 7.60% CAGR growth, fueled by rising urban disposable incomes and cold-chain infrastructure development across emerging economies.
Segmentation analysis across material, application, and fabrication types
The market divides by Material (Aluminum, Steel), Application (Food, Beverage), and Fabrication (Plain, Embossed, Printed). 2-Piece Cans utilize Drawn And Ironed technologies predominantly for beverages, while 3-Piece Cans rely on Welded configurations for processed foods.
Regional market analysis and geographic performance distribution
Geographic performance varies significantly, with North America and Europe leading in sophisticated Pressurized Cans consumption. Meanwhile, Asia-Pacific acts as the primary volume engine, driven by expanding middle-class demographics and rapid retail modernization across key metropolitan hubs.
In-depth regional review of high-growth territories
Regional growth is heavily concentrated in areas with established recycling ecosystems. Strict landfill reduction targets enforced by regulatory agencies in Western economies continue to favor infinitely recyclable metal substrates over traditional polymer alternatives.
Strategic company profiles of leading industry participants
Industry titans like Ball Corporation and Crown Holding Inc. leverage massive economies of scale to dominate global beverage supply agreements. Concurrently, specialized regional players like Sonoco Products Company and Greif Inc. capture niche industrial food packaging segments through tailored engineering solutions.
Porter's Five Forces analysis of competitive intensity
Bargaining power of raw material suppliers remains moderate-to-high, directly impacting aluminum and steel acquisition costs. Threat of substitutes is mitigated by metal's superior barrier properties against light and oxygen, protecting product integrity better than flexible plastic alternatives.
SWOT analysis highlighting internal and external market factors
Key strengths lie in metal's 100% recyclability profile. Weaknesses involve high initial capital expenditure requirements for can-manufacturing lines. Opportunities abound in premium craft beverage segments, whereas threats stem from relentless substitution pressures by advanced paperboard and biodegradable polymers.
Value chain analysis from raw material extraction to end-user consumption
The value flow initiates with bauxite mining and steel milling, progressing through coil rolling, high-speed body fabrication, and lithographic decoration. Finished containers are shipped to food processors and beverage fillers before reaching major retail distribution channels.
Investment insights and strategic high-potential areas
Investors should target manufacturers capable of producing ultra-lightweight Impact Extruded Cans. Our analysis indicates that capital allocation toward closed-loop recycling infrastructure yields the highest defensible moat against tightening environmental regulations.
Conclusion and core takeaways for industry stakeholders
The Food And Beverage Metal Cans Market offers exceptional growth, underscored by a forecasted 7.60% CAGR reaching $70.77 Billion by 2033. Companies that successfully balance lightweighting innovations with robust circular-economy mandates will capture outsized market share.
Research methodology behind baseline estimates and triangulation
Baseline estimates are meticulously triangulated by cross-referencing primary stakeholder interviews with C-suite executives, official trade registry statistics from international metal associations, and secondary macroeconomic indicators regarding global consumer spending patterns.
Scope of the report, coverage parameters, and analytical limitations
This report encompasses global revenue evaluations for 2-Piece Cans and 3-Piece Cans across food and beverage applications. Limitations exclude secondary transport packaging and non-metal rigid containers, maintaining a strict focus on primary metal packaging assets.
Recent developments, corporate announcements, and strategic industry partnerships
Recent market activities feature aggressive joint ventures aimed at increasing post-consumer recycled content in aluminum sheet supplies. Major operators are investing heavily in renewable energy-powered smelting facilities to appease institutional ESG investors and brand owners.