What is the Oil Shale Market scope and definition?
The Oil Shale Market encompasses the extraction, processing, and refinement of kerogen-rich sedimentary rocks into valuable hydrocarbons. Our analysis indicates this sector plays a critical role in global energy security by providing alternative liquid fuels like Shale Gasoline and Shale Diesel when conventional crude reserves face geopolitical and logistical constraints.
Structural Growth Drivers and Restraints in the Oil Shale Market
Key drivers include surging demand for Aviation Kerosene and technological breakthroughs in In-Situ Technology. However, market restraints involve stringent environmental regulations enforced by bodies like the EPA and high water-usage constraints. Companies such as ExxonMobil Corporation and Chevron Corporation must navigate these hurdles while optimizing their extraction yields.
Emerging Trends in the Oil Shale Market
The industry is witnessing a pivot toward Renewable Shale Diesel and advanced Ex-Situ Technology designed to lower carbon footprints. Based on our research, innovators like AuraSource Inc. and Shell PLC are leading the charge by integrating digital telemetry into retort processes to enhance thermal efficiency.
COVID-19 Impact Analysis on the Oil Shale Market
The pandemic severely disrupted supply chains and slashed crude benchmarks, temporarily halting capital expenditure across major shale plays. Our evaluation shows that recovery has been propelled by post-lockdown fuel demand surges, with firms like ConocoPhillips Company and Marathon Oil Corporation restructuring balance sheets to resume profitable operations.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is moderately consolidated, featuring dominant conglomerates alongside agile independents. Key players like Occidental Petroleum Corporation and BP PLC deploy proprietary fracturing techniques to secure market share, while regional entities focus on localized supply chain dominance for Petrochemical Feedstocks.
Executive Summary of the Oil Shale Market Report
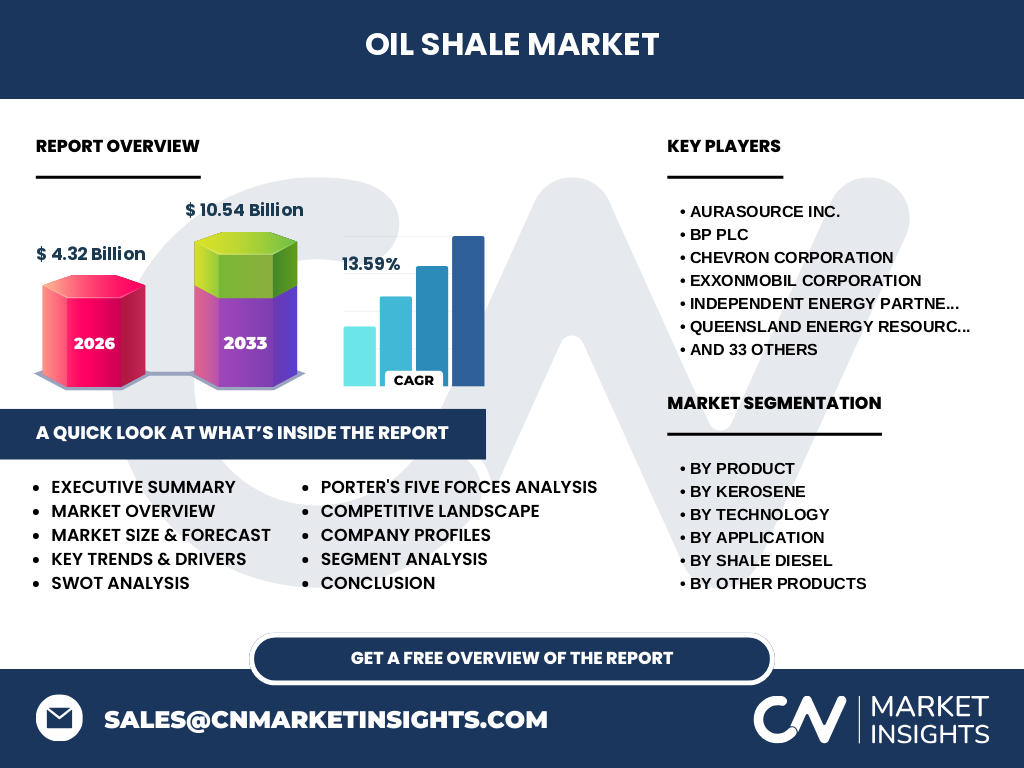
Our comprehensive assessment values the Oil Shale Market at $4.32 Billion in 2026, projecting a robust expansion to $10.54 Billion by 2033 at a 13.59% CAGR. This trajectory is anchored by heavy investments in Ultra-Low Sulfur Diesel (ULSD) production and rising electricity generation needs.
Oil Shale Market Forecast from 2027 to 2033
Driven by accelerating commercialization of Asphalts And Residuum and specialty fuels, the market is poised for exponential gains. The data suggests that capital deployment into Shale Oil extraction will surge, helping bridge the gap between depleting conventional reserves and rising global energy consumption through 2033.
Segmentation Analysis of the Oil Shale Industry
The market breaks down by product into Shale Gasoline, Shale Diesel, and Kerosene, alongside technology bifurcations like In-Situ Technology and Ex-Situ Technology. Applications span across fuel, electricity, and Cement And Chemicals, with niche segments including Specialty Shale Gasoline driving high-margin returns.
Regional Market Analysis and Geographic Performance
North America remains the dominant revenue hub due to extensive deposits and advanced extraction infrastructure led by players like Chesapeake Energy Corporation and Devon Energy Corporation. Meanwhile, Asia-Pacific exhibits rapid growth potential, supported by state-backed initiatives in nations targeting energy self-sufficiency via Heating Kerosene and power generation.
In-Depth Regional Review
Regional performance highlights North America's stronghold in Ultra-Low Sulfur Diesel (ULSD) production, supported by favorable regulatory sandboxes in select states. In contrast, international markets such as Australia, through Queensland Energy Resources Limited, focus on unlocking massive ex-situ reserves to supply domestic petrochemical hubs.
Company Profiles and Strategic Positioning
Industry leaders like Schlumberger Limited and Halliburton Company provide indispensable oilfield services that optimize well completion. Concurrently, producers such as EOG Resources Inc. and Pioneer Natural Resources Company leverage proprietary data analytics to maximize recovery rates across Shale Diesel reservoirs.
Porter's Five Forces Analysis of the Sector
Bargaining power of buyers remains moderate due to standardized commodity pricing, while supplier power is constrained by specialized equipment availability from firms like National Oilwell Varco Inc. Threat of substitutes is mitigated by unique regional advantages of Shale Oil, though strict regulatory entry barriers keep threat of new entrants low.
SWOT Analysis for Oil Shale Market Stakeholders
Strengths include vast resource bases and high-energy-density output of Shale Gasoline. Weaknesses involve high initial capital expenditure. Opportunities lie in Renewable Shale Diesel integration, while threats stem from aggressive global decarbonization mandates and volatile commodity price fluctuations affecting firms like Hess Corporation.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with geological exploration and land acquisition by operators like Continental Resources Inc., progressing through retorting and refining into Petrochemical Feedstocks, and culminating in distribution to end-users via major logistics networks managed by downstream fuel distributors and chemical manufacturers.
Investment Insights and High-Potential Areas
Investors should target technological innovators specializing in In-Situ Technology and low-emissions processing. High-potential areas include Aviation Kerosene refining and advanced Asphalts And Residuum applications, offering superior margin expansion compared to commoditized fuel grades.
Conclusion and Key Strategic Takeaways
The Oil Shale Market represents a dynamic frontier in global energy, underscored by a projected 13.59% CAGR through 2033. Success requires balancing aggressive asset development in Shale Oil with proactive compliance alongside evolving environmental standards championed by operators like Total S.A.
Research Methodology
Our baseline estimates are triangulated using a rigorous mix of primary stakeholder interviews with executives from Anadarko Petroleum Corporation and Apache Corporation, secondary macroeconomic indicators, and trade registry data from regulatory bodies to ensure absolute market intelligence accuracy.
Scope of the Report
This report covers global production, consumption trends, and technological evaluations across all stated product segments from 2027 to 2033. Limitations include inherent forecasting uncertainties regarding sudden geopolitical shifts and unforeseen regulatory adjustments impacting firms like Murphy Oil Corporation.
Recent Developments in the Oil Shale Industry
Recent milestones feature strategic joint ventures aimed at commercializing cleaner Ex-Situ Technology retorting systems. Industry pioneers such as Japan Petroleum Exploration Co Ltd. and Gazprom Neft PJSC have announced targeted partnerships to enhance the yield of Shale Diesel while reducing water intensity in arid extraction zones.