Market overview and structural significance of the Sports Betting Market
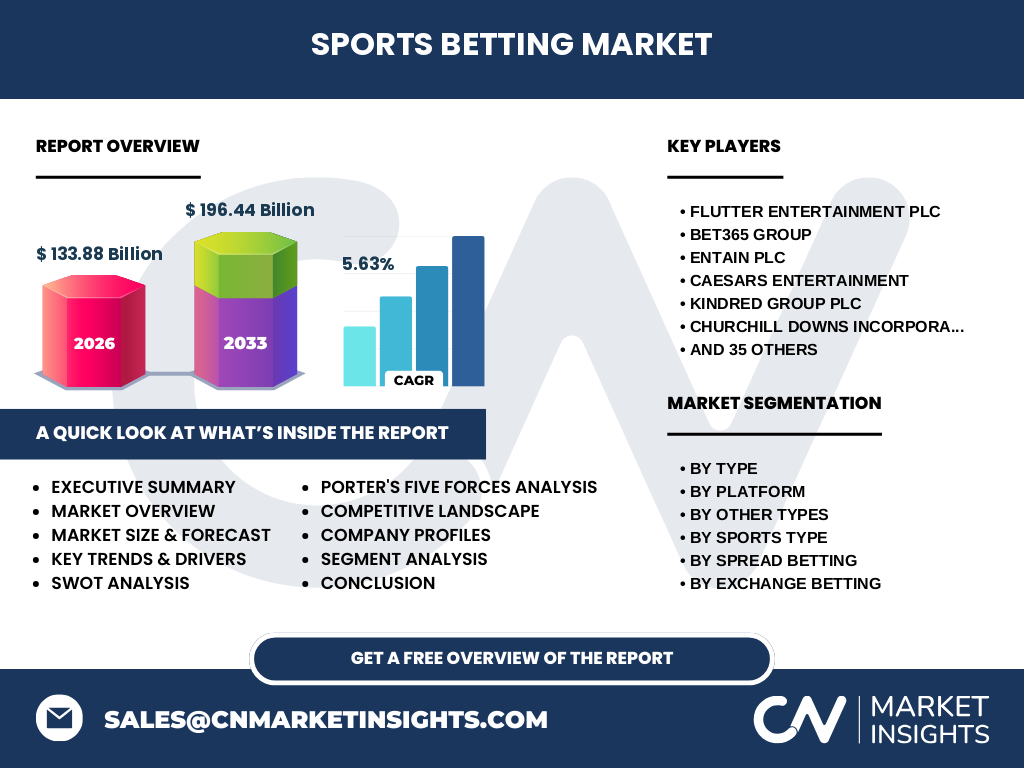
Our analysis indicates that the Sports Betting Market represents a multi-billion dollar economic ecosystem projected to reach $196.44 Billion by 2033, scaling up from $133.88 Billion in 2026. This sector encompasses diverse wagering frameworks—ranging from Live Or In-Play action to Fixed Odd Betting—governed by complex regulatory frameworks across international jurisdictions like the UK Gambling Commission and state-level US gaming boards.
Key market drivers, restraints, challenges, and opportunities shaping the industry
Growth is propelled by mobile-first wagering adoption and legislative liberalization, while regulatory friction and compliance costs act as major restraints. Cryptocurrency integration and localized compliance hurdles present distinct operational challenges. Strategic opportunities lie within E-Sports Betting expansion and real-time data monetization, favoring operators with robust technical architecture and nimble risk-management systems.
Emerging trends and growth patterns in the Sports Betting Market
The shift toward hyper-personalized in-game wagering experiences is transforming engagement metrics across platforms. Operators are leveraging micro-markets within Proposition (Prop) Betting to drive user retention. Data-driven algorithmic pricing models now dictate competitive advantage, pushing legacy bookmakers to acquire specialized B2B software providers to maintain market share.
COVID-19 impact analysis and pandemic recovery trajectory
The pandemic caused an unprecedented contraction due to the global cancellation of live sporting events, forcing operators to pivot toward virtual sports and E-Sports Betting. The subsequent recovery trajectory was sharply accelerated by digital acceleration and expedited state-level regulatory approvals in North America, establishing a resilient online-first operational baseline.
Competitive landscape, major players, and strategic market concentration
The competitive landscape is consolidated around tier-one global operators like Flutter Entertainment plc, Entain plc, and Bet365 Group, alongside rapidly scaling US entities like DraftKings Inc. and FanDuel Sportsbook. Industry giants utilize aggressive promotional spending and proprietary technology stacks to capture market share, while regional players carve out niches via localized regulatory expertise.
Executive summary of key findings in the Sports Betting Market
Valued at $133.88 Billion in 2026, the market is poised to expand at a steady CAGR of 5.63% through 2033, culminating in $196.44 Billion. Convergence between media broadcasting and interactive wagering, coupled with the proliferation of Exchange Betting platforms, underpins this long-term structural expansion.
Sports Betting Market forecast and revenue projections from 2027 to 2033
The forecast period exhibits robust momentum, driving the valuation from its 2026 baseline of $133.88 Billion to a projected $196.44 Billion by 2033 at a CAGR of 5.63%. This trajectory assumes sustained legalization waves in high-population territories and deepening market penetration of Online platform ecosystems.
Segmentation analysis across betting types, platforms, and sports categories
Market segmentation categorizes operations by Type—including Live Or In-Play, Fixed Odd Betting, Exchange Betting, Spread Betting, and Pari-Mutuel—alongside Platform divisions of Online and Offline. Specialized wagering categories like Accumulator Betting and Teaser Betting cater to recreational demographics, while core sports like Football, Basketball, and Horse Racing dominate handle volumes.
Regional market analysis and geographic performance distribution
Geographic performance exhibits stark contrasts, with North America leading incremental growth driven by post-PASPA state legalizations involving major players like BetMGM and Caesars Entertainment. Europe remains a mature, highly regulated stronghold anchored by legacy operators like Kindred Group plc and Betsson AB, whereas emerging economies in Latin America and Asia represent untapped frontiers.
In-depth regional review of high-growth regulatory jurisdictions
North American markets demonstrate rapid revenue velocity following state-by-state legislative rollouts, heavily contested by Barstool Sportsbook, PointsBet, and BetRivers. Meanwhile, European markets face tightening compliance mandates from bodies like the UKGC, prompting structural consolidation among firms such as 888 Holdings and Betclic Everest Group.
Company profiles and strategic positioning of leading industry participants
Market leaders utilize distinct strategic plays: Flutter Entertainment plc leverages global brand synergy across FanDuel and Paddy Power, while DraftKings Inc. focuses on tech-forward product innovation. European stalwarts like Bet365 Group maintain dominance via proprietary platform infrastructure, and niche operators like Sporttrade Inc introduce financial exchange mechanics to sports wagering.
Porter's Five Forces analysis of the global wagering sector
Competitive rivalry is intensely high due to customer acquisition costs and low switching barriers. Threat of substitutes remains moderate, tempered by the unique real-time thrill of Live Or In-Play betting. Bargaining power of suppliers is elevated for official league data providers, while regulatory bodies hold immense structural leverage over market entry.
SWOT analysis highlighting internal capabilities and external market dynamics
Strengths include sophisticated algorithmic risk management and seamless mobile applications. Weaknesses involve high marketing expenditure required for player acquisition. Opportunities center on E-Sports Betting integration and international expansion. Threats stem from unpredictable regulatory shifts, taxation policy changes, and problem-gambling legislative crackdowns.
Value chain analysis from raw data providers to end-user platforms
The value chain initiates with primary sports data aggregators (e.g., Sportradar, Genius Sports), flowing through proprietary oddsmaking and risk-assessment engines. B2C operators like Betway, Unibet, and Parimatch then distribute these markets via Online applications, culminating in user engagement through localized payment gateways and responsible gambling verification tools.
Investment insights and high-potential strategic growth areas
Investors should prioritize B2B software providers specializing in automated Live Or In-Play pricing algorithms and compliance automation. High-potential areas also include localized Latin American platforms such as Bplay and emerging E-Sports Betting infrastructure that captures younger demographic cohorts with lower traditional sports affinity.
Conclusion and core takeaways for market stakeholders
The Sports Betting Market offers compelling long-term upside, scaling to $196.44 Billion by 2033. Success hinges on regulatory agility, technological superiority in mobile UI, and diversification across Exchange Betting and Proposition (Prop) Betting product verticals to maximize lifetime player value.
Research methodology utilizing triangulation and stakeholder interviews
Baseline estimates are triangulated by cross-referencing public financial filings of major entities like Churchill Downs Incorporated and FDJ – La Française des Jeux with regulatory tax receipts, primary stakeholder interviews with industry executives, and macroeconomic indicators concerning disposable income and digital infrastructure penetration.
Scope of the report, coverage parameters, and operational limitations
This report covers global commercial wagering activities across both Online and Offline mediums, evaluating segments including Fixed Odd Betting and Pari-Mutuel. Limitations include the exclusion of unregulated offshore black-market operations and informal peer-to-peer wagers lacking verifiable financial auditing data.
Recent developments, corporate partnerships, and strategic mergers
Recent industry activity is characterized by cross-border mergers, media-publishing partnerships, and technological acquisitions. Companies like SuperDraft Inc and BetWarrior continue to refine daily fantasy and mobile integration, while European entities forge official sponsorship alliances with major sports leagues to secure proprietary data access.