Market overview — definition, scope, and industry significance of Grocery List Generation Artificial Intelligence (AI) Market
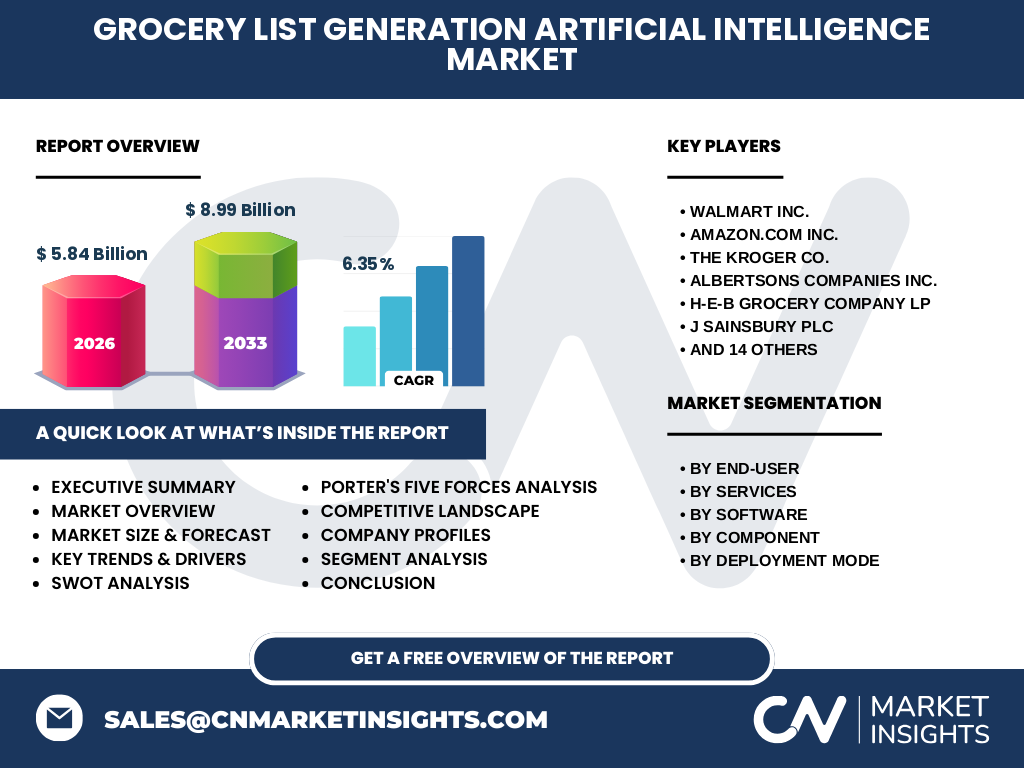
Our analysis indicates that the Grocery List Generation Artificial Intelligence (AI) Market is valued at 5.84 Billion in 2026. This burgeoning sector encompasses intelligent software and specialized services that automate household provisioning through advanced machine learning algorithms. Industry significance stems from its profound disruption of traditional retail logistics, shifting consumer habits from reactive shopping to predictive inventory management across major retail supply chains.
Key market drivers, restraints, challenges, and opportunities shaping Grocery List Generation Artificial Intelligence (AI) Market
The Grocery List Generation Artificial Intelligence (AI) Market industry trends reveal that soaring smartphone penetration and consumer demand for hyper-personalized shopping act as primary drivers. Conversely, strict data privacy mandates enforced by regional bodies like the EU GDPR present notable regulatory compliance restraints. Market opportunities lie heavily in integrating predictive replenishment algorithms directly with smart kitchen hardware to eliminate household food waste.
Emerging trends and growth patterns in Grocery List Generation Artificial Intelligence (AI) Market
A defining shift within the Grocery List Generation Artificial Intelligence (AI) Market analysis is the convergence of Natural Language Processing tools with spatial computer vision systems. Consumers increasingly rely on conversational assistants to orchestrate weekly meal plans, which dynamically populate localized supermarket e-commerce carts, resulting in unprecedented basket-size optimization for participating food delivery networks.
COVID-19 impact analysis — how the pandemic affected Grocery List Generation Artificial Intelligence (AI) Market and the recovery trajectory
Pandemic lockdowns accelerated the adoption of automated digital grocery provisioning, forcing retailers to rapidly upgrade their recommendation engines and cloud infrastructure. Our research shows this disruption permanently altered consumer tolerance for out-of-stock items, permanently cementing AI-driven list generation as an essential tool for contactless, efficient household inventory management.
Competitive landscape — major players, market concentration, and strategic dynamics
The competitive ecosystem features an intense interplay between tech giants like Walmart Inc. and Amazon.com Inc., alongside pure-play innovators such as Bring! Labs AG and Listonic Sp. z o.o. Market concentration is moderately consolidated among traditional supermarket giants wielding vast proprietary customer purchase data, while agile startups compete fiercely on UI innovation and niche dietary personalization algorithms.
Executive summary — high-level synthesis of key findings about Grocery List Generation Artificial Intelligence (AI) Market
Valued at 5.84 Billion in 2026, the market is poised for robust expansion driven by algorithmic retail innovation. Strategic partnerships between grocery chains and software developers remain critical for capturing market share. Stakeholders must prioritize cloud-based scalability and robust recommendation engines to capitalize on shifting consumer preferences toward automated nutritional planning.
Market forecast — projected growth from 2027 to 2033
Based on our research, the Grocery List Generation Artificial Intelligence (AI) Market market size is projected to expand from 8.99 Billion by 2033, exhibiting a steady compound annual growth rate of 6.35%. This trajectory reflects widespread mainstream integration of predictive replenishment software across both developed metropolitan retail sectors and emerging online grocery ecosystems.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Market segmentation spans end-users including Individuals, Retailers, and Food Delivery Services; services encompassing Integration and Managed Services; software such as Machine Learning Platforms and Recommendation Engines; components divided into Software and Services; and deployment modes spanning Cloud-Based and On-Premises architectures. Each segment serves a vital role in balancing consumer-facing convenience with enterprise backend inventory synchronization.
Regional market analysis — geographic distribution and performance across regions
Geographic performance highlights North America as the dominant revenue generator, bolstered by advanced digital grocery infrastructure and high consumer smartphone adoption rates. Meanwhile, Europe demonstrates stringent regulatory oversight regarding consumer algorithmic profiling, whereas the Asia-Pacific region exhibits the fastest acceleration driven by hyper-dense urban delivery networks and mobile-first retail models.
In-depth regional review — detailed examination of key regional markets
North American growth is anchored by major enterprise deployments from players like The Kroger Co. and Instacart, optimizing regional supply chains through predictive list analytics. In contrast, European markets require strict adherence to local data sovereignty laws, forcing developers like Ocado Group Plc to prioritize decentralized, privacy-compliant cloud deployment modes for their automated grocery solutions.
Company profiles — strategic positioning of leading companies in Grocery List Generation Artificial Intelligence (AI) Market
Industry leaders leverage distinct strategic advantages: Walmart Inc. and Amazon.com Inc. dominate via vertically integrated logistics and massive transactional datasets. Simultaneously, specialized innovators like Mealime Inc. and Cozi Group Inc. secure loyal user bases through hyper-focused dietary planning features, while Ocado Group Plc licenses advanced automated fulfillment tech to global supermarket chains.
Porter's Five Forces analysis — competitive forces assessment
Bargaining power of buyers remains high due to low switching costs among consumer mobile applications. Threat of new entrants is moderate, constrained by high proprietary data requirements and complex grocery inventory API integrations. Supplier power is mitigated by the abundance of open-source machine learning frameworks and cloud infrastructure providers.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Core strengths include deep personalization and seamless retail cart syncing. Weaknesses involve high initial customer acquisition costs and algorithmic recommendation errors. Opportunities lie in expanding into enterprise B2B corporate catering software, while threats encompass tightening regulatory crackdowns on consumer data harvesting and user privacy breaches.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value flow initiates with foundational raw data inputs—such as nutritional databases and agricultural supply metrics—processed through machine learning platforms and recommendation engines. This intelligence flows downstream via cloud-based APIs to supermarkets, food delivery services, and end-user mobile interfaces, ultimately driving automated checkout conversion at physical and digital registers.
Investment insights — strategic recommendations and high-potential areas
Investors should target developers specializing in multimodal Natural Language Processing tools and advanced Computer Vision systems designed for automated pantry auditing. Strategic acquisitions of niche app developers by established supermarket conglomerates like Albertsons Companies Inc. or Tesco Plc represent high-potential exit vectors within this market.
Conclusion and key takeaways
The Grocery List Generation Artificial Intelligence (AI) Market represents a transformative frontier in digital retail, bridging the gap between household consumption habits and enterprise supply chains. With a projected climb toward 8.99 Billion by 2033, firms that successfully blend user-friendly recommendation engines with robust cloud security will capture dominant market positioning.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by combining exhaustive trade registry data, primary stakeholder interviews with retail technology executives, and secondary macroeconomic indicators. This multi-layered approach ensures high fidelity in sizing complex software deployments across both cloud-based and on-premises enterprise environments.
Scope of the report — coverage parameters and limitations
This report covers global deployment models, software categories, service types, and end-user verticals across major global economies. Limitations include potential variance in regional regulatory enforcement regarding consumer data usage and unpredictable macroeconomic fluctuations impacting discretionary retail technology spending through the forecast window.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent market dynamism includes strategic AI feature rollouts by platforms like ShopWise AI Ltd. and Shoptimus AI Inc., introducing predictive pantry tracking via smart appliance integrations. Major partnerships between traditional grocery operators and AI startups continue to accelerate, focusing heavily on reducing last-mile fulfillment friction and minimizing household food waste.