What is the market overview and scope of the Workover Rigs Market?
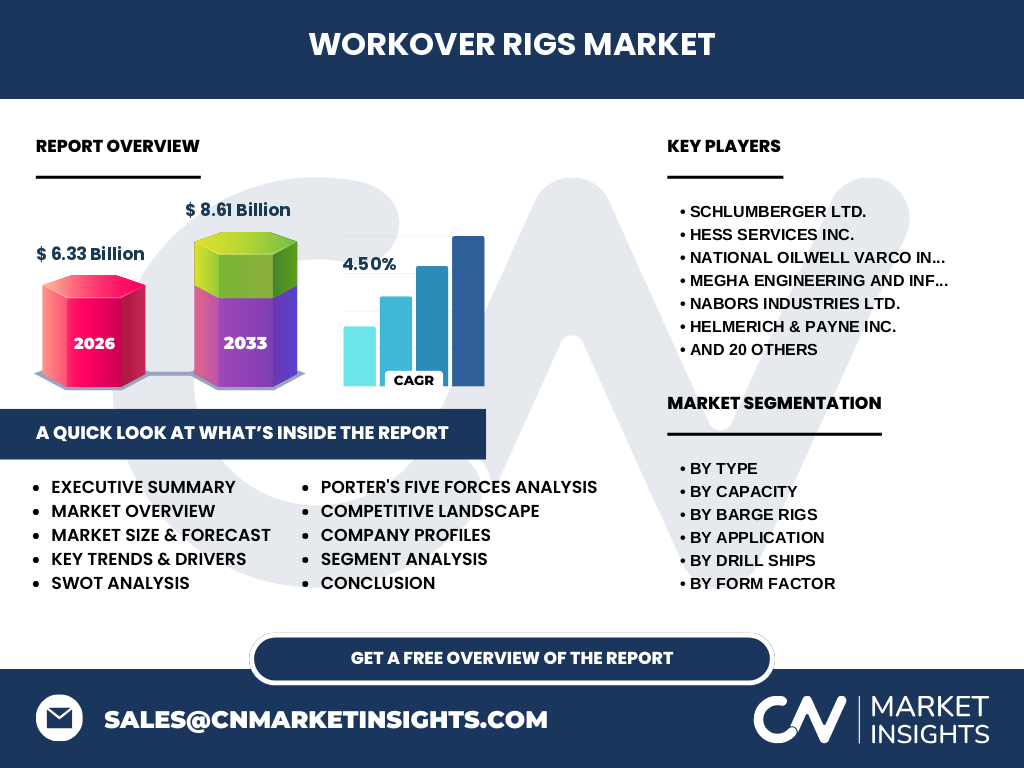
The Workover Rigs Market represents a vital sector within oilfield services, valued at $6.33 Billion in 2026. This market encompasses specialized equipment used for well intervention, maintenance, and production enhancement. Our analysis indicates that mature onshore and offshore fields heavily rely on these assets to sustain hydrocarbon output amid declining reservoir pressures.
Structural Growth Drivers and Restraints in the Workover Rigs Market
Growth is propelled by aging hydrocarbon infrastructure and rising interventions in mature basins. Key restraints involve stringent environmental regulations enforced by bodies like the EPA and high capital expenditures for advanced fleets. Volatile crude oil prices further challenge operators attempting long-term fleet modernization programs.
Emerging Trends and Growth Patterns Shaping Operations
The industry is rapidly adopting automation and digitalization to optimize well interventions. Automated Rig Technologies Ltd. and KOLLER Solutions Maschinen- und Anlagenbau GmbH lead this shift by integrating rig remote monitoring and automated pipe handling. These innovations significantly reduce Non-Productive Time (NPT) during complex operations.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted the Workover Rigs Market through sudden capital expenditure freezes and strict offshore logistical constraints. Recovery has been driven by post-pandemic energy security demands. Firms like Fieldwood Energy LLC and Superior Energy Services restructured operations to capitalize on rebounding global drilling activity.
Competitive Benchmarking in the Workover Rigs Market
The market features intense competition among major oilfield service providers. Schlumberger Ltd., Nabors Industries Ltd., and Helmerich & Payne Inc. dominate through extensive global footprints. Smaller regional players like Moncla Energy Services LLC carve out niches by offering localized, highly responsive well servicing fleets.
Executive Summary: Key Findings of the Research
Our comprehensive research confirms a robust expansion path for the sector, projecting growth from $6.33 Billion in 2026 to $8.61 Billion by 2033 at a CAGR of 4.50%. Strategic focus on high-capacity units and automated systems remains critical for outperforming broader market averages.
Market Forecast and Trajectory from 2027 to 2033
The market is set to expand from $8.61 Billion starting in 2027 through 2033, achieving a steady 4.50% CAGR. Accelerating production requirements in deepwater and ultra-deepwater plays will drive sustained demand for advanced semi-submersible and drill ship intervention units over this forecast period.
Segmentation Analysis: Breaking Down the Industry
The market splits across multiple dimensions. By Type: Barge Rigs, Tender Rigs, Jack Ups Rigs, Platform Rigs, Semi-Submersible Rigs, and Drill Ship. Capacity tiers span Below 1,000 HP, 1,000-1,500 HP, and Above 1,500 HP. Form factors include Single Drum and Double Drum configurations, catering to diverse onshore and offshore environments.
Geographic Distribution and Regional Performance
Regional performance varies based on mature asset concentration and offshore activity hubs. North America dominates onshore intervention demand, supported by dense infrastructure in basins like the Permian. Meanwhile, offshore-heavy regions in the Middle East and Asia-Pacific prioritize high-capacity jack-up and tender rigs for sustained maritime extraction.
In-Depth Regional Review of Active Basins
North American operations heavily leverage mobile double-drum units for frequent onshore workovers. In contrast, offshore-centric regional markets rely on complex maritime logistics. Companies like National Energy Services Reunited Corp. and San Antonio Internacional navigate localized regulatory hurdles to capture high-margin intervention contracts in emerging regional basins.
Strategic Positioning of Leading Companies
Industry leaders utilize distinct strategies to maintain market share. National Oilwell Varco Inc. and Drillmec Drilling Technologies focus on proprietary equipment manufacturing and technological upgrades. Meanwhile, Precision Drilling Corporation and Megha Engineering and Infrastructures Ltd. leverage large, versatile fleets to secure long-term service contracts with major exploration and production firms.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate to high due to numerous competing service providers. Threat of substitutes is low given the specialized nature of well intervention. Supplier power stays constrained by specialized steel and automation component availability, while industry rivalry remains fierce among established tier-one contractors.
SWOT Analysis of the Workover Rigs Sector
Strengths include robust technological advancements and high asset durability. Weaknesses involve high maintenance costs and cyclical exposure. Opportunities emerge from aging offshore platforms requiring plug-and-abandonment or workovers. Threats stem from strict environmental mandates and rapid shifts toward alternative energy sources.
Value Chain Analysis: From Raw Materials to End-Users
The value chain begins with specialized raw material suppliers providing high-grade steel and hydraulic components. Manufacturers like Hubei Petrokh Machine Manufacturing Co. Ltd. fabricate rig structures. Service providers then operate the units, ultimately delivering intervention services to upstream oil and gas operators managing producing reservoirs.
Investment Insights and High-Potential Areas
Investors should target fleets equipped with advanced automation and high horsepower capacity exceeding 1,500 HP. Strategic investments in digital integration yield higher utilization rates. Companies focused on brownfield asset rejuvenation in stable regulatory jurisdictions present the most compelling risk-adjusted return profiles.
Conclusion and Key Takeaways for Industry Stakeholders
The Workover Rigs Market offers solid growth prospects, expanding to $8.61 Billion by 2033. Success requires embracing technological upgrades, navigating complex environmental regulations, and aligning fleet capabilities with the rising demand for deepwater and high-capacity intervention solutions.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining maritime trade registry data, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators. Proprietary econometric models reconcile conflicting data points to ensure an accurate portrayal of market revenues and volume shipments.
Scope of the Report and Coverage Parameters
This report covers global deployment parameters across onshore and offshore environments. Limitations include unforeseen geopolitical disruptions and sudden macroeconomic shifts that could alter baseline crude pricing assumptions underpinning our multi-year forecast models.
Recent Developments: Strategic Moves and Partnerships
Recent market activity highlights a wave of strategic acquisitions and greenfield technology deployments. Firms like KLX Energy Services Holdings Inc. and Twin Eagle Transport LLC have formed targeted operational alliances to streamline supply chain logistics and enhance rapid-response well servicing capabilities across major shale plays.