What is the Fire Protection System Pipes Market scope and industry significance?
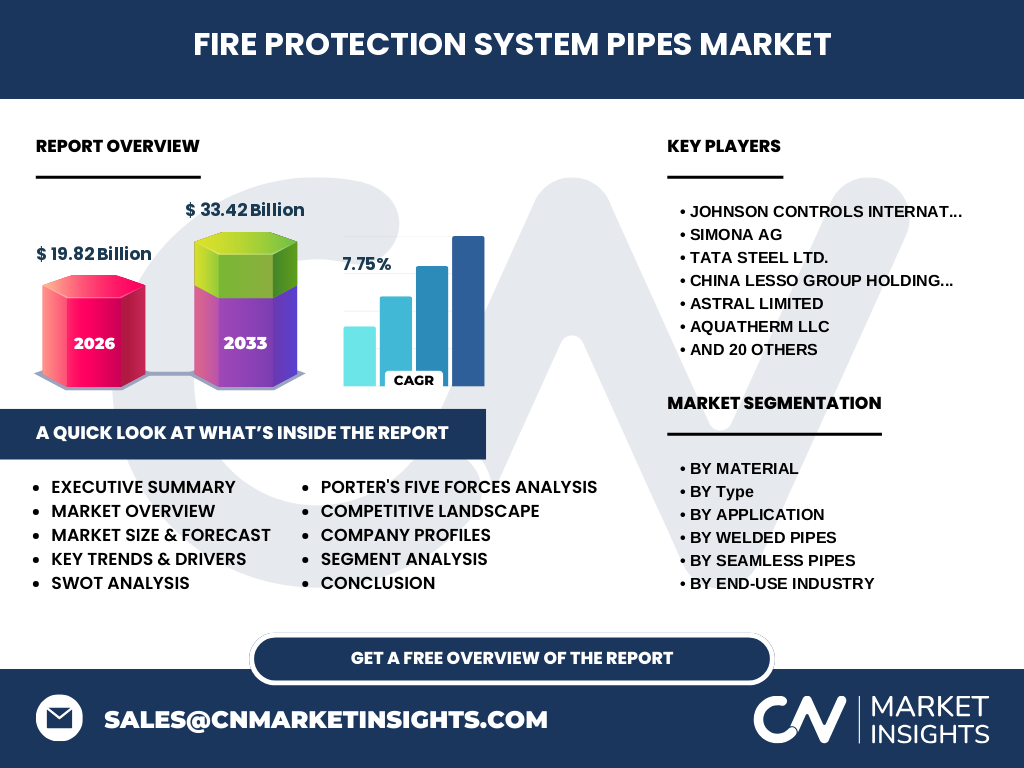
Our analysis indicates that the Fire Protection System Pipes Market represents a critical infrastructure segment valued at $19.82 Billion in 2026. This sector encompasses specialized piping networks engineered to comply with stringent National Fire Protection Association (NFPA) standards, safeguarding high-rise commercial buildings and heavy industrial plants against catastrophic failure.
Key market drivers, restraints, challenges, and opportunities shaping Fire Protection System Pipes Market
Stringent urban building codes and rising investments in smart infrastructure act as primary catalysts for the Fire Protection System Pipes Market industry trends. However, volatile raw material costs for carbon and stainless steel present ongoing margin pressures, while the accelerating adoption of CPVC piping creates high-margin expansion opportunities.
Emerging trends and growth patterns in Fire Protection System Pipes Market
The shift toward pre-fabricated modular piping assemblies is transforming project execution. Based on our research, major fabricators like Ferguson Fire & Fabrication Inc. are leveraging these innovations to reduce on-site installation timelines, directly addressing skilled labor shortages in commercial construction.
COVID-19 impact analysis on Fire Protection System Pipes Market and recovery trajectory
Pandemic-induced supply chain disruptions and temporary construction halts temporarily stalled the Fire Protection System Pipes Market analysis. The subsequent recovery trajectory has been robust, fueled by post-pandemic stimulus packages targeting healthcare and industrial infrastructure modernization across global supply hubs.
Competitive landscape, major players, market concentration, and strategic dynamics
The market features a moderately consolidated landscape where giants like Johnson Controls International plc and Tata Steel Ltd. leverage extensive global distribution networks. Strategic mergers and localized manufacturing acquisitions remain core tactics for tier-1 suppliers defending their market share.
Executive summary of key findings about Fire Protection System Pipes Market
Driven by robust urbanization and stricter life-safety regulations, the Fire Protection System Pipes Market market size is poised for substantial expansion. Industry participants must prioritize lightweight alloy innovations and corrosion-resistant materials to capture emerging demand across industrial end-users.
Market forecast from 2027 to 2033
Our projections show the market expanding from $19.82 Billion in 2026 to reach $33.42 Billion by 2033, expanding at a notable CAGR of 7.75%. This trajectory reflects sustained global investments in commercial and industrial fire suppression retrofits.
Segmentation analysis of the Fire Protection System Pipes Market
Segmentation is categorized by material (Steel, CPVC, Copper, Other), type (Seamless and Welded pipes), application (Fire Suppression and Sprinkler systems), and end-use industry. Steel and CPVC dominate material demand due to their high tensile strength and chemical resistance.
Regional market analysis and geographic distribution
Geographic performance highlights North America and Asia-Pacific as primary revenue generators. Rapid industrialization in developing Asian economies, combined with strict OSHA and NFPA mandates in North America, drives localized manufacturing investments by firms such as China Lesso Group Holdings Ltd.
In-depth regional review of key markets
North America remains a dominant revenue pool driven by mandatory retrofitting of aging commercial infrastructure. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, supported by massive high-rise real estate developments in urban centers requiring advanced fire suppression piping.
Company profiles and strategic positioning of leading firms
Market leaders such as Victaulic and Zekelman Industries differentiate themselves through proprietary mechanical joining technologies and high-grade carbon steel production. Meanwhile, Astral Limited and Simona AG focus heavily on advancing CPVC piping formulations for high-temperature resilience.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers is moderate due to fluctuating steel and resin commodity prices. Threat of substitutes remains low given strict life-safety certification requirements, though intense rivalry among established fabricators like Minimax GmbH presses profit margins.
SWOT analysis of the Fire Protection System Pipes Market
Strengths include high structural integrity and compliance with global safety standards. Weaknesses involve high initial capital expenditure for specialized alloy installations. Opportunities lie in smart building integrations, while threats stem from counterfeit lower-grade piping materials entering developing markets.
Value chain analysis from raw materials to end-users
The value chain originates with raw material extraction—such as iron ore and petrochemical resins—processed by mill operators like Tata Steel Ltd. These are transformed by specialized fabricators and distributed through specialized channels to commercial and residential contractors.
Investment insights and strategic recommendations
Investors should target manufacturers specializing in corrosion-resistant alloy solutions and pre-fabricated modular systems. Companies focusing on sustainable, recyclable CPVC and steel manufacturing processes present high-potential opportunities for long-term equity growth.
Conclusion and key takeaways
The Fire Protection System Pipes Market demonstrates exceptional resilience and growth potential. Stakeholders must align their product portfolios with stringent fire safety regulations and embrace lightweight, corrosion-resistant piping innovations to secure long-term market dominance.
Research methodology for baseline estimations
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with executives at firms like Mueller Industries Inc. and The Viking Corporation, and secondary macroeconomic indicators from global construction indices.
Scope of the report and coverage parameters
This report covers global revenue estimations, volume shipments, and strategic landscape evaluations from 2026 through 2033. Macroeconomic disruptions, localized trade policies, and material-specific cost variances are factored into all quantitative forecasting models.
Recent developments in company announcements and partnerships
Recent industry momentum highlights strategic joint ventures and capacity expansions. Firms such as Jindal Industries Pvt. Ltd. have ramped up high-frequency welded tube production lines to meet surging demand for certified commercial fire sprinkler infrastructure.