What is the scope and industry significance of the Metal Alloys Market?
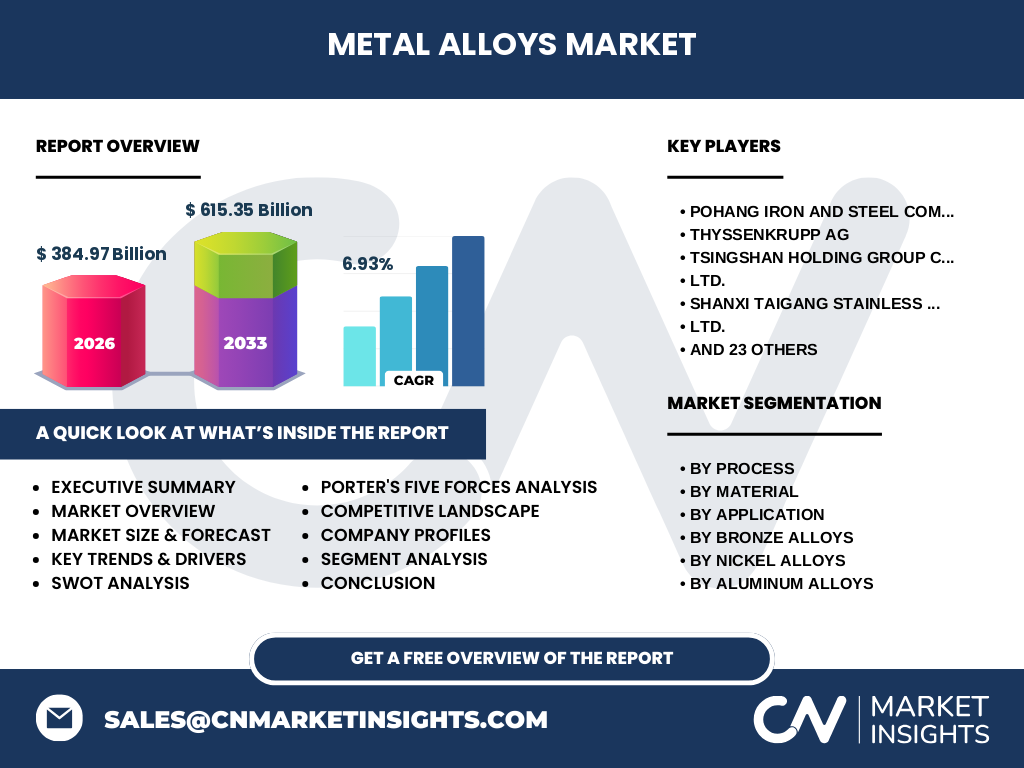
Our analysis indicates that the Metal Alloys Market represents a foundational pillar for global manufacturing, valued at 384.97 Billion in 2026. This sector encompasses advanced material formulations like Stainless Steel Alloys, Aluminum Alloys, and Nickel Alloys, serving critical infrastructure, aerospace, and industrial applications globally.
Key market drivers, restraints, challenges, and opportunities shaping the Metal Alloys Market
Structural growth is propelled by escalating demand in transportation and construction sectors. However, supply chain bottlenecks for raw materials like nickel and bauxite remain significant restraints. Strategic opportunities emerge in lightweighting initiatives, forcing mills to innovate advanced casting and rolling techniques to maintain competitive advantage.
The Shift Toward Advanced Material Performance
Industry trends reveal a pronounced migration toward specialized nickel-chromium alloys like Inconel and wrought aluminum variants. Based on our research, end-users increasingly demand high-entropy formulations capable of withstanding extreme thermal stress, directly benefiting technology innovators such as QuesTek Innovations LLC and ATI Specialty Alloys & Components.
COVID-19 impact analysis and recovery trajectory for the Metal Alloys Market
The pandemic caused severe supply chain disruptions and temporary shutdowns across major metallurgical hubs. The subsequent recovery trajectory has been robust, driven by fiscal stimulus packages targeting green infrastructure and an aggressive rebound in automotive and machinery manufacturing activity across North America and Asia-Pacific.
Competitive Benchmarking and Market Concentration
The competitive landscape is characterized by intense rivalry among multinational producers such as Thyssenkrupp AG, Pohang Iron and Steel Company, and United Company RUSAL plc. Market concentration remains moderate to high, with major players leveraging backward integration and strategic acquisitions to secure raw material supply and pricing power.
Executive summary of key findings in the Metal Alloys Market
Our comprehensive evaluation projects the Metal Alloys Market to reach 615.35 Billion by 2033, expanding at a robust 6.93% CAGR from 2027. Growth is anchored by technological advancements in casting and hot-rolling processes, alongside surging demand for corrosion-resistant stainless steel and high-performance bronze alloys.
Market forecast trajectory from 2027 to 2033
The data suggests sustained upward momentum, scaling the market from its 2026 baseline of 384.97 Billion to 615.35 Billion by 2033. This trajectory reflects a steady 6.93% CAGR, underpinned by rising industrialization in emerging economies and stringent regulatory mandates favoring durable, recyclable metallic materials.
Segmentation analysis across processes, materials, and applications
Segmentation is categorized by Process (Casting, Hot and Cold Rolling), Material (Stainless Steel, Aluminum, Bronze, Nickel Alloys), and Application (Transportation, Construction, Machinery). Each tier plays a vital role, with austenitic stainless steel and wrought aluminum dominating volume consumption across global industrial ecosystems.
Regional market analysis and geographic performance
Geographic distribution highlights Asia-Pacific as the undisputed volume leader, driven by heavy industrial output in China and South Korea through titans like Baosteel and POSCO. Meanwhile, North America and Europe prioritize high-value specialty alloys for aerospace and defense, supported by strict localized quality standards and environmental regulations.
In-depth regional review of manufacturing hubs and logistical nodes
Regional performance is heavily anchored by access to major maritime ports and localized raw material reserves. Industrial clusters in East Asia leverage proximity to bauxite and nickel deposits, whereas European producers navigate stringent carbon border adjustment mechanisms, impacting operational costs for energy-intensive melting and rolling facilities.
Strategic positioning of leading companies in the Metal Alloys Market
Industry leaders maintain distinct strategic moats. Aperam S.A. and Acerinox S.A. focus on high-grade stainless steel efficiency, while Carpenter Technology Corporation and Haynes International Inc. specialize in proprietary superalloys. VSMPO-AVISMA dominates titanium-aluminum synergies for aerospace, cementing critical tier-1 supplier relationships worldwide.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to the commoditized nature of base metals like nickel and aluminum, though constrained by geopolitical trade policies. Buyer power is high among automotive OEMs, while threat of substitution is mitigated by continuous metallurgical innovations yielding superior alloy strength-to-weight ratios.
SWOT analysis of the global alloy ecosystem
Key strengths include established global supply chains and advanced metallurgical expertise. Weaknesses involve high energy dependency. Opportunities lie in electric vehicle lightweighting and renewable energy infrastructure. Threats stem from volatile raw material pricing and stringent environmental compliance mandates.
Value chain analysis from raw materials to end-users
The value chain initiates with mining raw ores like nickel, chromium, and bauxite, transitioning through smelting, alloying, and primary processing via casting or rolling. Mid-stream fabricators shape these materials into components for downstream transportation and construction end-users, capturing significant margin via specialized thermal treatments.
Investment insights and high-potential areas
High-potential investment avenues target advanced nickel-chromium superalloys and cast aluminum components tailored for electric mobility. Based on our research, capital allocation toward eco-friendly electric arc furnace recycling technologies yields superior long-term ROI as carbon taxation regimes expand globally.
Conclusion and strategic takeaways for industry stakeholders
The Metal Alloys Market offers compelling growth, projected to hit 615.35 Billion by 2033. Stakeholders must prioritize operational decarbonization, digital supply chain transparency, and R&D in high-performance alloy variants to capture expanding market share amid evolving industrial demands.
Research methodology for baseline estimation and data triangulation
Baseline estimates are meticulously triangulated by synthesizing primary stakeholder interviews with c-suite executives, secondary trade registry data from customs authorities, and macroeconomic indicators. Bottom-up volumetric aggregation is cross-verified with top-down revenue models to ensure high fidelity across all segments.
Scope of the report and coverage parameters
This report covers global market dynamics for the Metal Alloys Market from 2026 through 2033, evaluating specific material grades, manufacturing processes, and end-user applications. Limitations include unforeseen geopolitical trade embargoes and sudden macroeconomic shifts impacting primary metal commodity pricing.
Recent developments, partnerships, and strategic moves
Recent industry momentum features aggressive capacity expansions by Tsingshan Holding Group and joint ventures focused on green steel production. Companies like MetalTek International and Materion Corporation continue to invest in proprietary alloy formulations to meet tightening aerospace and defense specifications.