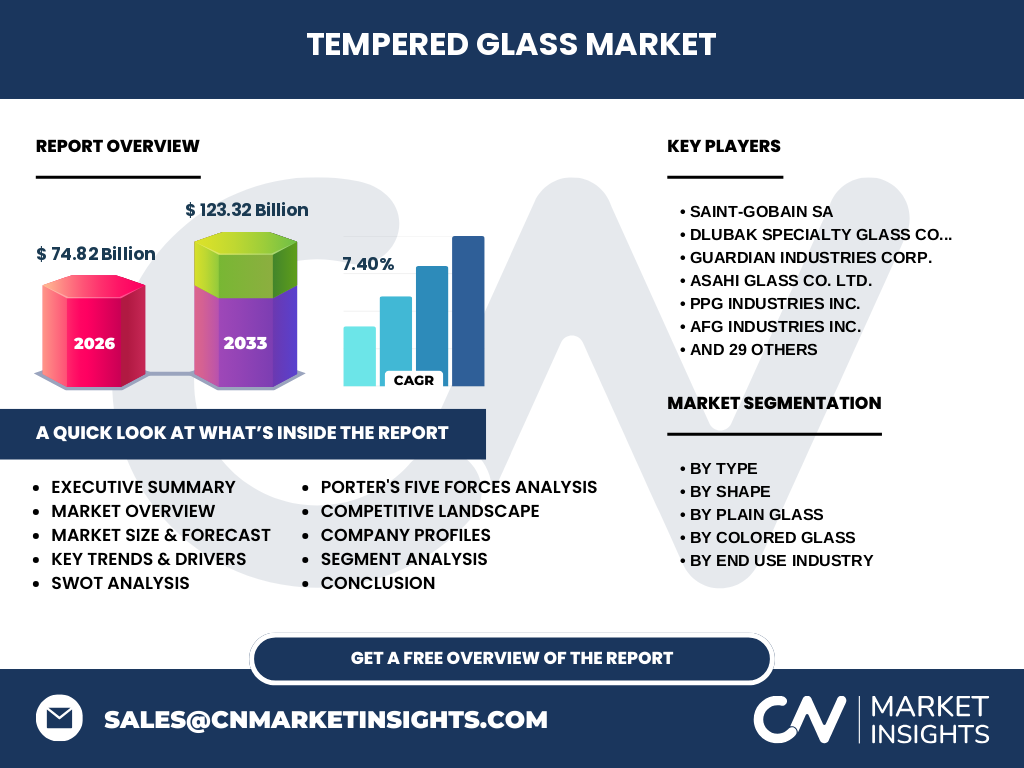
Market overview of the Tempered Glass Market
The Tempered Glass Market evaluates thermal and chemical toughening processes applied to raw float glass. Valued at $74.82 Billion in 2026, this sector underpins safety requirements in architecture and automotive manufacturing by inducing surface compressive stresses.
Key market drivers, restraints, challenges, and opportunities shaping Tempered Glass Market
Strict safety mandates from regulatory bodies like the Department of Transportation act as core drivers. Conversely, high energy intensity during thermal tempering poses cost restraints, while opportunities thrive in developing lightweight photovoltaic encasements.
Emerging trends and growth patterns in Tempered Glass Market
Industry trends highlight a surge in demand for low iron tempered glass to maximize solar transmittance in clean energy installations, shifting fabrication hubs toward automated optical inspection.
COVID-19 impact analysis on the Tempered Glass Market
Pandemic-induced supply chain fractures temporarily stalled construction pipelines. However, rapid post-pandemic recovery across automotive assembly plants propelled a robust rebound for major fabricators like Saint-Gobain SA and Fuyao Glass.
Competitive landscape of the Tempered Glass Market
The market features high consolidation among tier-one producers such as Guardian Industries Corp. and Asahi Glass Co. Ltd., competing through proprietary coatings and localized tempering facilities.
Executive summary of key findings for the Tempered Glass Market
Our analysis projects the Tempered Glass Market to surge from $74.82 Billion in 2026 to $123.32 Billion by 2033 at a CAGR of 7.40%, driven by urbanization and safety compliance.
Market forecast from 2027 to 2033
Propelling forward at a 7.40% CAGR, the sector will expand from its 2026 baseline to hit $123.32 Billion by 2033, heavily supported by infrastructure buildouts across emerging economies.
Segmentation analysis by type, shape, and end use industry
Segmentation spans Plain Glass and Colored Glass categories, further divided by Flat and Bent Tempered Glass configurations, serving high-growth pillars in automotive and construction.
Regional market analysis and geographic distribution
Geographic performance shows Asia-Pacific dominating volume consumption owing to massive automotive manufacturing hubs in China and Japan, while North America prioritizes high-performance architectural safety glazing.
In-depth regional review of the Tempered Glass Market
Regional momentum centers on rapid urbanization in developing Asian markets, where players like Xinyi Glass Holdings Limited leverage local silica sand reserves to optimize production economics.
Company profiles and strategic positioning of leading firms
Industry titans like Nippon Sheet Glass Co. Ltd. and Schott AG maintain competitive moats via continuous furnace innovation and strategic partnerships with multinational construction conglomerates.
Porter's Five Forces analysis of competitive pressures
The industry experiences moderate-to-high supplier power due to raw soda ash and silica pricing volatility, alongside intense rivalry among established glass fabricators striving for scale.
SWOT analysis of the Tempered Glass Market
Strengths include exceptional mechanical durability, while weaknesses involve high capital expenditure for tempering kilns. Opportunities lie in smart glass integrations, offset by the threat of alternative polymers.
Value chain analysis from raw materials to end-users
The value chain initiates with silica sand extraction, transitions through float glass formation and precise thermal tempering, and culminates in end-use integration by architectural and automotive assemblers.
Investment insights and high-potential areas
High-potential capital deployment focuses on energy-efficient electric tempering furnaces and automated quality control systems, offering superior operational margins for early adopters.
Conclusion and key takeaways for stakeholders
The Tempered Glass Market represents a robust investment landscape, anchored by a 7.40% CAGR through 2033, where sustainability and high-performance safety glazing dictate market leadership.
Research methodology for baseline estimates
Our findings combine primary interviews with C-level executives across glass manufacturing firms, triangulated against trade registry data, customs records, and macroeconomic construction indices.
Scope of the report and coverage parameters
This report covers global market sizing from 2026 to 2033, analyzing segmentation across clear, low iron, tinted, reflective, and frosted variants while addressing regulatory and logistical hurdles.
Recent developments in the Tempered Glass Market
Recent strategic moves highlight heavy investments in solar-grade low iron lines and joint ventures by companies like Sisecam to expand their European and North American footprint.