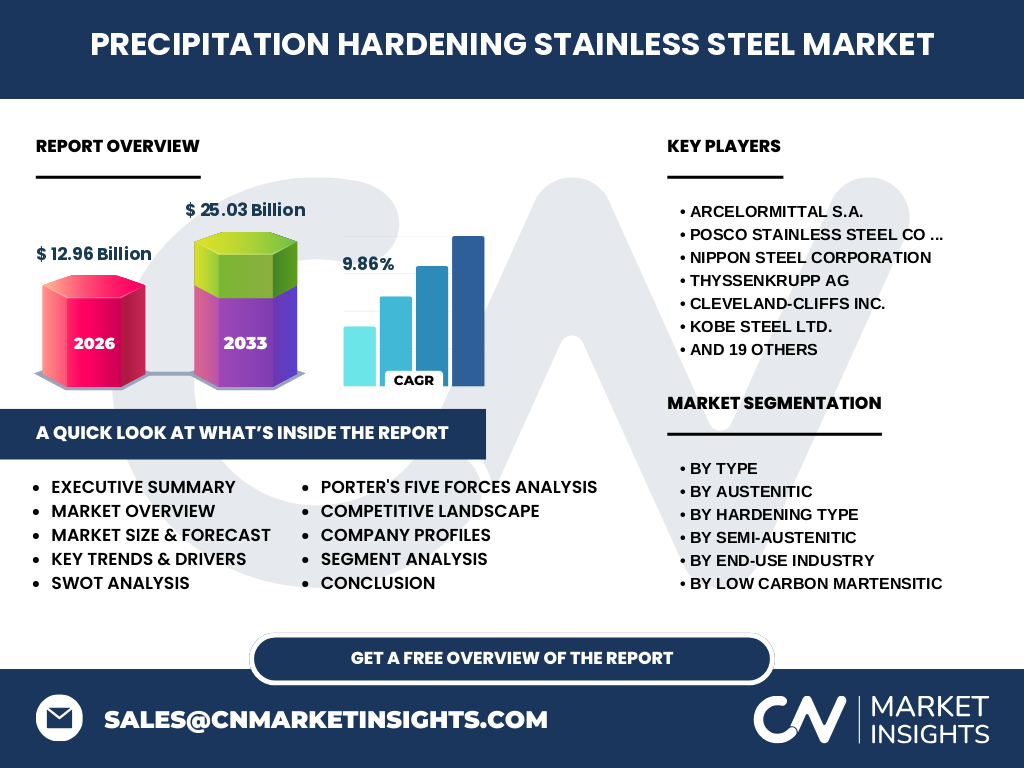
Market overview of the Precipitation Hardening Stainless Steel Market
Our analysis indicates the Precipitation Hardening Stainless Steel Market represents a critical segment of advanced metallurgical engineering, valued at $12.96 Billion in 2026. This sector encompasses specialized high-strength alloys utilized where exceptional mechanical properties, corrosion resistance, and high-temperature performance are mandatory across demanding engineering environments.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Precipitation Hardening Stainless Steel Market?
Growth is propelled by stringent aerospace performance mandates and extreme oil and gas extraction environments. However, supply chain volatility in critical raw materials like nickel and chromium presents ongoing cost pressures. Strategic opportunities lie in developing advanced alloys optimized for additive manufacturing applications governed by ASME and ASTM standards.
Emerging trends and growth patterns in the Precipitation Hardening Stainless Steel Market
The data suggests a strong pivot toward proprietary powder metallurgy and specialized vacuum induction melting processes. Industry leaders like Carpenter Technology Corporation and Allegheny Technologies Incorporated (ATI) are pioneering customized grades that deliver superior fracture toughness, transforming component lifecycles in critical defense and aerospace applications.
How did the COVID-19 pandemic impact the Precipitation Hardening Stainless Steel Market and dictate its recovery trajectory?
Pandemic-induced supply chain disruptions and sudden commercial aviation contractions caused temporary output contractions across primary mills. Recovery has been robustly steered by surging defense budgets and accelerated regionalization of supply chains, with major logistics hubs recovering throughput velocity through automated processing plants.
Competitive Benchmarking in the Precipitation Hardening Stainless Steel Market
Market concentration remains moderately high, anchored by integrated global giants. ArcelorMittal S.A., Nippon Steel Corporation, and Outokumpu Oyj leverage massive scale advantages, whereas specialized providers like Valbruna Stainless Inc. and Böhler Edelstahl GmbH & Co KG compete through niche metallurgical engineering and stringent aerospace certifications.
Executive Summary of the Precipitation Hardening Stainless Steel Market
Our research confirms the Precipitation Hardening Stainless Steel Market industry trends point toward sustained expansion, driven by high-performance industrial applications. The market is projected to reach $25.03 Billion by 2033, expanding at a robust CAGR of 9.86% from 2027, fueled by rising global demand for ultra-durable, corrosion-resistant engineering materials.
Market Forecast and Trajectory through 2033
Based on our econometric modeling, the Precipitation Hardening Stainless Steel Market market size will scale dramatically from its 2026 baseline of $12.96 Billion to achieve $25.03 Billion by 2033. This sustained trajectory reflects a compound annual growth rate of 9.86%, underpinned by multi-year supply agreements in the aerospace and energy sectors.
Segmentation Analysis of the Precipitation Hardening Stainless Steel Market
Our segmentation framework breaks down the market by Type (Low Carbon Martensitic featuring 15-5 PH and 17-4 PH Stainless Steel; Semi-Austenitic featuring PH 13-8 Mo and A-286 Stainless Steel; and Austenitic featuring Alloy 625, Alloy 718, and Alloy 800), Hardening Type (Coherency Strain, Chemical, Dispersion), and End-Use Industries spanning Aerospace, Defense, Automotive, Oil and Gas, and Medical Devices.
Geographic Distribution and Regional Market Analysis
Regional performance highlights distinct industrial priorities. North America dominates consumption due to robust aerospace and defense manufacturing bases, while Asia-Pacific represents the fastest-expanding operational theatre, driven by rapid industrialization, automotive manufacturing expansion in South Korea and Japan, and massive infrastructure investments managed by firms like POSCO Stainless Steel Co Ltd.
In-Depth Regional Review and Localized Constraints
Localized market constraints in Europe involve stringent REACH chemical regulations and high energy costs impacting regional melt shops. Conversely, North American production centers benefit from established scrap recycling networks, though they face skilled labor shortages in specialized heat treatment operations involving providers like Bodycote plc and Paulo Products Company.
Strategic Positioning of Leading Companies in the Precipitation Hardening Stainless Steel Market
Key industry participants deploy distinct competitive plays. Sandvik AB and Thyssenkrupp AG focus on high-integrity tubular and flat products, while service specialists like Bluewater Thermal Solutions LLC and Specialty Steel Treating Inc. provide essential precipitation hardening heat treatment services required to achieve specified mechanical tolerances.
Porter's Five Forces Analysis of Competitive Dynamics
The threat of new entrants remains remarkably low due to massive capital expenditure requirements for vacuum induction melting furnaces and stringent aerospace qualifications like NADCAP. Bargaining power of suppliers is moderate, dictated by raw material price volatility for elements like molybdenum and cobalt, whereas buyer power is constrained by specialized alloy specifications.
SWOT Analysis of the Precipitation Hardening Stainless Steel Sector
Strengths include exceptional strength-to-weight ratios and outstanding corrosion resistance under extreme service conditions. Weaknesses center on high alloy production costs and complex machining requirements. Opportunities abound in next-generation medical implants and clean energy infrastructure, while threats involve substitute engineering plastics and carbon fiber composites.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with primary raw material extraction of iron ore, chromium, nickel, and specialty additives. This flows through electric arc furnace melting, continuous casting, and hot/cold rolling executed by primary producers like Jindal Stainless Limited and Aperam S.A., culminating in precision thermal processing by treaters like Wallwork Heat Treatment Ltd prior to end-user deployment.
Investment Insights and High-Potential Areas
Strategic recommendations highlight high-potential investment in secondary processing facilities and powder metallurgy production lines tailored for additive manufacturing. Investors should prioritize partnerships with tier-1 aerospace suppliers and certified heat treaters like Pacific Metallurgical Inc. and Tokushu Kinzoku Excel Co Ltd. to capture high-margin component manufacturing contracts.
Conclusion and Key Takeaways for Market Stakeholders
The Precipitation Hardening Stainless Steel Market analysis proves that technical innovation and strict quality compliance remain the primary determinates of market leadership. With a projected expansion to $25.03 Billion by 2033, stakeholders must invest in advanced metallurgical capabilities to capitalize on high-growth defense, aerospace, and energy transition verticals.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by synthesizing proprietary trade registry data, primary stakeholder interviews with C-level metallurgical engineers, and secondary macroeconomic indicators from international trade bodies. This multi-tiered research approach ensures high statistical fidelity and reliable market sizing across all tracked segments and regions.
Scope of the Report and Coverage Parameters
This comprehensive report covers global market dynamics, volume shipments, and revenue projections from 2027 through 2033, using 2026 as the foundational base year of $12.96 Billion. Geographic parameters encompass North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa, with specific evaluations of regulatory compliance and raw material logistics.
Recent Developments, Strategic Partnerships, and M&A Activity
Recent strategic moves feature aggressive capacity expansions and long-term supply agreements. Major players such as Daido Steel Co Ltd., Cleveland-Cliffs Inc., and Hunan Fushun Metal Co Ltd. have intensified joint ventures focused on green-steel production methodologies and localized aerospace distribution hubs to mitigate global freight disruptions and satisfy strict carbon reduction mandates.