What is the scope and industry significance of the Classroom Management Systems Market?
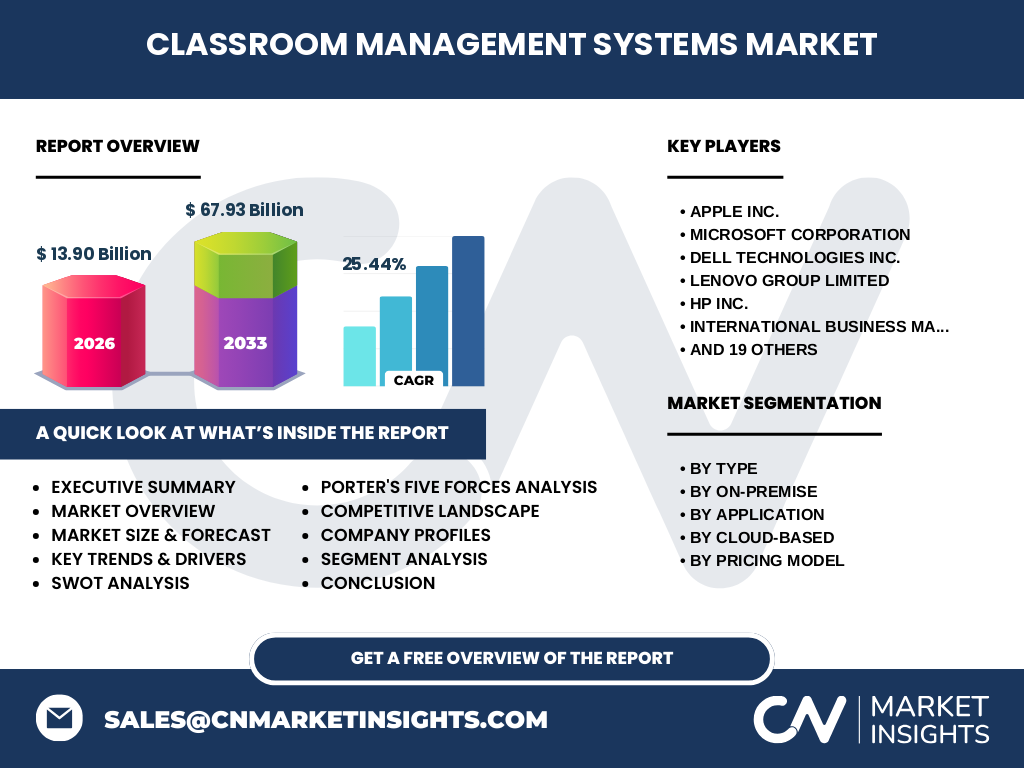
Our analysis indicates that the Classroom Management Systems Market encompasses specialized software and hardware deployment frameworks designed to streamline instructor-student interactions. Valued at 13.90 Billion in 2026, the industry underpins modern educational infrastructure, heavily influenced by strict regulatory compliance like FERPA and COPPA regarding student data privacy.
What are the core structural growth drivers and challenges shaping this market?
The market is heavily propelled by accelerating digitalization across global academic institutions. However, severe budgetary constraints in public K-12 districts and persistent cybersecurity vulnerabilities regarding localized server deployments act as primary restraints. Educational technology leaders must navigate complex administrative compliance hurdles while scaling cloud-based infrastructures.
Emerging trends and growth patterns in Classroom Management Systems Market
The data suggests a massive pivot toward SaaS solutions and mobile cloud applications. Institutions increasingly demand real-time analytics and AI-driven behavioral tracking to optimize remote and hybrid learning environments, favoring agile technology providers over legacy on-premise setups.
How did COVID-19 impact the Classroom Management Systems Market trajectory?
The pandemic served as an unprecedented catalyst, forcing immediate emergency remote learning adoption. This disruption permanently altered institutional spending priorities, transitioning Classroom Management Systems Market industry trends from optional auxiliary tools to mission-critical operational necessities with sustained post-pandemic recovery growth.
Competitive Benchmarking: Major players and strategic market dynamics
The competitive landscape features a mix of hardware giants like Apple Inc., Microsoft Corporation, and Google alongside specialized ed-tech firms like Blackboard Inc. and ClassDojo Inc. Companies leverage strategic acquisitions and ecosystem lock-in to capture high-margin institutional contracts.
Executive Summary of Classroom Management Systems Market findings
Our comprehensive research projects the Classroom Management Systems Market to reach 67.93 Billion by 2033, expanding at a robust CAGR of 25.44% from 2027. This explosive trajectory is heavily driven by higher education digital transformation and cloud infrastructure investments.
Market Forecast and Trajectory from 2027 to 2033
Starting from a baseline of 13.90 Billion in 2026, the market will scale rapidly to 67.93 Billion by 2033. This remarkable 25.44% CAGR reflects accelerated institutional transition toward subscription-based cloud platforms and integrated K-12 virtual ecosystems.
Segmentation Analysis of Classroom Management Systems Market
The market is segmented by type into On-Premise (Standalone Software, Integrated Solutions, Local Server, Self-Hosted) and Cloud-Based (SaaS, PaaS, Hybrid, LMS, Mobile). Application segments split into K-12 and Higher Education, while pricing relies on One-Time and Subscription models.
Geographic Distribution and Regional Performance Overview
Regional performance varies significantly, with North America leading due to early cloud adoption and high IT spending in educational institutions. Meanwhile, Asia-Pacific represents the fastest-growing regional market, propelled by government-led digital literacy initiatives in densely populated developing economies.
In-Depth Regional Review of Classroom Management Systems Market
North America dominates market revenue share, anchored by robust enterprise partnerships involving firms like Cisco Systems Inc. and Dell Technologies Inc. Conversely, the European market prioritizes stringent data sovereignty regulations, heavily favoring localized hybrid cloud deployments and secure LMS integrations.
Company Profiles and Strategic Positioning
Industry leaders maintain distinct strategic moats. Pearson plc and McGraw Hill Education Inc. focus on content-integrated platforms, whereas infrastructure providers like Lenovo Group Limited and HP Inc. bundle management software directly with hardware shipments to secure institutional dominance.
Porter's Five Forces Analysis of the Industry
Bargaining power of buyers is moderately high due to competitive RFPs from school boards. However, high switching costs for integrated cloud-based learning management systems mitigate supplier power and reduce overall industry churn rates significantly.
SWOT Analysis: Internal Strengths and External Realities
Key strengths include high scalability of SaaS models and essential utility during remote learning. Weaknesses involve high initial integration costs. Opportunities lie in emerging AI tutoring integrations, while threats stem from rising cybersecurity threats targeting student databases.
Value Chain Analysis from Development to End-Users
The value chain flows from foundational software development and cloud hosting infrastructure providers to system integrators, ultimately reaching institutional end-users like K-12 districts and universities via specialized deployment and training partners.
Investment Insights and High-Potential Areas
Investors should target cloud-native SaaS platforms and mobile application developers specializing in accessibility compliance. Companies integrating automated assessment and behavioral analytics present the highest risk-adjusted return potential over the forecast period.
Conclusion and Key Takeaways for Industry Stakeholders
The Classroom Management Systems Market represents a highly lucrative sector projected to hit 67.93 Billion by 2033. Stakeholders must prioritize cloud scalability, strict regulatory compliance, and seamless LMS integration to capture expanding market share.
Research Methodology for Classroom Management Systems Market Analysis
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with ed-tech CTOs, secondary macroeconomic indicators from global education ministries, and verified trade registry data regarding enterprise software deployments and institutional procurement budgets.
Scope of the Report and Coverage Parameters
This report covers global revenue estimations from 2026 to 2033, evaluating hardware-bundled and standalone software deployments. Limitations include varying regional public school funding cycles and undocumented localized open-source classroom tool adoption.
Recent Developments and Strategic Industry Moves
Recent market activity highlights aggressive partnerships, such as Adobe Inc. and D2L Corporation integrating creative multimedia tools into enterprise LMS frameworks. Competitors like Absorb Software Inc. have launched AI-driven administrative automation features to capture shifting institutional demand.