What is the scope and industry significance of the Vanadium Market?
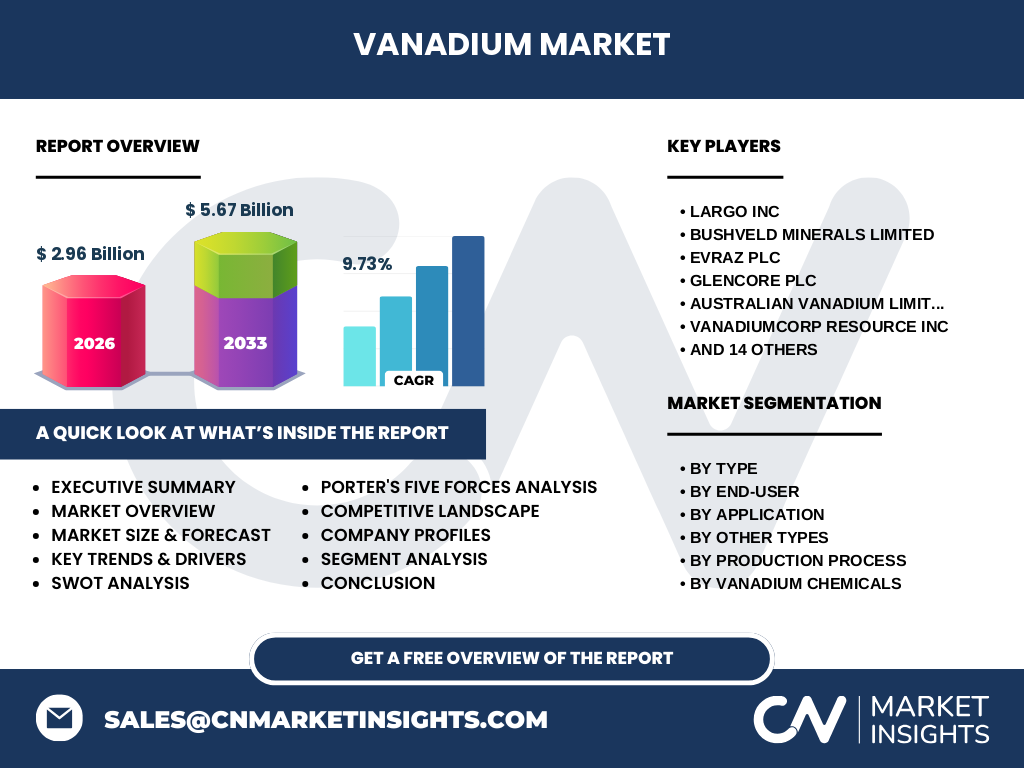
Our analysis indicates the Vanadium Market size is valued at $2.96 Billion in 2026, driven by critical requirements in high-strength low-alloy steel and emerging energy storage applications. This proprietary assessment establishes the industry significance of vanadium across metallurgical, chemical, and advanced battery sectors globally.
Structural Growth Drivers and Market Restraints
The market is propelled by expanding infrastructure investments and grid-scale vanadium redox flow batteries (VRFBs). Conversely, strict environmental regulations governing the extraction of titaniferous magnetite ores and volatile processing costs for Vanadium Pentoxide act as notable restraints, limiting rapid supply expansions.
Emerging Industry Trends in the Vanadium Market
A definitive shift toward clean energy storage has elevated the commercial profile of Vanadyl Sulfate and Vanadium Chloride chemicals. Industry participants are increasingly prioritizing green extraction techniques to meet stringent carbon-reduction mandates enforced by regulatory bodies across key manufacturing hubs.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic induced severe supply chain disruptions and logistical bottlenecks across primary ports, temporarily depressing demand from automotive and aerospace end-users. Recovery has been robustly spearheaded by government-backed stimulus packages focusing on green energy transitions and critical mineral supply security.
Competitive Benchmarking and Market Concentration
Industry leadership is consolidated among major players like Largo Inc, Bushveld Minerals Limited, and EVRAZ plc, who leverage large-scale mining assets. These established entities compete with agile developers like Australian Vanadium Limited and Vecco Group through integrated supply chains.
Executive Summary of the Vanadium Market
Our comprehensive overview forecasts the Vanadium Market to surge from $2.96 Billion in 2026 to $5.67 Billion by 2033 at a CAGR of 9.73%. This exceptional trajectory underscores the metal's indispensable role in global decarbonization and high-performance steel manufacturing.
Vanadium Market Forecast (2027 to 2033)
Projected growth from 2027 to 2033 will achieve a steady CAGR of 9.73%, catapulting total valuation to $5.67 Billion. This expansion is underpinned by surging demand for Ferrovanadium in high-strength structural steels and massive deployment of energy storage systems.
Segmentation Analysis Across Types and End-Users
The market is segmented by type into Vanadium Pentoxide, Ferrovanadium, Aluminum-Vanadium Alloys, and Vanadium Chemicals. End-user applications span automotive, chemical, and energy storage sectors, with Iron and Steel dominating consumption via the metallurgical grade segment.
Geographic Distribution and Regional Performance
Asia-Pacific dominates the global consumption landscape due to intensive steel production in China, supported by dominant players like Pangang Group Vanadium Titanium & Resources Co Ltd. Meanwhile, North America and Europe focus heavily on securing domestic supply chains for critical energy storage applications.
In-Depth Regional Review of Key Markets
In North America, projects spearheaded by firms like Energy Fuels Inc and Western Uranium & Vanadium Corp highlight regional efforts to mitigate import dependencies. Concurrently, Australian developers such as TNG Limited and Golden Deeps Ltd are unlocking high-grade deposits to supply international markets.
Strategic Positioning of Leading Companies
Market giants like Glencore plc control vast global distribution networks, while specialized miners such as Ferro‑Alloy Resources Limited and VanadiumCorp Resource Inc focus on proprietary extraction technologies. This dynamic creates a multi-layered competitive environment balancing scale with technological innovation.
Porter's Five Forces Analysis of the Industry
Bargaining power of suppliers remains moderate due to geographically concentrated high-grade deposits, while the threat of substitution in energy storage is mitigated by the unique long-duration cyclic stability of Vanadium Redox Flow Batteries. Competitive rivalry is intense among established multinational mining conglomerates.
SWOT Analysis of the Vanadium Sector
Key strengths include high tensile strength contributions to steel and superior energy storage metrics. Weaknesses involve complex, capital-intensive refining processes. Opportunities lie in the renewable energy boom, while threats stem from potential technological shifts in alternative battery chemistries.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from extraction of titaniferous magnetite and secondary residues through roasting and smelting to produce Chemical Grade and Metallurgical Grade Vanadium Pentoxide, ultimately feeding downstream alloy manufacturers and energy storage system integrators.
Investment Insights and High-Potential Areas
High-potential investment avenues concentrate on localized processing facilities utilizing the Aluminothermic Reduction Technique and silicon reduction processes. Investors are advised to target integrated developers possessing both mining tenements and downstream electrolyte production capabilities.
Conclusion and Key Takeaways
The Vanadium Market represents a high-growth sector bridging traditional metallurgy with next-generation clean energy infrastructure. Achieving a market size of $5.67 Billion by 2033, it offers robust opportunities for strategic stakeholders navigating regulatory and supply complexities.
Research Methodology for Baseline Estimates
Our rigorous research methodology triangulates data by combining exhaustive trade registry statistics, primary stakeholder interviews with executives from Strategic Resources and Critical Metals Ltd, and secondary macroeconomic indicators to establish reliable baseline estimates.
Scope of the Report and Coverage Parameters
This report encompasses a detailed global assessment of the Vanadium Market industry trends, covering segments such as Low-Vanadium Ferrovanadium, High-Vanadium Ferrovanadium, and specific chemical derivatives from 2026 through 2033, while acknowledging geopolitical and macroeconomic constraints.
Recent Developments and Strategic Industry Moves
Recent milestones feature strategic joint ventures, plant expansions, and advanced technological rollouts by innovators like Voyager Metals Inc and Ioneer Ltd. These corporate maneuvers reflect an aggressive industry-wide push to secure long-term offtake agreements and optimize processing efficiencies.