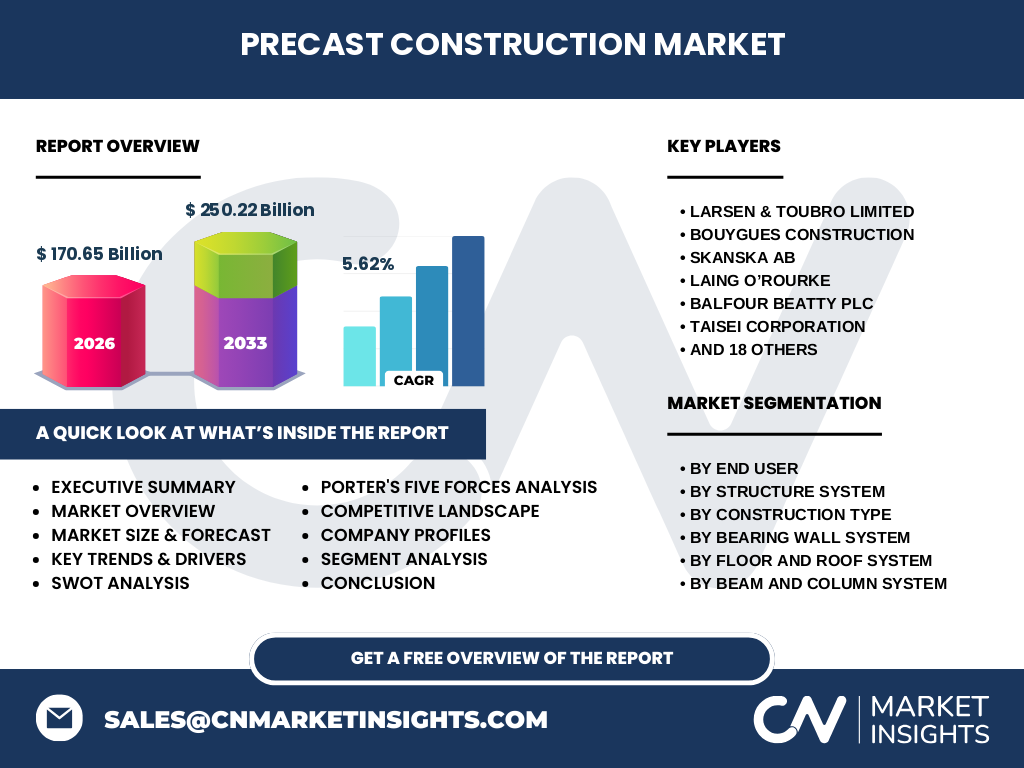
What is the Precast Construction Market overview and its current economic significance?
Our analysis indicates the Precast Construction Market reaches 170.65 Billion in 2026, driven by off-site manufacturing efficiencies. Regulatory bodies like the Precast/Prestressed Concrete Institute shape standards, optimizing raw materials such as Portland cement and reinforcing steel for accelerated urban infrastructure deployment.
Key market drivers, restraints, challenges, and opportunities shaping Precast Construction Market
Labor shortages and stringent OSHA safety mandates act as primary drivers, pushing developers toward factory-controlled precast production. However, high initial capital expenditures for heavy lifting logistics remain a restraint. Opportunities abound in sustainable sandwich panels and insulated walls that meet strict energy efficiency codes.
Emerging trends and growth patterns in Precast Construction Market
The shift toward automated BIM-integrated batching plants is revolutionizing manufacturing precision. Industry innovators like Oldcastle Infrastructure and Tindall Corporation leverage digital tracking for hollow core slabs, significantly reducing onsite material waste across complex megaprojects.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced supply chain disruptions and port congestion temporarily stalled modular assembly schedules. The subsequent recovery trajectory highlights a robust rebound, as contractors prioritize precast concrete walls to minimize onsite worker density and accelerate project timelines post-pandemic.
Competitive Benchmarking: Major players and strategic dynamics
Market concentration features a mix of global engineering giants and specialized precast fabricators. Firms like Larsen & Toubro Limited and Bouygues Construction utilize vertically integrated supply chains, securing a competitive edge in executing large-scale institutional and transportation frameworks.
Executive summary of key findings
Based on our research, the Precast Construction Market is poised for accelerated expansion, moving from 170.65 Billion in 2026 to 250.22 Billion by 2033 at a 5.62% CAGR. Strategic investments in modular manufacturing will dictate future industry leadership.
Market forecast: Projected growth from 2027 to 2033
The data suggests the sector will expand robustly at a 5.62% CAGR, scaling the valuation from 170.65 Billion to 250.22 Billion by 2033. This trajectory reflects increasing municipal demand for durable beam and column systems in seismic zones.
Segmentation analysis of structural systems and end users
Our analysis categorizes the market by end user into Residential and Non-residential sectors. Structure systems are further divided into Beam & Column System, Floor & Roof System, and Bearing Wall System, catering to diverse structural load requirements.
Regional market analysis and geographic distribution
Geographic performance varies significantly based on localized seismic codes and urbanization rates. North America and Europe demonstrate mature demand for precast roof panels, while emerging economies in Asia-Pacific show rapid adoption of modular manufactured homes to address housing deficits.
In-depth regional review of high-growth territories
Regional momentum is heavily concentrated in urban centers requiring rapid transit infrastructure. Compliance with Eurocode standards in Europe and ACI guidelines in North America dictates localized production tolerances for precast frames and insulated walls.
Company profiles and strategic positioning of leading innovators
Market leaders strategically position themselves through localized batching plants and strategic acquisitions. Companies like Skanska AB, Laing O’Rourke, and Jensen Precast utilize advanced casting technology to dominate regional infrastructure and commercial supply contracts.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers is moderate due to standardized raw material inputs like cement and aggregates. Threat of new entrants remains low, constrained by high capital outlays required for heavy transport fleets and specialized crane equipment.
SWOT analysis of the Precast Construction Market
Key strengths include superior quality control and reduced weather-related delays. Weaknesses involve high logistical costs for oversized components. Opportunities lie in green concrete formulations, while threats stem from volatile steel pricing and complex municipal permitting delays.
Value chain analysis from raw materials to end-users
The value chain flows from raw aggregate extraction and cement production to computerized batching, curing, and precision transport. Specialized logistics providers ensure structural precast beams reach congested urban job sites safely without compromising structural integrity.
Investment insights and high-potential areas
High-potential investment areas center around automated precast hollow core slab production and proprietary insulation composite panels. Investors should target regional fabricators exhibiting strong balance sheets and established municipal supply agreements.
Conclusion and key takeaways for industry stakeholders
The Precast Construction Market offers compelling long-term growth, supported by urbanization and labor-saving prefabrication trends. Stakeholders must embrace digital fabrication technologies to capture market share through 2033.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with C-suite executives at firms like Spancrete Group Inc., and secondary macroeconomic indicators from global construction indices.
Scope of the report and coverage parameters
This report covers global precast industry dynamics across residential and non-residential applications from 2026 to 2033. Limitations exclude cast-in-place concrete methodologies unless utilized in direct hybrid structural comparisons.
Recent developments, strategic moves, and partnerships
Recent industry momentum features strategic partnerships aimed at reducing carbon footprints through supplementary cementitious materials. Market participants like Balfour Beatty plc and Taisei Corporation continue to invest in automated robotic precasting facilities to enhance output.