Market overview of the Geophysical Data Collection Market
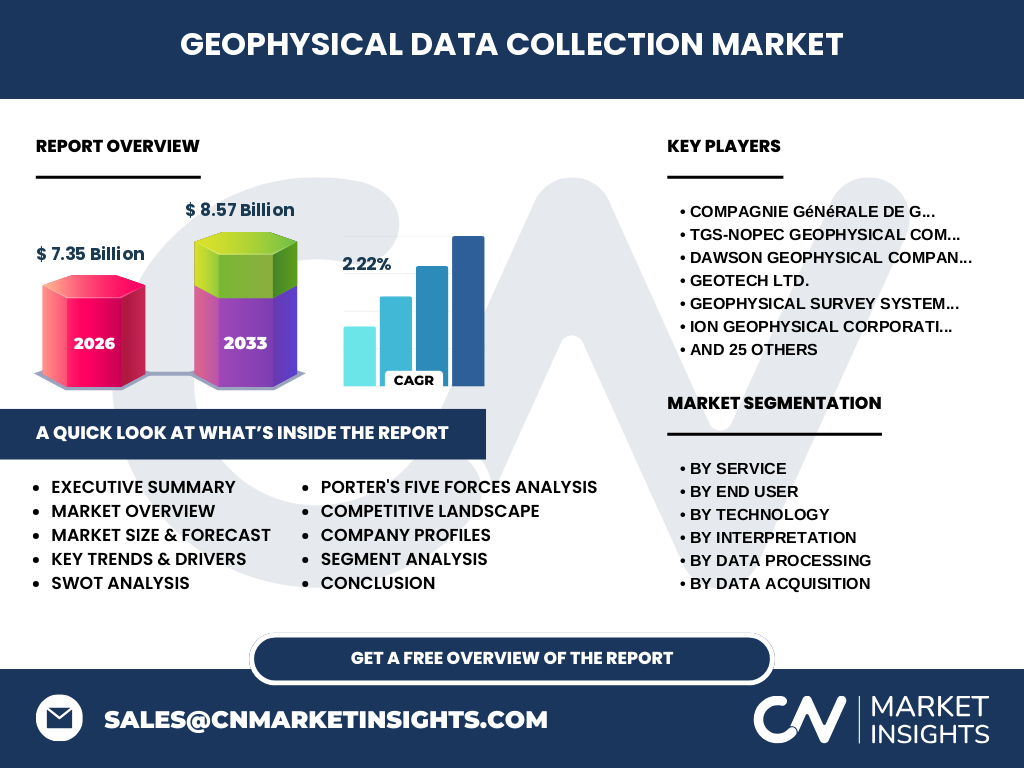
Our analysis indicates that the Geophysical Data Collection Market represents a foundational sector for subsurface intelligence, valued at $7.35 Billion in 2026. This market encompasses critical services like Data Acquisition, Data Processing, and Interpretation. Companies such as CGG SA and WesternGeco LLC rely on advanced 2D, 3D, and 4D Imaging technologies to map minerals, oil and gas reserves, and environmental hazards under strict regulatory frameworks.
What are the core drivers, restraints, challenges, and opportunities shaping the Geophysical Data Collection Market?
Growth is heavily propelled by escalating demand in Minerals & Mining and Water Exploration, driving the market toward a $8.57 Billion forecast by 2033. However, high capital expenditures for marine data acquisition and strict environmental compliance enforced by bodies like the United States Geological Survey act as major restraints. Opportunities lie in integrating machine learning for automated Seismic Data Processing.
Emerging trends and growth patterns in the Geophysical Data Collection Market
The industry is shifting rapidly toward high-resolution 4D Imaging and real-time data integration, driven by the need for enhanced reservoir and resource estimation. Innovators like TGS-NOPEC Geophysical Company ASA and Petroleum Geo-Services ASA are spearheading cloud-based subsurface mapping, allowing clients to analyze massive Electromagnetic Data Processing streams with unprecedented speed and precision.
How did COVID-19 impact the Geophysical Data Collection Market and shape its recovery trajectory?
The pandemic caused severe operational bottlenecks, delaying capital-intensive offshore and airborne campaigns due to travel restrictions and supply chain disruptions. Recovery has been steady, accelerated by a post-pandemic rebound in energy demand and expedited by remote-monitoring solutions deployed by firms like Dawson Geophysical Company to minimize on-site personnel risks during localized lockdowns.
Competitive benchmarking and strategic dynamics in the Geophysical Data Collection Market
Market concentration remains moderate to high, dominated by established tier-one providers including Halliburton Company, CGG SA, and BGP Inc. These industry leaders maintain competitive moats through proprietary Geophysical Modeling And Inversion technologies, extensive vessel fleets for marine surveys, and strategic mergers aimed at expanding their global footprint in emerging mining corridors.
Executive summary of key findings in the Geophysical Data Collection Market
Our comprehensive research establishes a projected expansion from $7.35 Billion in 2026 to $8.57 Billion by 2033 at a 2.22% CAGR. The Geophysical Data Collection Market industry trends highlight that Data Acquisition and advanced 3D interpretation services remain the primary revenue engines, heavily influenced by shifting energy policies and escalating environmental monitoring mandates globally.
Market forecast and projected growth trajectory from 2027 to 2033
Based on our econometric modeling, the Geophysical Data Collection Market will expand at a steady 2.22% CAGR, moving from $7.35 Billion in 2026 to reach $8.57 Billion by 2033. This trajectory reflects steady, capital-disciplined investments in renewable energy site characterization, deepwater oil exploration, and critical mineral mapping across challenging terrains.
Segmentation analysis across services, end users, technologies, and data types
The market is segmented by service into Data Acquisition, Data Processing, and Interpretation. End-use verticals span Agriculture, Environment, Minerals & Mining, Oil & Gas, and Water Exploration. Technology variations include 2D, 3D, and 4D Imaging. Specialized workflows encompass Gravity Data Processing and Geophysical Modeling And Analysis, catering to distinct industrial exploration requirements.
Regional market analysis and geographic performance distribution
Geographic performance varies significantly, with North America and the Middle East leading in Oil & Gas data acquisition spend, while Asia-Pacific exhibits the fastest growth in Minerals & Mining and Water Exploration. Regulatory landscapes, such as stringent EPA guidelines in the U.S. and complex offshore permitting in Europe, heavily dictate regional operational strategies for firms like Ramboll Group A/S.
In-depth regional review of key markets in the Geophysical Data Collection Market
North America remains a dominant hub supported by mature unconventional oil plays and robust environmental remediation projects. Meanwhile, the Asia-Pacific region is witnessing a surge in airborne and ground-based data acquisition driven by rapid industrialization and critical mineral exploration initiatives in Australia, engaging specialized regional consultancies and technology providers.
Company profiles and strategic positioning of leading industry participants
Industry leaders such as Compagnie Générale de Géophysique SA and TGS-NOPEC Geophysical Company ASA focus on multi-client library monetization and advanced seismic imaging. Specialty players like Geotech Ltd. dominate airborne electromagnetic surveys, while Dawson Geophysical Company leverages localized land-based seismic expertise to maintain strong regional market share.
Porter's Five Forces analysis of the Geophysical Data Collection Market
The threat of new entrants is moderate due to high capital requirements for specialized vessels and sensor equipment. Bargaining power of buyers is high given the commoditization of basic seismic data, compelling firms like ION Geophysical Corporation to pivot toward high-value software integration, hazard assessment interpretation, and proprietary cloud analytics platforms.
SWOT analysis highlighting internal capabilities and external market conditions
Strengths include extensive multi-client data libraries and advanced proprietary algorithms. Weaknesses involve high exposure to volatile energy commodity cycles. Opportunities stem from carbon capture and storage (CCS) site characterization. Threats comprise tightening environmental regulations and geopolitical tensions affecting cross-border marine data collection and seabed mapping operations.
Value chain analysis from raw materials to end-user deployment
The value chain initiates with specialized hardware manufacturers producing geophones, hydrophones, and sensors. Mid-stream activities involve data acquisition contractors and processing houses executing Seismic Data Processing and Data Filtering And Noise Reduction. Downstream delivery provides actionable subsurface models to end-users in mining, energy, and environmental engineering sectors.
Investment insights and high-potential areas for strategic allocation
Investors should target niche segments specializing in 4D Imaging and carbon sequestration monitoring. Companies integrating automated Data Integration And Analysis workflows offer superior scalability. High-potential areas include geotechnical surveys for offshore wind infrastructure and deep-mineral exploration necessary for global green energy supply chains.
Conclusion and key takeaways for stakeholders in the Geophysical Data Collection Market
The Geophysical Data Collection Market is transitioning into a technology-driven era marked by modest, stable growth reaching $8.57 Billion by 2033. Success hinges on technological differentiation, diversification into environmental and renewable sectors, and the ability to extract high-fidelity insights from complex subsurface datasets using advanced machine learning.
Research methodology used to triangulate baseline estimates and forecast metrics
Our baseline estimates and forecasts are triangulated by synthesizing proprietary trade registry data, primary stakeholder interviews with c-suite executives across major survey firms, and secondary macroeconomic indicators. This rigorous methodology reconciles top-down energy capital expenditure models with bottom-up operational metrics to ensure high forecast accuracy for the $7.35 Billion in 2026 baseline.
Scope of the report, coverage parameters, and analytical limitations
This report covers the global Geophysical Data Collection Market across six primary data acquisition modalities and five end-user verticals from 2026 through 2033. Limitations include unforeseen macroeconomic shifts, sudden geopolitical embargoes on marine research vessels, and rapid regulatory changes impacting offshore hydrocarbon and deep-sea mineral exploration rights.
Recent developments, strategic partnerships, and product launches in the industry
Recent market dynamics feature aggressive joint ventures in carbon storage monitoring and the launch of AI-powered seismic interpretation suites by market leaders. Firms are increasingly collaborating with cloud hyperscalers to handle petabyte-scale Electromagnetic Data Processing, significantly reducing turnaround times for mineral exploration clients and offshore energy developers.