What is the market overview and industry significance of the Gasoline Stations Market?
Our analysis indicates that the Gasoline Stations Market represents a vital node in global energy distribution, valued at $3.47 Billion in 2026. This sector governs the retail distribution of refined petroleum products, alternative gases, and ancillary retail offerings to end-users. It bridges upstream refining operations and consumer mobility.
Key market drivers, restraints, challenges, and opportunities shaping Gasoline Stations Market
Growth is propelled by rising road transport demand and expanding non-fuel retail operations. However, regulatory pressures from bodies like the EPA and stringent urban zoning laws act as key restraints. Strategic opportunities lie in diversifying into electric vehicle charging and alternative fuels such as hydrogen.
Emerging trends and growth patterns in Gasoline Stations Market
The industry is witnessing an accelerated shift toward convenience retail integration and multi-energy forecourts. Major operators like Shell plc and Exxon Mobil Corporation are transforming traditional refueling sites into localized mobility hubs featuring advanced automated car washes and digitized loyalty ecosystems.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted fuel consumption due to global lockdowns and remote work mandates, contracting forecourt throughput. Recovery has been driven by a rebound in commercial logistics and passenger transit, pushing the market toward its robust trajectory heading into 2027.
Competitive landscape, major players, and strategic dynamics
The market exhibits a consolidated structure dominated by integrated supermajors and national energy giants. Companies like Sinopec, China National Petroleum Corporation, and TotalEnergies SE leverage massive supply chain integration to maintain margin resilience against fluctuating crude oil feedstock costs.
Executive summary of the Gasoline Stations Market report
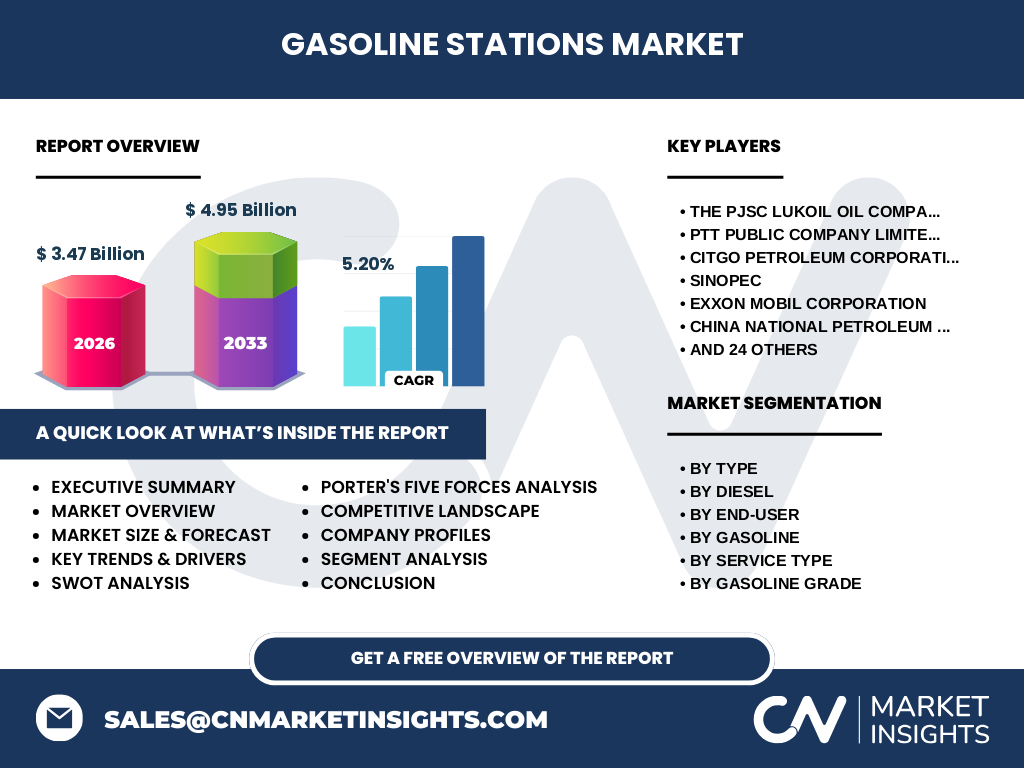
Our research forecasts the Gasoline Stations Market to expand from $3.47 Billion in 2026 to reach $4.95 Billion by 2033, achieving a steady CAGR of 5.20%. Traditional fuel dominance is increasingly supplemented by high-margin non-fuel sales and expanding alternative gas infrastructures.
Market forecast from 2027 to 2033
Based on our econometric modeling, the industry will experience steady expansion, scaling from its 2026 baseline to $4.95 Billion by 2033 at a CAGR of 5.20%. This growth is underpinned by rising urbanization in developing economies and steady demand for commercial diesel.
Segmentation analysis across product and service categories
Segmentation spans multiple dimensions: By Type covers Gasoline, Diesel, CNG Or Other Gases, and Non-Fuel Sales. By Diesel includes Regular and Premium Diesel. By Gasoline Grade features Regular, Midgrade, and Premium. By Service Type differentiates Self-Service and Full-Service operations.
Regional market analysis and geographic performance
Geographic performance varies significantly, with North America and Asia-Pacific leading in total throughput volume. Rapid motorization in developing Asian economies contrasts with mature, efficiency-driven markets in Europe, where strict environmental mandates shape localized forecourt investments.
In-depth regional review of key geographic territories
Asia-Pacific dominates volume consumption, driven by massive fleet expansions managed by players like Indian Oil Corporation and Reliance Industries Limited. Meanwhile, North American markets focus on optimizing retail convenience footprints led by operators like 7-Eleven Inc. and Wawa Inc.
Company profiles and strategic positioning of leading enterprises
Industry leaders maintain distinct competitive moats. Chevron Corporation and Marathon Petroleum Corporation focus on refined product logistics optimization, while specialized retail innovators like Sheetz Inc. and Aldrees Petroleum & Transport Services Co. drive revenue growth through advanced food service offerings.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate due to localized station density, while supplier power is dictated by upstream crude refiners. Threat of substitutes is rising via alternative mobility solutions, though traditional liquid fuels maintain entrenched logistical advantages across major transport corridors.
SWOT analysis of the Gasoline Stations Market
Strengths include established real estate networks and brand loyalty. Weaknesses involve high capital expenditure for environmental compliance. Opportunities emerge in hydrogen fuel and EV integration. Threats stem from aggressive carbon-reduction policies and fluctuating petroleum commodity prices.
Value chain analysis from raw materials to end-users
The value chain originates with crude oil extraction and refining, flows through primary bulk logistics to regional storage terminals, and terminates at retail forecourts. Value capture increasingly shifts downstream toward convenience store merchandise and high-grade premium fuels.
Investment insights and high-potential areas
Investors should target forecourts incorporating diversified non-fuel sales such as groceries and car wash services, which offer higher margins than base fuel dispensing. Strategic partnerships with alternative energy providers represent high-yield entry points for future-proofing retail assets.
Conclusion and key takeaways
The Gasoline Stations Market is navigating a pivotal transition phase. Reaching $4.95 Billion by 2033 at a 5.20% CAGR, success depends on balancing core petroleum distribution with agile non-fuel retail diversification and alternative fuel readiness.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with executives from Valero Energy Corporation and Petrochina Company Limited, and secondary macroeconomic indicators from global energy and transportation boards.
Scope of the report and coverage parameters
This report encompasses global retail fuel distribution networks through 2033. Limitations include unforeseen geopolitical disruptions in major oil-producing regions and regulatory shifts that could alter localized alternative fuel adoption timelines.
Recent developments in corporate strategy and partnerships
Recent industry moves highlight aggressive expansion into convenience retailing and alternative energy. Firms like ENI S.p.A. and Emirates National Oil Company Group have forged strategic alliances to deploy multi-energy charging infrastructure and digital payment platforms across their retail networks.