What is the scope and industry significance of the Energy Meters Market?
The Energy Meters Market is valued at $25.44 Billion in 2026, serving as the foundational backbone for global electrical grid modernization. Our analysis indicates that raw material availability, including silicon wafers and copper, directly dictates manufacturing capacity. Regulatory compliance with bodies like the IEEE and IEC governs device certification, ensuring metering accuracy across residential, commercial, and industrial deployments.
Structural Growth Drivers and Market Restraints
Grid decarbonization mandates and the rapid adoption of electric vehicle infrastructure are key catalysts. Conversely, supply chain bottlenecks for semiconductor components and stringent cybersecurity protocols act as primary restraints. Industry leaders like Landis+Gyr Group AG and Itron Inc. leverage proprietary firmware security to mitigate these vulnerabilities, driving deployment reliability across volatile macroeconomic landscapes.
Emerging trends and growth patterns in the Energy Meters Market
The shift toward advanced metering infrastructure featuring cellular IoT integration is redefining utility operations. Sagemcom Energy & Telecom and Kamstrup A/S are pioneering edge-computing capabilities within smart meters, enabling real-time demand response. This trend heavily favors manufacturers equipped with robust firmware update protocols to handle dynamic grid loads.
How did the COVID-19 pandemic impact the industry recovery trajectory?
Pandemic-induced supply chain fractures delayed municipal metering rollouts globally, causing short-term revenue contractions. However, post-crisis infrastructure stimulus packages accelerated digital grid investments. Based on our research, utilities capitalized on remote-read technologies during lockdowns, permanently shifting procurement priorities toward touchless, automated metering solutions.
Competitive Benchmarking and Industry Concentration
The market exhibits a consolidated structure dominated by tier-one conglomerates like Schneider Electric SE, ABB Ltd., and Siemens-backed entities. These heavyweights compete on interoperability and cloud analytics integration. Mid-tier innovators like Iskraemeco d.d. and Apator S.A. carve out profitable niches via localized compliance and modular meter designs.
Executive summary of key findings for the Energy Meters Market
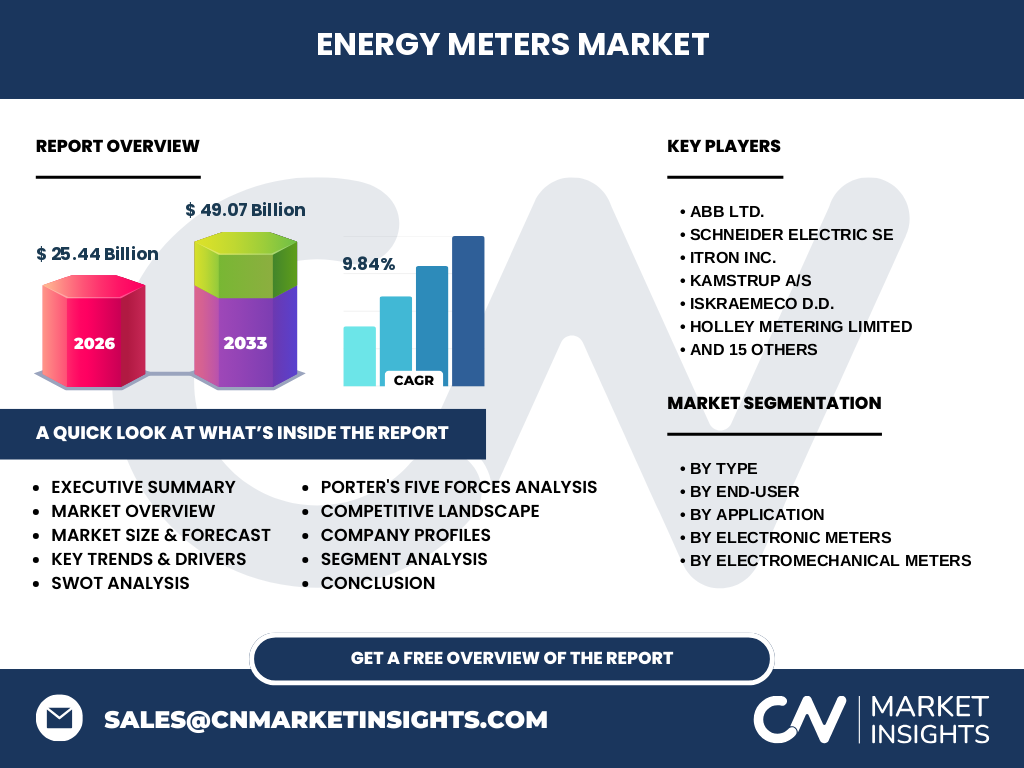
Our comprehensive research projects the market to expand from $25.44 Billion in 2026 to $49.07 Billion by 2033 at a CAGR of 9.84%. Urbanization, smart grid mandates, and decentralized renewable generation serve as core value accelerators. Companies failing to transition from legacy electromechanical devices to smart electronic platforms risk immediate market obsolescence.
Energy Meters Market forecast and growth trajectory through 2033
Driven by aggressive net-zero carbon targets, the market will scale aggressively to reach $49.07 Billion by 2033. The projected 9.84% CAGR reflects accelerated capital expenditure by distribution system operators. The data suggests that emerging economies in Asia-Pacific will contribute disproportionately to this valuation expansion through greenfield smart grid deployments.
Segmentation analysis of device types and end-user verticals
The market bifurcates into Electromechanical Meters (Analog Meters, Induction Meters) and Electronic Meters (Smart Meters, Digital Meters, Prepaid Meters). End-user verticals span Residential, Commercial, and Industrial sectors, while applications encompass Power Substations and Electric Vehicle Chargers. Smart electronic variants dominate new procurement cycles due to bidirectional communication needs.
Geographic distribution and regional market performance
Regional performance varies based on regulatory pressure and government subsidization of smart grid tech. North America and Europe prioritize grid hardening and cybersecurity, whereas Asia-Pacific leads in raw volume consumption driven by rapid urbanization. Regional logistics hubs through major ports facilitate steady component flow for regional assemblers like Hexing Group and Wasion Group Holdings.
In-depth regional review of high-growth territories
Asia-Pacific represents the most aggressive growth arena, fueled by national smart metering mandates in developing economies. Conversely, European markets focus on replacement cycles substituting first-generation smart devices with high-precision IoT meters. This regional dichotomy requires multinational vendors like Secure Meters Limited to tailor firmware to local utility communication protocols.
Strategic positioning of leading company profiles
Industry stalwarts balance hardware durability with software-as-a-service monetization. Jiangsu Linyang Electronics Co. Ltd. and Holley Metering Limited focus on cost-optimized scaled manufacturing, whereas Elster Group GmbH and ZIV Automation specialize in heavy industrial sub-station metering. This strategic diversity prevents commoditization across core product lines.
Porter's Five Forces analysis of the competitive ecosystem
Bargaining power of buyers remains moderate-to-high, as municipal utilities often execute massive, consolidated tenders. Threat of substitutes is low, given strict legal mandates for certified metering. Supplier power fluctuates with semiconductor availability, while competitive rivalry is intense, forcing continuous R&D investment into secure, interoperable metering hardware.
SWOT analysis of the global metering sector
Key strengths lie in high switching costs and mission-critical utility integration. Weaknesses involve vulnerability to silicon supply shocks. Opportunities abound in electric vehicle charger sub-metering. Threats include sophisticated nation-state cyberattacks targeting grid-connected smart endpoints, necessitating rigorous encryption standards across all manufactured units.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material extraction of silicon, copper, and rare-earth magnets. Component fabricators then supply printed circuit boards to Tier-1 assemblers like Genus Power Infrastructures Ltd. and EDMI Limited. Finished units flow through specialized logistics networks to utility end-users, supported by cloud analytics platforms from firms like Cuculus GmbH.
Strategic investment insights and high-potential focus areas
Investors should target firms specializing in EV charging sub-metering and AI-driven grid analytics integration. Companies with agile supply chains capable of sourcing alternative microcontrollers will outperform peers. The data highlights prepaid electronic meters in emerging markets as a high-margin growth vector worth immediate capital allocation.
Conclusion and critical industry takeaways
The transition toward a $49.07 Billion valuation by 2033 underscores the fundamental shift in electrical infrastructure management. Manufacturers must embed advanced cybersecurity and IoT capabilities into every product line. Success belongs to agile innovators who navigate regulatory hurdles while scaling production efficiency to meet surging global demand.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with chief technology officers at major utilities, and secondary macroeconomic indicators. We cross-reference municipal deployment filings with semiconductor shipment metrics to ensure absolute accuracy in our market sizing models.
Scope of the report and coverage parameters
This report covers global revenue streams for electromechanical and electronic energy meters across residential, commercial, and industrial end-user verticals from 2026 to 2033. Excluded from this scope are behind-the-meter sub-meters utilized strictly for internal industrial process monitoring without grid-connection capabilities or utility reporting mandates.
Recent developments, partnerships, and strategic corporate moves
Recent market dynamism features aggressive cross-border joint ventures and cloud-platform acquisitions. Market players frequently partner with telecom giants to embed secure eSIM technology directly into metering hardware. These strategic maneuvers aim to capture recurring software service revenues amidst hardware commoditization pressures.