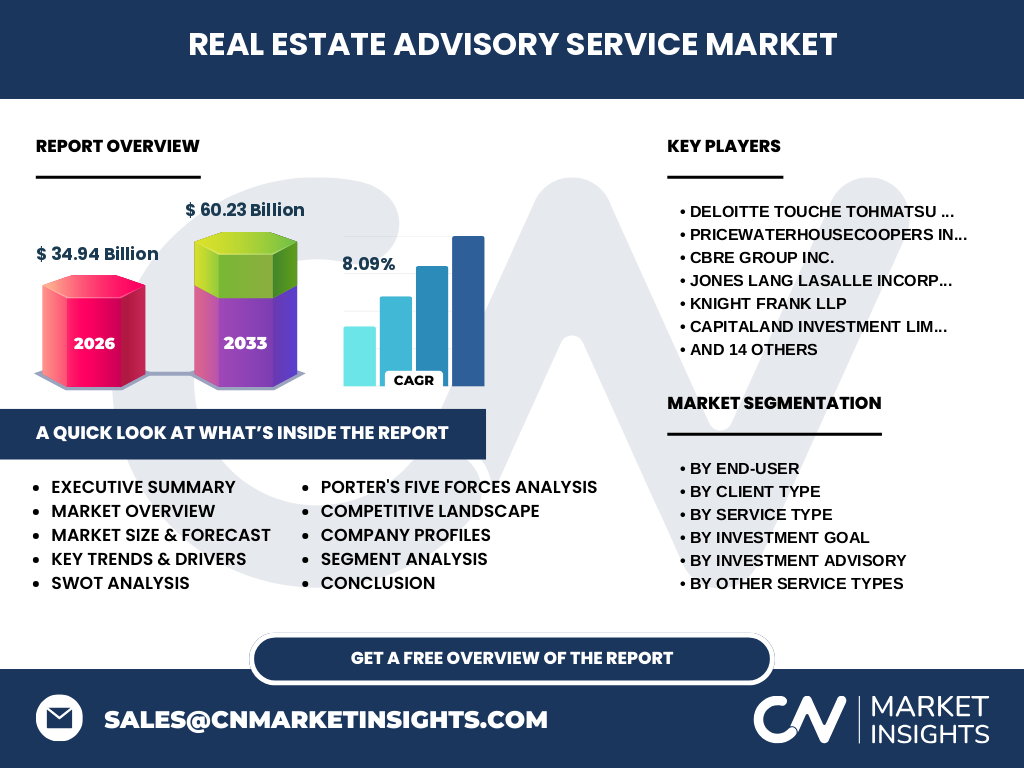
Market overview of the Real Estate Advisory Service Market
Our analysis indicates that the Real Estate Advisory Service Market reached a market size of 34.94 Billion in 2026. This sector encompasses critical professional consulting, valuation, and transaction structuring for commercial, residential, and industrial assets. Industry participants navigate complex regulatory frameworks set by bodies like the RICS and SEC to optimize capital allocation and mitigate asset-level risks.
What are the key market drivers, restraints, challenges, and opportunities shaping the Real Estate Advisory Service Market?
The market is propelled by surging institutional demand for alternative asset classes and cross-border portfolio diversification. However, macroeconomic headwinds, fluctuating interest rates, and stringent zoning laws enforced by municipal urban planning authorities act as primary restraints. Strategic opportunities abound in sustainability consulting, helping firms align with evolving ESG mandates and green building certifications.
Emerging trends and growth patterns in the Real Estate Advisory Service Market
The industry is witnessing an accelerated shift toward technology-enabled due diligence and automated property valuation models. Leading advisory firms increasingly integrate geospatial data analytics and carbon-neutral audit tools into their core offerings. This trend favors tech-forward entities capable of scaling complex portfolio strategy development and regulatory compliance advisory without compromising analytical rigor.
COVID-19 impact analysis on the Real Estate Advisory Service Market
The pandemic severely disrupted transactional velocity across commercial and retail real estate, forcing advisory firms to pivot rapidly toward distressed asset restructuring and lease advisory services. The recovery trajectory has been marked by a permanent integration of hybrid workplace strategies, boosting demand for specialized development strategy and planning consultants adept at repositioning underutilized urban footprints.
Competitive landscape of the Real Estate Advisory Service Market
The competitive landscape is characterized by a mix of global professional services networks and specialized real estate brokerages. Market concentration is moderate, with powerhouse entities like CBRE Group Inc., Jones Lang LaSalle Incorporated, and Cushman & Wakefield plc leveraging global reach to dominate institutional mandates, while specialized boutiques capture niche local markets.
Executive summary of key findings for the Real Estate Advisory Service Market
Our comprehensive research confirms robust expansion, projecting the Real Estate Advisory Service Market to surge from 34.94 Billion in 2026 to 60.23 Billion by 2033, expanding at a notable CAGR of 8.09%. Growth is anchored by increasing urbanization, institutional capital inflows, and complex sustainability mandates governing modern property development.
Market forecast for the Real Estate Advisory Service Market from 2027 to 2033
Based on our econometric models, the market is set to expand rapidly, moving from its 2026 baseline to achieve 60.23 Billion by 2033. This growth trajectory, underpinned by an 8.09% CAGR, reflects sustained corporate demand for professional guidance in navigating volatile capital markets and shifting regulatory environments across global financial hubs.
Segmentation analysis across end-users, clients, and services
Market segmentation spans multiple dimensions: End-User (Residential, Commercial, Industrial), Client Type (Individual Clients, Corporate Clients, Institutional Investors, Government Agencies), Service Type (Investment Advisory, Transaction Advisory, Valuation And Appraisal, Strategic Consulting), and Investment Goal (Capital Appreciation, Rental Income Generation). Each segment dictates specific advisory competencies, from industrial property appraisals to complex REIT portfolio strategies.
Regional market analysis and geographic distribution
Geographic performance varies significantly, driven by localized macroeconomic conditions, foreign investment policies, and urban density constraints. North America and Europe currently command major revenue shares due to established institutional investment frameworks, while Asia-Pacific markets demonstrate the highest incremental growth velocity, fueled by rapid urbanization and large-scale infrastructure investments.
In-depth regional review of the Real Estate Advisory Service Market
In North America, advisory services are heavily influenced by Federal Reserve monetary policy and regional zoning codes. Meanwhile, the EMEA market focuses intensely on EU-driven taxonomy compliance and retrofitting aging commercial stock. APAC growth is concentrated in gateway cities across Southeast Asia, where rapid industrialization requires sophisticated feasibility studies and site selection expertise.
Company profiles and strategic positioning of leading firms
Industry giants such as Deloitte and PwC anchor their positioning in financial reporting valuation and rigorous tax-benefit structuring. Concurrently, dedicated real estate powerhouses like Knight Frank LLP, Savills plc, and Colliers International leverage extensive proprietary transactional data to dominate buy-side advisory and commercial property valuation mandates worldwide.
Porter's Five Forces analysis of the industry
The threat of new entrants remains moderate due to high capital requirements and the necessity of established client trust. Buyer power is substantial among institutional investors who demand bespoke analytics. Supplier power is low, though specialized prop-tech data providers hold leverage. Rivalry is intense among top-tier firms competing for marquee institutional asset management contracts.
SWOT analysis for the Real Estate Advisory Service Market
Key strengths include deep domain expertise and entrenched relationships with institutional capital. Weaknesses involve high reliance on cyclical property market conditions. Opportunities lie in expanding ESG advisory and digital asset tokenization consulting. Threats include macroeconomic recessionary pressures and tightening cross-border investment regulations imposed by national authorities.
Value chain analysis from raw advisory inputs to end-users
The industry value chain begins with raw macroeconomic data acquisition, GIS mapping inputs, and regulatory registry records. Advisory firms synthesize these inputs through proprietary valuation algorithms and expert analysis, delivering actionable intelligence to end-users such as corporate tenants, institutional funds, and government agencies seeking capital appreciation or wealth preservation.
Investment insights and strategic recommendations for stakeholders
Our analysis indicates that stakeholders should prioritize investments in technology infrastructure, specifically predictive market forecasting algorithms and automated ESG compliance tracking tools. Firms that integrate sustainability advisory directly into traditional capital markets consulting will capture outsized market share among institutional investors seeking long-term risk mitigation.
Conclusion and key takeaways for market participants
The Real Estate Advisory Service Market presents compelling growth prospects, anchored by a projected expansion to 60.23 Billion by 2033. Success in this evolving ecosystem requires combining traditional valuation mastery with advanced technological capabilities, regulatory agility, and comprehensive sustainability advisory services to meet sophisticated client demands.
Research methodology used for market sizing and forecasting
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with C-suite executives across top advisory firms, and secondary macroeconomic indicators. Quantitative models cross-reference historical transaction volumes with predictive econometric variables to ensure high fidelity across all market segments and regional forecasts.
Scope of the report and analytical limitations
This report covers global advisory services categorized by end-user, client type, service type, and investment goal from 2026 through 2033. Limitations include potential unforeseen geopolitical shocks, sudden regulatory shifts in major financial jurisdictions, and fluctuations in primary currency exchange rates that could marginally influence cross-border transaction advisory revenues.
Recent developments, partnerships, and strategic moves in the industry
Recent strategic maneuvers feature major consolidations, such as cross-border mergers and acquisitions among firms like Newmark Group Inc. and Avison Young, aimed at expanding global transaction advisory footprints. Furthermore, market leaders are actively forming joint ventures with specialized prop-tech innovators to enhance their urban planning and green building advisory capabilities.