What is the scope and industry significance of the Electronics And Appliance Stores Market?
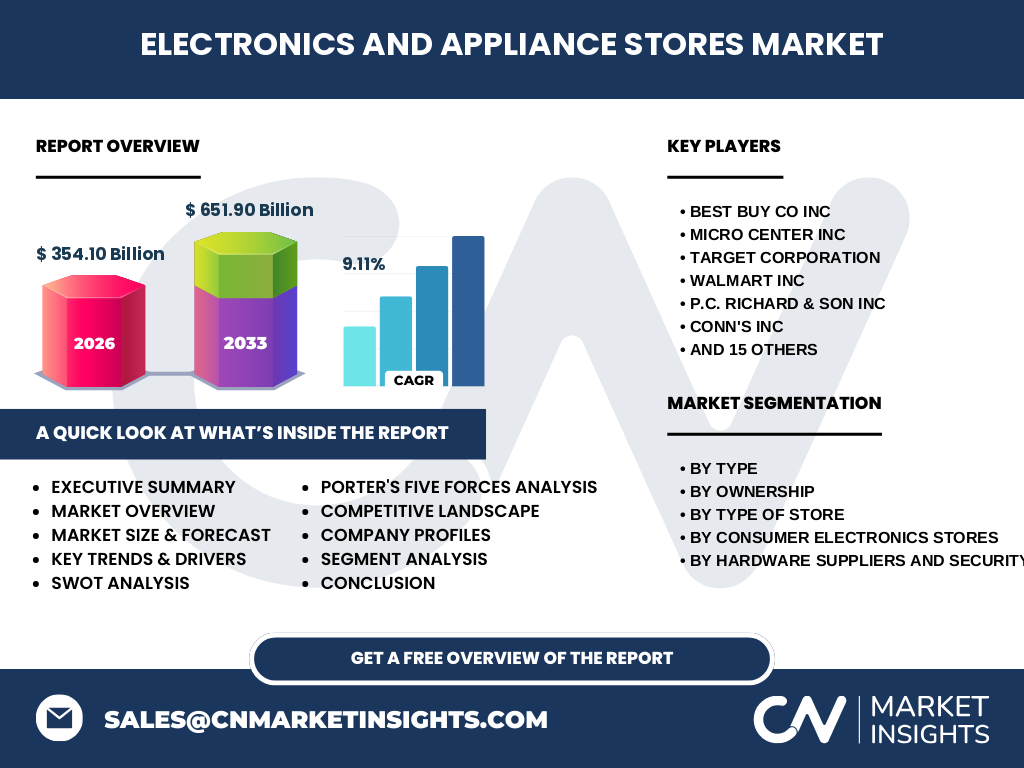
Our analysis indicates that the Electronics And Appliance Stores Market reached a baseline valuation of 354.10 Billion in 2026. This ecosystem encompasses specialized retail channels distributing hardware suppliers, security systems, and consumer electronics, serving as a critical commercial bridge between original equipment manufacturers and end-users.
Key market drivers, restraints, challenges, and opportunities shaping Electronics And Appliance Stores Market
The market is propelled by rapid IoT adoption and smart home integration. However, supply chain bottlenecks involving rare-earth minerals and stringent energy-efficiency mandates by the Department of Energy act as restraints. Opportunities abound in omnichannel fulfillment strategies for enterprise-grade security systems.
Emerging trends and growth patterns in Electronics And Appliance Stores Market
The shift toward experiential showrooms is redefining physical footprints. Specialty players like ABT Electronics Inc and Crutchfield Corporation leverage augmented reality product demonstrations, driving higher conversion rates compared to traditional inventory-heavy big-box retailers.
COVID-19 impact analysis on the Electronics And Appliance Stores Market
Pandemic-era remote work initiatives triggered an unprecedented surge in consumer electronics demand. While global logistical gridlocks initially crippled inventory replenishment, adaptive omnichannel operators successfully pivoted to curbside pickup and contactless home delivery, accelerating digital transformation by years.
Competitive landscape and strategic market concentration
The competitive landscape features a polarized dynamic between retail giants like Walmart Inc and Costco Wholesale Corporation, and specialized operators such as B&H Photo Video. Market concentration remains moderate, with omnichannel juggernauts leveraging immense purchasing power to squeeze supplier margins.
Executive summary of key findings
Our research projects the Electronics And Appliance Stores Market to expand from 354.10 Billion in 2026 to 651.90 Billion by 2033, achieving a robust CAGR of 9.11%. Success hinges on seamless digital integration and personalized advisory services.
Market forecast trajectory from 2027 to 2033
Driven by replacement cycles of smart appliances and security upgrades, the market will scale aggressively from 2027 to 2033 to hit 651.90 Billion. This expansion represents a compound annual growth rate of 9.11%, fueled by urban residential developments.
Segmentation analysis across store formats and ownership types
Segmentation divides the market by type into Hardware Suppliers And Security Stores and Consumer Electronics Stores. Ownership models separate retail chains from independent operators, while store formats range from exclusive showrooms to inclusive dealer networks.
Regional market analysis and geographic distribution
North America dominates the revenue share, supported by high disposable incomes and mature digital infrastructure. Meanwhile, Asia-Pacific exhibits the fastest regional acceleration due to rapid urbanization and expanding middle-class consumer bases purchasing advanced home appliances.
In-depth regional review of key markets
North American markets emphasize premium smart-home ecosystems, whereas European territories enforce strict eco-design regulations that favor energy-efficient refrigeration and climate control units sold through specialized electrical supply channels and regional retail chains.
Strategic positioning of leading companies
Industry leaders like Best Buy Co Inc and Amazon.com Inc deploy advanced hybrid models, blending physical consultative selling with hyper-efficient digital logistics. Meanwhile, niche players like Micro Center Inc capture enthusiast demographics through deep technical inventory.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers is moderate due to dominant big-box retail channels controlling shelf space. Competitive rivalry is fierce, driven by margin compression from pure-play e-commerce platforms like Newegg Inc and global marketplace giants.
SWOT analysis of the retail sector
Strengths include extensive customer reach and localized fulfillment networks. Weaknesses involve high inventory holding costs. Opportunities lie in integrated smart-security subscription services, while threats stem from direct-to-consumer manufacturer sales strategies.
Value chain analysis from raw materials to end-users
The value chain traces component sourcing (silicon, rare earths) through OEM assembly, logistics hubs at major maritime ports, wholesale distribution by firms like Costco, and final retail delivery managed by specialized technicians and installers.
Investment insights and high-potential areas
Investors should target omnichannel enablers and B2B security integration specialists. Companies possessing proprietary installation logistics and robust reverse-supply-chain capabilities offer superior margin expansion potential through 2033.
Conclusion and key takeaways for stakeholders
The Electronics And Appliance Stores Market offers exceptional upside, scaling to 651.90 Billion by 2033. Operators must invest in experiential retail and advanced inventory visibility to capture shifting consumer preferences.
Research methodology and baseline estimation techniques
Our baseline estimates are triangulated by combining corporate financial disclosures, customs import-export registries, primary stakeholder interviews with retail executives, and secondary macroeconomic indicators regarding housing starts and consumer spending indices.
Scope of the report and coverage parameters
This report covers global brick-and-mortar and digital retail operations specializing in consumer electronics, major appliances, and security hardware. B2B industrial component distribution is excluded to maintain strict consumer-facing retail parameters.
Recent developments, corporate announcements, and strategic partnerships
Recent market activities feature major consolidation moves, retail-media network launches by big-box operators, and strategic logistics partnerships aimed at reducing last-mile delivery times for oversized home appliances and complex security systems.