What is the market overview and industry significance of the Bearing Steel Market?
Our analysis indicates that the Bearing Steel Market commands a valuation of 7.41 Billion in 2026. This specialized alloy sector provides foundational high-purity materials essential for reducing friction in heavy machinery, automotive assemblies, and aerospace turbines, ensuring extreme fatigue resistance under severe cyclical loading conditions.
Structural Growth Drivers, Restraints, and Opportunities
Growth is propelled by surging wind energy installations demanding high-performance steels like M50 Steel. However, volatile alloy surcharges for raw chromium and molybdenum constrain margins. Significant opportunities lie in developing ultra-clean vacuum-degassed steels to meet stringent ISO cleanliness standards mandated by global industrial consumers.
Emerging Trends and Growth Patterns in the Sector
The shift toward electrification has accelerated demand for specialized carburizing grades such as 8620 Steel and 9310 Steel in electric vehicle powertrains. Producers are increasingly adopting advanced ladle metallurgy furnace techniques to minimize non-metallic inclusions and enhance rolling contact fatigue life.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted global supply chains, halting production at primary mills operated by giants like Nippon Steel Corporation and Tata Steel Limited. The subsequent recovery trajectory has been driven by a sharp rebound in automotive production and robust investments in renewable energy infrastructure.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, dominated by integrated metallurgical conglomerates like China Baowu Steel Group Corp. Ltd. and specialized producers such as Daido Steel Co. Ltd. Strategic dynamics center on vertical integration, proprietary heat-treatment technologies, and long-term supply agreements with tier-one bearing manufacturers.
Executive Summary: High-Level Synthesis of Key Findings
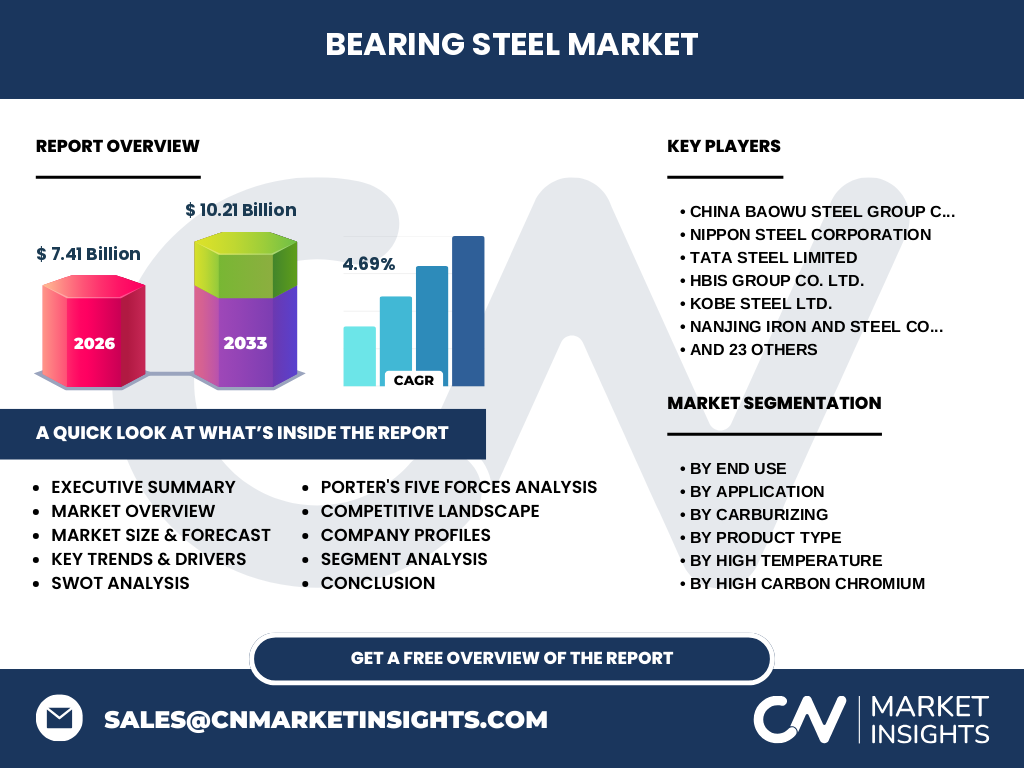
Our comprehensive research demonstrates that the Bearing Steel Market is poised for steady expansion, growing from 7.41 Billion in 2026 to 10.21 Billion by 2033 at a CAGR of 4.69%, underpinned by robust industrial automation and aerospace recovery.
Bearing Steel Market Forecast from 2027 to 2033
The data suggests the market will achieve a solid CAGR of 4.69% over the forecast window, expanding from its 2026 baseline to reach 10.21 Billion by 2033. This trajectory reflects sustained capital expenditure in precision engineering and high-speed railway networks across developing economies.
Segmentation Analysis: End Use, Application, and Product Types
The sector breaks down by End Use into Automotive, Aerospace, Machinery And Equipment, Energy, and Other End Uses. Application categories cover Ball Bearings, Roller Bearings, Thrust Bearings, and Other Applications. Product types encompass High Carbon Chromium, Carburizing, and High Temperature steels, with 100Cr6 (AISI 52100) dominating high-volume manufacturing.
Regional Market Analysis and Geographic Distribution
Geographic performance is heavily weighted toward industrial manufacturing hubs in Asia-Pacific, North America, and Europe. Strict environmental regulations by bodies such as the European Union Emissions Trading System heavily influence regional steel production methods, favoring electric arc furnace routes over traditional blast furnaces.
In-Depth Regional Review
Asia-Pacific commands the lion's share of consumption, fueled by massive automotive and industrial manufacturing clusters in China, Japan, and India. Meanwhile, North America and Europe focus on high-value niche segments, particularly aerospace-grade M50 Steel and premium 440C Stainless Steel for corrosive environments.
Company Profiles and Strategic Positioning
Industry leaders like AB SKF, NSK Ltd., and The Timken Company leverage captive steel production or exclusive mill partnerships to secure raw material consistency. Concurrently, material innovators such as Kobe Steel Ltd. and Saarstahl AG focus on proprietary alloy designs to capture high-margin aerospace contracts.
Porter's Five Forces Analysis of the Industry
Supplier power remains moderate due to raw material commodity pricing, while buyer power is high among major automotive OEMs demanding cost concessions. Threat of substitution is low given stringent metallurgical requirements, though the threat of new entrants is mitigated by high capital expenditure barriers.
SWOT Analysis of the Global Landscape
Strengths include established proprietary alloy formulations and deep OEM relationships. Weaknesses involve high energy dependency. Opportunities abound in offshore wind turbine components, while threats stem from geopolitical trade tariffs and raw material price volatility affecting scrap steel and ferroalloys.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction of iron ore, carbon, chromium, and molybdenum. This proceeds through primary steelmaking, secondary ladle metallurgy, continuous casting, and hot rolling, culminating in precision machining and heat treatment by specialized bearing manufacturers for final integration.
Investment Insights and High-Potential Areas
Strategic recommendations highlight investments in vacuum induction melting facilities and green steel production capabilities. High-potential areas include high-temperature alloys like M42 Steel designed for extreme aerospace applications and demanding defense sector requirements.
Conclusion and Key Takeaways
The Bearing Steel Market represents a technologically vital, moderately consolidated sector transitioning toward cleaner production methods and advanced high-temperature alloys. Reaching 10.21 Billion by 2033, success will favor firms investing in metallurgical purity and localized supply chain resilience.
Research Methodology and Baseline Triangulation
Baseline estimates are meticulously triangulated by combining customs trade registry data, primary stakeholder interviews with chief metallurgists and procurement directors, and secondary macroeconomic indicators from industrial associations to ensure robust, verifiable market sizing.
Scope of the Report and Coverage Parameters
This report covers global consumption, production trends, and pricing dynamics across specified product, carburizing, application, and end-use segments from 2026 through 2033. Limitations exclude non-alloy carbon structural steels and unverified artisanal secondary scrap markets.
Recent Developments: Corporate Announcements and Strategic Moves
Recent industry activity features strategic joint ventures between specialty steelmakers and bearing OEMs to co-develop carbon-neutral production processes. Notable initiatives by firms like Nanjing Iron and Steel Co. Ltd. focus on expanding high-cleanliness steel output for high-speed rail applications.