Market overview of the High Strength Aluminum Alloys Market
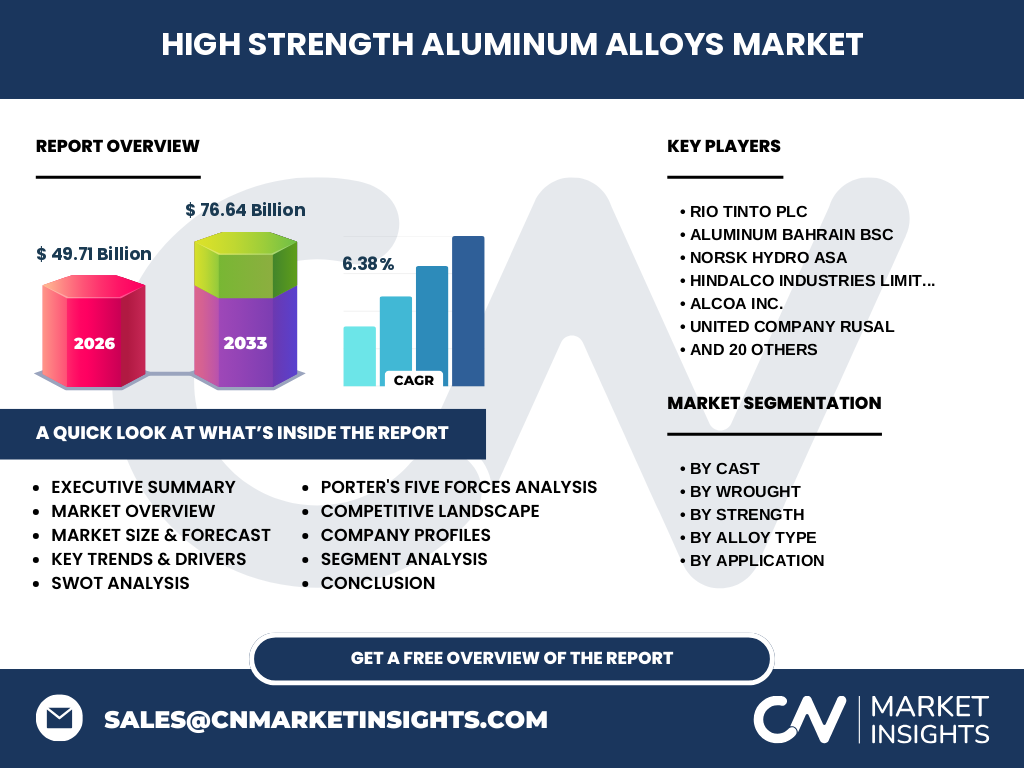
Our analysis indicates that the High Strength Aluminum Alloys Market encompasses advanced metallurgical formulations engineered for extreme mechanical stress, evaluated at $49.71 Billion in 2026. These materials are critical for lightweighting aerospace frames and defense vehicles, complying with strict Federal Aviation Administration standards. Industry participants like Alcoa Inc. and Constellium SE leverage specialized thermo-mechanical processing to supply critical structural components to global original equipment manufacturers.
What are the primary market drivers, restraints, challenges, and opportunities?
The market is propelled by stringent International Maritime Organization emission mandates and automotive lightweighting goals, offset by raw material price volatility in primary aluminum and silicon. Supply chain bottlenecks involving bauxite mining in Guinea create severe logistical hurdles for European smelters. Conversely, the electrification of transport vectors offers substantial growth opportunities for high-strength extrusions.
Emerging trends and growth patterns in the High Strength Aluminum Alloys Market
A definitive industry trend is the adoption of closed-loop recycling loops by major producers like Novelis Inc. and Norsk Hydro ASA to reduce carbon footprints. Advanced scrap sorting technologies now allow precise alloy segregation, directly lowering reliance on energy-intensive primary smelting while preserving the mechanical integrity of 7xxx series alloys.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe disruptions in commercial aviation and automotive assembly lines, depressing demand for high-strength plate and sheet products. Based on our research, the recovery trajectory has been shaped by aggressive defense spending and localized supply chain re-shoring. Companies utilizing automated casting facilities rebounded faster than competitors relying on manual handling.
Competitive landscape and strategic dynamics
The competitive landscape features high market concentration among vertically integrated giants like Rio Tinto plc and United Company Rusal, alongside agile specialized extruders. Strategic dynamics revolve around securing low-carbon power purchase agreements for energy-intensive potlines and acquiring downstream recycling assets to protect margins against raw material cost spikes.
Executive summary of key findings
Our proprietary research confirms that the High Strength Aluminum Alloys Market is poised for robust expansion, driven by stringent fuel-efficiency standards and aerospace demand. Key players are heavily investing in proprietary thermal treatments. Strategic positioning around sustainable, low-carbon alloy production will dictate market leadership through the decade.
Market forecast from 2027 to 2033
Driven by accelerating demand in lightweight defense vehicles and next-generation commercial aircraft, the High Strength Aluminum Alloys Market size is projected to reach $76.64 Billion by 2033. This expansion represents a steady compound annual growth rate of 6.38%, underpinned by rising adoption of ultra-high strength automotive body structures.
Segmentation analysis across alloy series and product types
Market segmentation spans cast and wrought categories, including 2xx.x, 3xx.x, 4xx.x, and 7xx.x series for complex castings, and 2xxx, 6xxx, and 7xxx series for high-stress wrought plates. Wrought alloys dominate structural aerospace applications due to superior fracture toughness, whereas silicon-rich cast alloys excel in complex automotive engine blocks.
Regional market analysis and geographic distribution
Geographic performance highlights North America and Europe as dominant demand centers, anchored by robust aerospace clusters near major logistical hubs like Seattle and Toulouse. Meanwhile, Asia-Pacific acts as the primary manufacturing engine, driven by rapid industrialization, expanding rail networks, and heavy automotive assembly investments in China and Japan.
In-depth regional review of key markets
North American growth is anchored by stringent Corporate Average Fuel Economy standards, forcing automakers to adopt 6xxx and 7xxx series extrusions. In contrast, the Asia-Pacific regional review reveals immense consumption fueled by China's massive high-speed rail expansion and domestic aerospace programs, utilizing advanced inputs from suppliers like Aluminum Corporation of China Limited.
Company profiles and strategic positioning
Industry leaders maintain distinct competitive moats through proprietary alloy development and regional positioning. For instance, Kobe Steel Ltd. and UACJ Corporation focus heavily on high-precision aerospace sheet, while Hindalco Industries Limited leverages low-cost captive power and bauxite access to capture high-volume industrial extrusions in emerging markets.
Porter's Five Forces analysis of the sector
Porter's Five Forces analysis indicates moderate-to-high supplier power due to concentrated bauxite and alumina supply chains. Buyer power remains high among major aerospace primes like Boeing and Airbus, whereas the threat of substitution is mitigated by stringent certification requirements for structural metal replacements.
SWOT analysis of the High Strength Aluminum Alloys Market
Strengths include exceptional strength-to-weight ratios and infinite recyclability. Weaknesses involve high energy intensity during primary electrolysis. Opportunities lie in electric vehicle battery enclosures, while threats include rising carbon border adjustment tariffs imposed by regional regulatory bodies on carbon-heavy imports.
Value chain analysis from raw materials to end-users
The value chain initiates with bauxite mining and the Bayer-Hall-Héroult refining process, progressing through DC casting, hot rolling, and thermo-mechanical processing. Value capture concentrates heavily downstream in specialized extrusion and heat-treatment facilities operated by firms like Arconic Corporation, serving mission-critical end-users.
Investment insights and strategic recommendations
We advise market entrants and investors to prioritize greenfield investments in closed-loop recycling infrastructure and hydrogen-powered melting furnaces. High-potential areas include dedicated production lines for ultra-high strength EV crash management systems, insulating portfolios against traditional aerospace cyclicality.
Conclusion and key takeaways
The High Strength Aluminum Alloys Market represents a high-barrier, technology-driven sector essential for global decarbonization and lightweighting. Success requires balancing energy security with advanced metallurgical innovation, positioning proactive alloy producers for sustained profitability through 2033.
Research methodology and data triangulation
Our research methodology employs a rigorous triangulation approach, combining customs trade registry data, primary executive interviews with chief metallurgists, and secondary macroeconomic indicators from the International Aluminum Institute. Baseline estimates are cross-referenced with capacity data from major ports and smelters.
Scope of the report and analytical parameters
This report covers global consumption, production capacities, and pricing dynamics across cast and wrought variants from 2026 through 2033. Exclusions apply to standard commercial foil and non-structural architectural framing materials that do not meet specialized high-strength mechanical benchmarks.
Recent developments, partnerships, and strategic moves
Recent industry developments feature aggressive capital expenditure by companies like Kaiser Aluminum Corporation and Constellium SE toward low-carbon recycling lines. Furthermore, strategic supply agreements between rolling mills and EV manufacturers highlight an industry-wide pivot toward localized, sustainable alloy sourcing.