What is the scope and industry significance of the Green Mining Market?
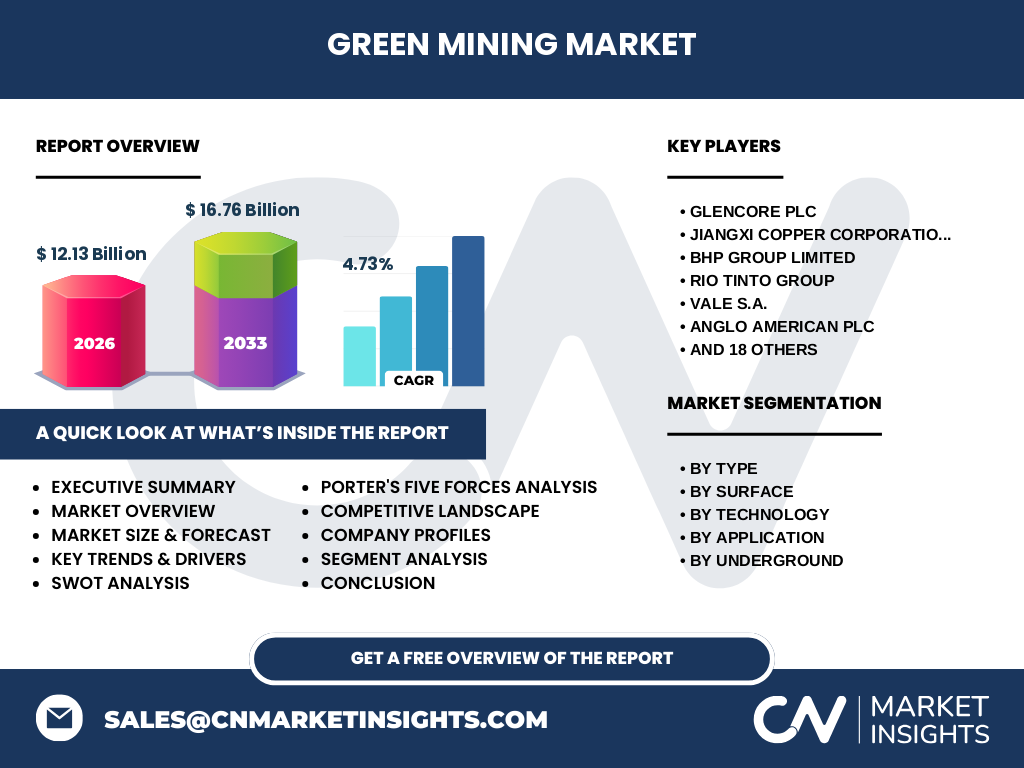
The Green Mining Market encompasses sustainable extraction methodologies designed to minimize environmental footprints across critical mineral value chains. Valued at $12.13 Billion in 2026, this sector integrates advanced technologies like power and water reduction to address stringent ESG mandates enforced by regulatory bodies such as the EPA and international mining councils.
Key market drivers, restraints, challenges, and opportunities shaping Green Mining Market
Growth is propelled by surging demand for transition metals like copper and lithium, driven by giants such as BHP Group Limited and Rio Tinto Group. However, high capital expenditures for electrification act as restraints. Opportunities lie in deploying proprietary emission-reduction algorithms across surface operations like open-pit and strip mining to lower compliance costs.
Emerging trends and growth patterns in Green Mining Market
Industry trends highlight a definitive pivot toward automated underground extraction, notably room and pillar and block caving methods. Our analysis indicates that companies prioritizing water-reduction technologies in arid jurisdictions achieve superior operational longevity. This structural shift redefines capital allocation toward closed-loop recycling and renewable microgrids at remote extraction sites.
COVID-19 impact analysis and recovery trajectory for Green Mining Market
Pandemic-induced supply chain bottlenecks temporarily stalled greenfield decarbonization projects. Yet, the recovery trajectory accelerated digital transformation. Industry leaders like Vale S.A. leveraged remote monitoring technologies during the downturn, ensuring a robust rebound that positions the sector for a 4.73% CAGR from 2027 onward.
Competitive landscape and strategic dynamics in Green Mining Market
The competitive landscape features high market concentration among Tier-1 operators including Glencore plc, Anglo American plc, and Freeport-McMoRan Inc. Strategic dynamics revolve around securing green premiums for responsibly sourced copper and gold. Majors are actively acquiring specialized clean-tech startups to protect their market share against tightening global decarbonization thresholds.
Executive summary of the Green Mining Market report overview
Our comprehensive research values the Green Mining Market industry trends at $12.13 Billion in 2026, expanding to $16.76 Billion by 2033 at a 4.73% CAGR. Decarbonization imperatives and technological adoption across surface and underground assets are the primary catalysts transforming traditional extraction into an ESG-compliant powerhouse.
Market forecast trajectory from 2027 to 2033
The market is projected to surge from $12.13 Billion in 2026 to reach $16.76 Billion by 2033, maintaining a steady 4.73% CAGR. This expansion is fueled by mandatory carbon-pricing mechanisms and escalating investor demand for sustainable copper, nickel, and iron ore production from firms like Newmont Corporation and Barrick Gold Corporation.
Segmentation analysis across operational and technological categories
The market segments by type into Surface (open-pit, strip, mountaintop removal) and Underground (room and pillar, longwall, block caving). Technology segments comprise power, emission, and water reduction applied across mining and exploration geology. Each segment requires tailored capital investments to meet regional environmental regulations.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with Latin America and Asia-Pacific leading in surface extraction volume, while North America and Europe prioritize underground electrification. Regional growth hinges on local mining codes, with jurisdictions like Western Australia enforcing stringent water-usage caps that mandate advanced reduction technology integration.
In-depth regional review of key operational hubs
Our regional audit reveals that South American operations, spearheaded by firms like Teck Resources Limited, face acute water scarcity, accelerating the adoption of dry-stack tailings. Simultaneously, Canadian and Nordic underground operations leverage hydroelectric microgrids to eliminate diesel particulate emissions, setting global benchmarks for sustainable extraction.
Company profiles and strategic positioning of leading participants
Industry leaders like Jiangxi Copper Corporation and Shandong Gold Mining Co. Ltd. focus on smelting efficiency, while diversified miners such as BHP Group Limited and Rio Tinto Group invest heavily in automated haulage fleets. These strategic positions insulate companies against carbon taxes while capturing premium pricing in downstream metal markets.
Porter's Five Forces analysis of the competitive environment
Bargaining power of buyers is moderate, constrained by scarce supply of low-carbon minerals. Threat of substitutes remains low due to the irreplaceable nature of mined transition metals. However, rivalry among established giants like Glencore plc and Vale S.A. is intense, driving continuous R&D investment in proprietary emission-reduction systems.
SWOT analysis highlighting strategic strengths and threats
Key strengths include robust asset portfolios held by firms like Newmont Corporation. Weaknesses involve high initial capital expenditures. Opportunities emerge from green-financing subsidies, while threats encompass shifting geopolitical trade barriers and stricter regulatory penalties for non-compliant surface operations.
Value chain analysis from raw materials to end-user delivery
The value chain spans geological exploration, extraction (surface and underground), processing, and refining. Value flows heavily toward eco-efficient processing nodes where firms utilize water-reduction systems to lower operational expenditures before shipping refined commodities to global manufacturing hubs.
Investment insights and high-potential growth areas
Investors should target technology providers specializing in underground ventilation heat recovery and automated electric fleet management. Companies like Lundin Mining Corporation and Kinross Gold Corporation showcase how early-stage ESG integration yields superior long-term valuations and lower cost-of-capital advantages.
Conclusion and key takeaways for industry stakeholders
The Green Mining Market market size expansion to $16.76 Billion by 2033 underscores that sustainability is no longer optional. Stakeholders must embed power and water reduction strategies directly into core extraction workflows to maintain social license to operate and capture premium market valuations.
Research methodology for baseline estimates and data triangulation
Our proprietary research methodology triangulates data by combining exhaustive trade registry filings, primary executive interviews with operators like First Quantum Minerals Ltd. and Yamana Gold Inc., and secondary macroeconomic indicators to ensure robust, verifiable market sizing through 2033.
Scope of the report, coverage parameters, and analytical limitations
This report covers global surface and underground extraction segments, technological subsets, and Tier-1 market participants through 2033. Limitations include potential unforeseen regulatory shifts in developing mining economies and localized disruptions in critical mineral supply chains.
Recent developments, strategic partnerships, and product launches
Recent milestones feature Anglo American plc launching hydrogen-powered haul trucks and Freeport-McMoRan Inc. expanding leaching technology partnerships. These strategic moves illustrate how industry leaders actively deploy capital to eliminate Scope 1 and Scope 2 emissions across their global operational footprints.